
Moomoo Insights
Jul 16 15:38
TSMC Earnings: AI Demand Is Stronger Than the Chip Selloff Suggests
Moomoo Insights
Sep 30 05:04
Live Take | Anthropic’s $518B Compute Bet: Who Wins From the AI Buildout?
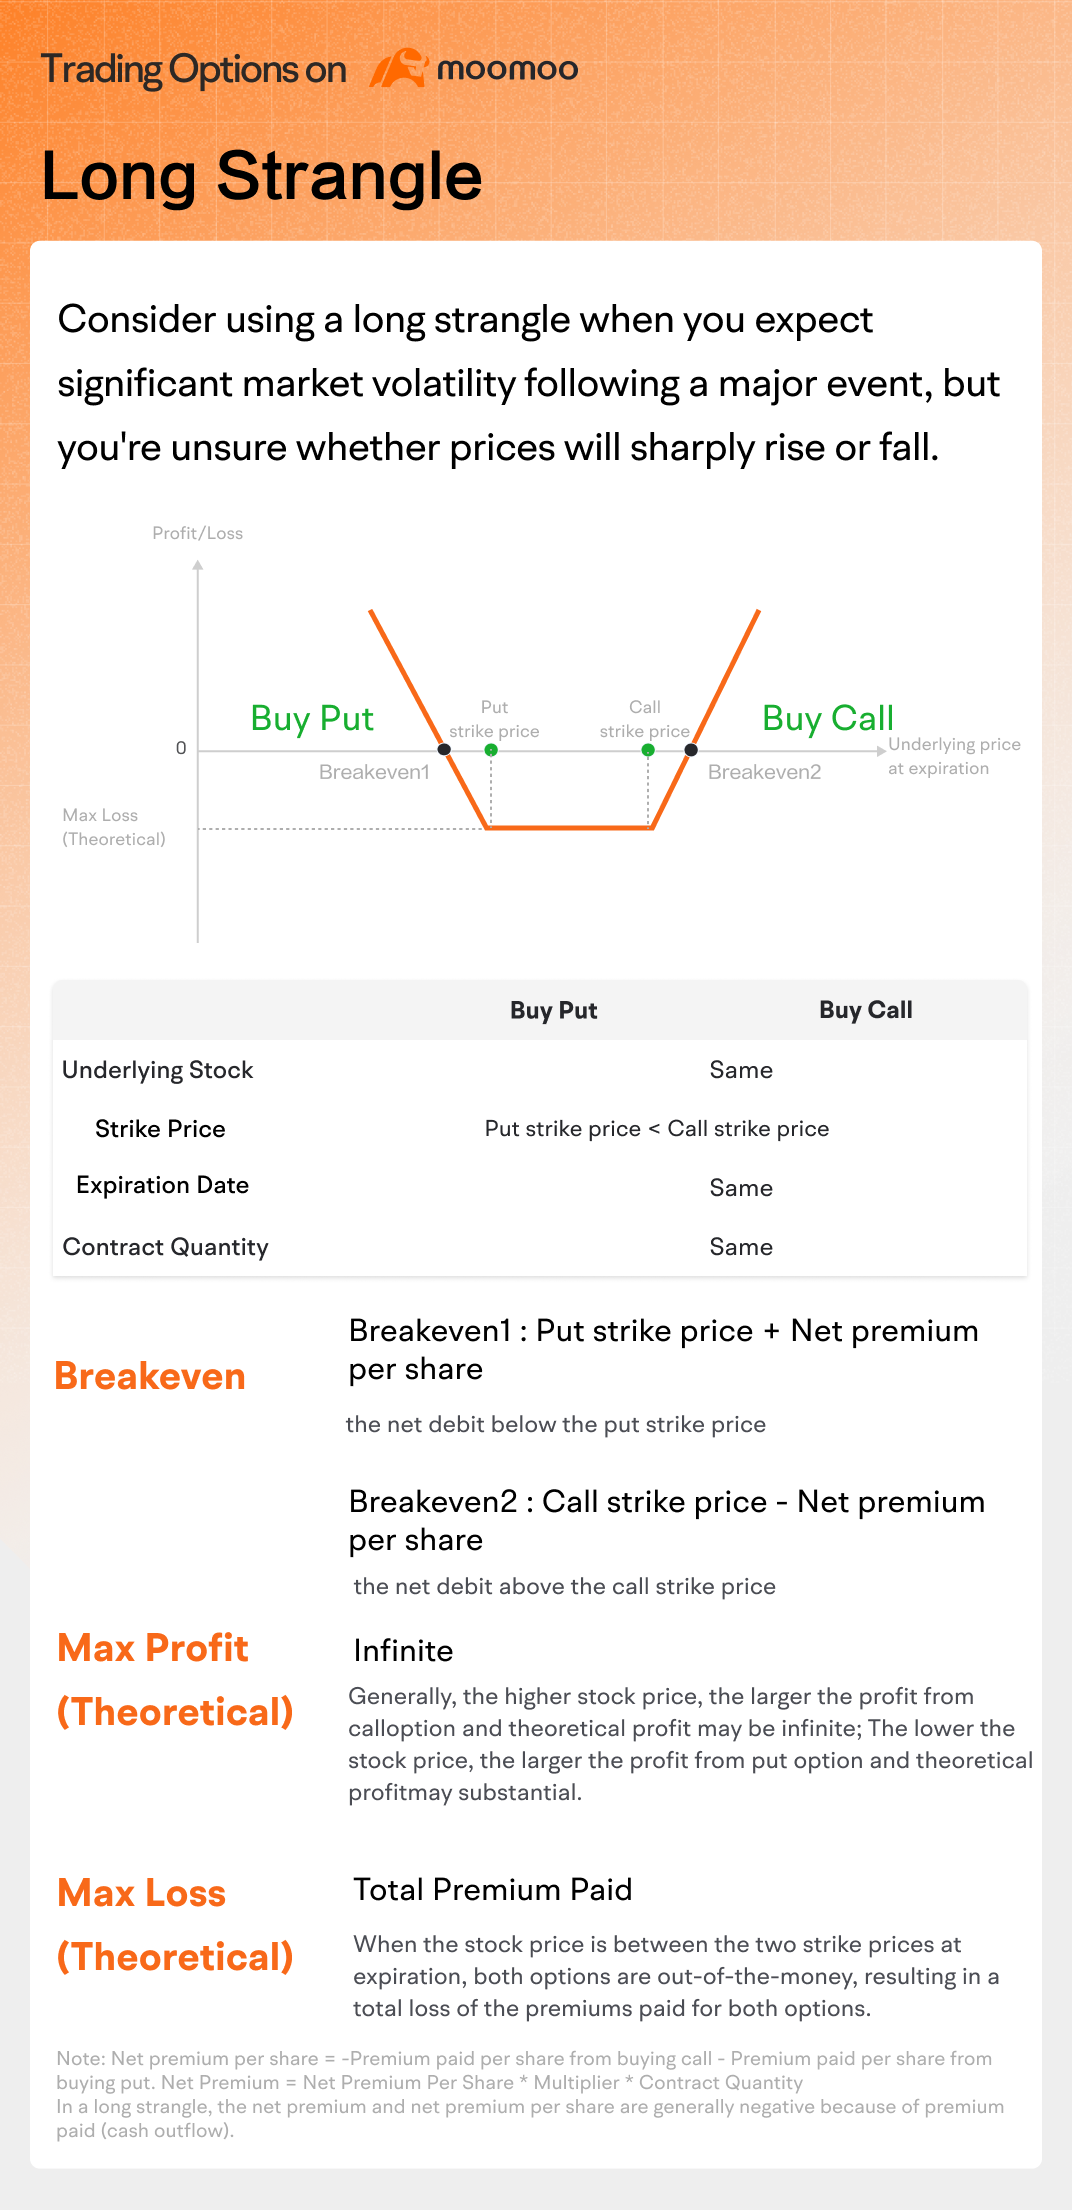
A long strangle is an options strategy used by traders expecting significant market volatility to follow a major event but are uncertain about the direction of the price movement.
By buying both out-of-the-money (OTM) put and call options simultaneously, traders aim to profit from large price swings while keeping the strategy's cost lower relative to buying at-the-money options.
「 Buy Put」+「Buy Call」
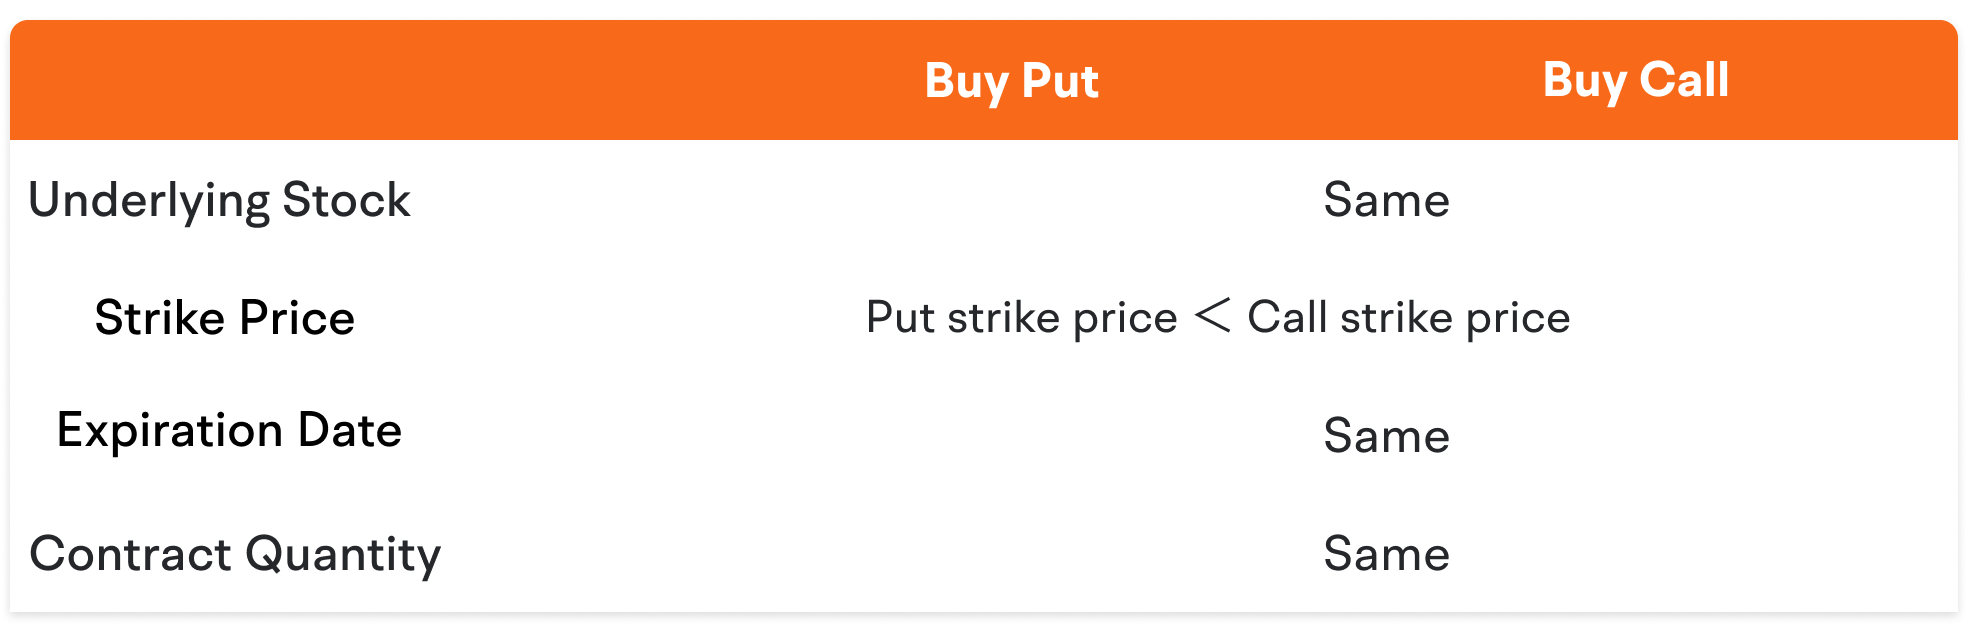
A long strangle is similar to a long straddle, involving call and put options on the same stock with the same expiration date and contract quantity.
However, in a long strangle, the put’s strike price is lower than the call’s. Both options are typically out-of-the-money, with the put strike below and the call strike above the current stock price.
The potential profit from a long strangle comes from simultaneously buying both put and call options. When the stock price falls, the put option price usually rises, and when the stock price rises, the call option price usually rises. If the total value of the strategy rises past the initial premium paid to open the position, the profit is realized when selling to close the position.
Whether the price goes up or down, as long as the magnitude of the move is large enough to offset the loss on one side with the gain on the other side, this strategy can be profitable.
Note: Maximum potential loss and profit for options are calculated based on the single leg or an entire multi-leg trade remaining intact until expiration with no option contracts being exercised or assigned. These figures do not account for a portion of a multi-leg strategy being changed or removed or the trader assuming a short or long position in the underlying stock at or before expiration. Therefore, it is possible to lose more than the theoretical max loss of a strategy.
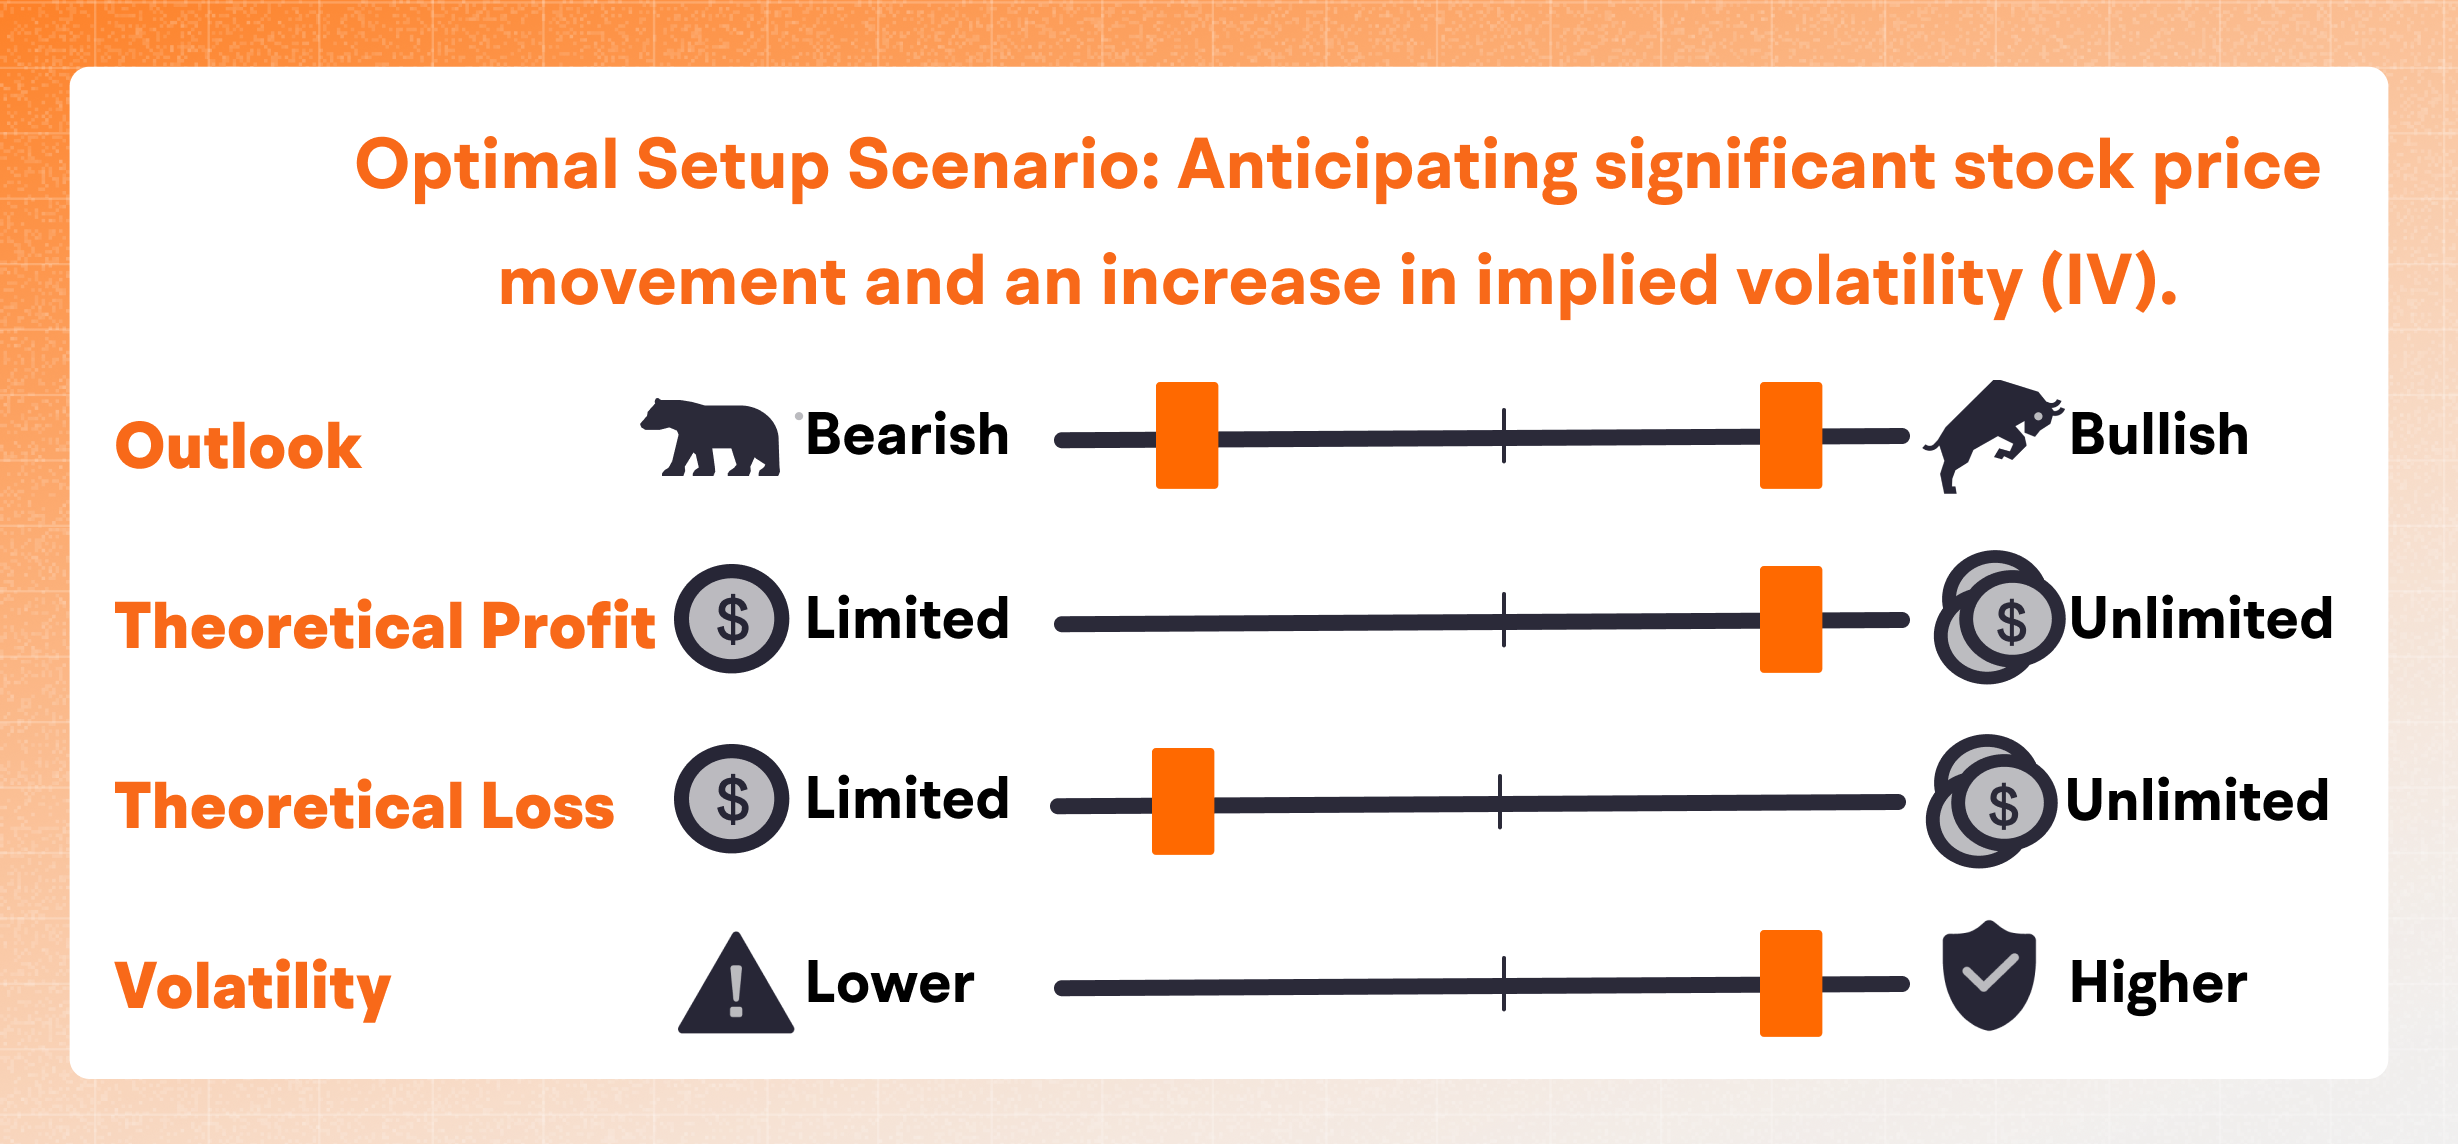
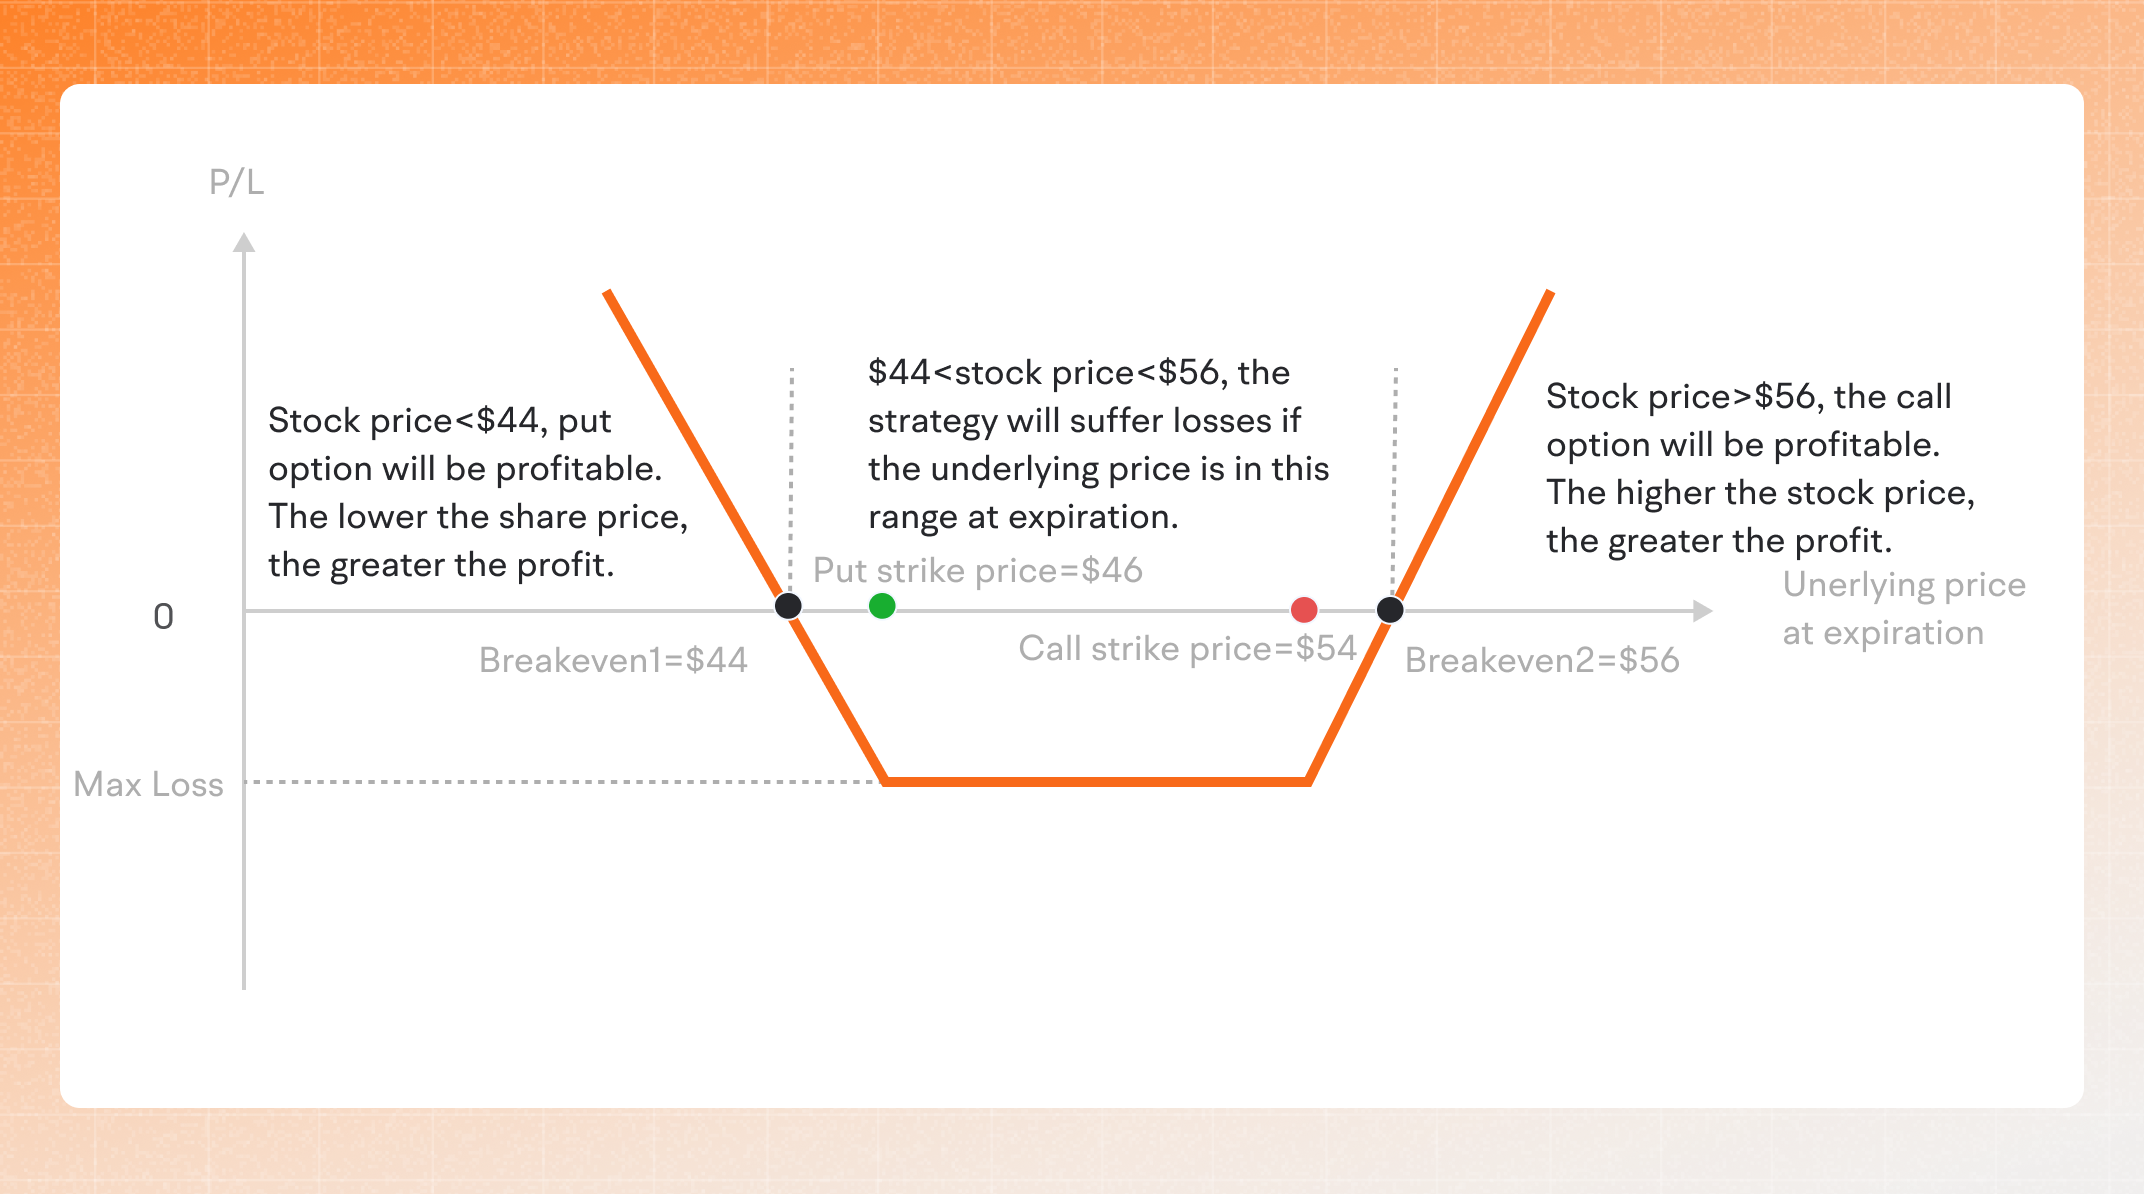
Favorable conditions: Significant price rise or fall. This strategy may be appropriate when a significant stock price movement is expected, but the direction is uncertain.
Unlimited Profit: Because you are the buyer of both a call and a put, you can potentially profit regardless of whether the stock price rises or falls. The greater the magnitude of the price movement, the higher the potential profit. Profit is only unlimited on the call side because the maximum profit on the put side is reached if the stock price falls to zero.
Limited Loss: When the put strike price < stock price < call strike price at expiration, both options are out-of-the-money, resulting in a loss of the entire premium paid. Theoretical Maximum Loss = total premium paid.
Higher Volatility: This strategy tends to benefit from high volatility. If the underlying asset's price does not change significantly by the expiration date, you may lose the entire premium paid.
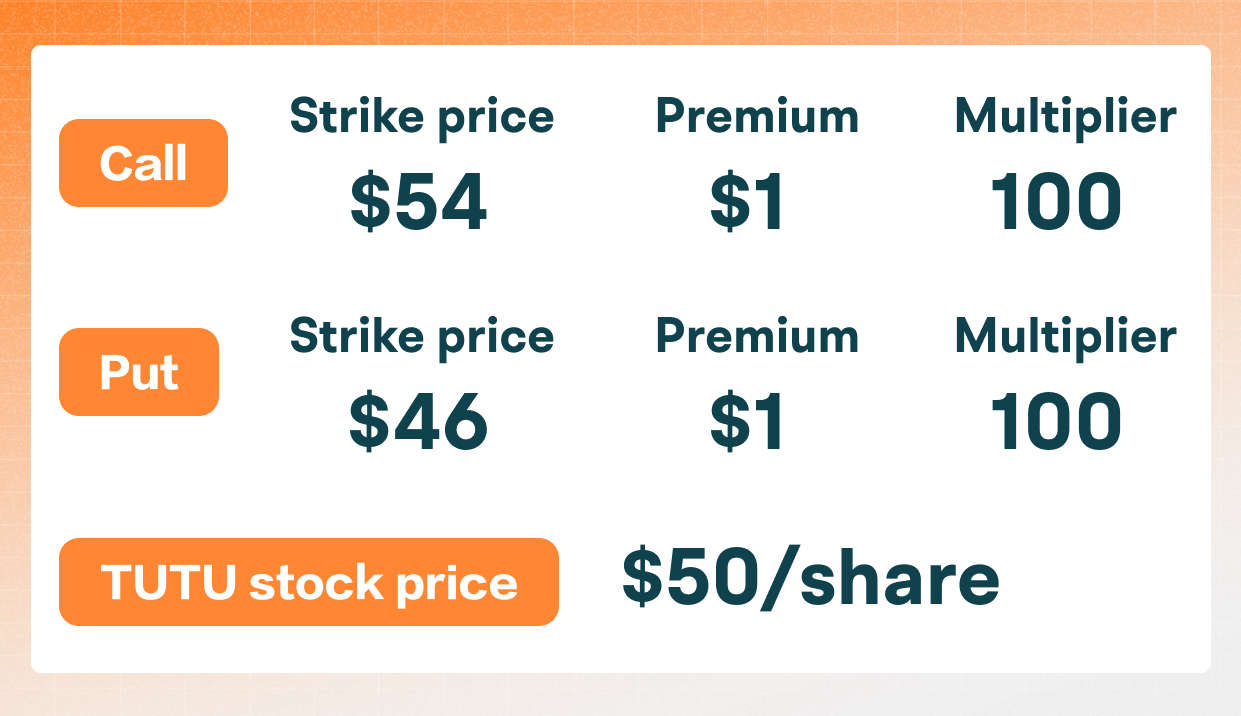
TUTU, our theoretical stock, is releasing its earnings report next week. You expect significant price volatility but aren't sure if the stock will rise or fall.
With TUTU's stock price at $50, you set up a long strangle strategy to prepare for potentially large price movements.
To have relatively lower initial setup costs, you choose to buy two OTM options: a call option with a strike price of $54 and a put option with a strike price of $46.
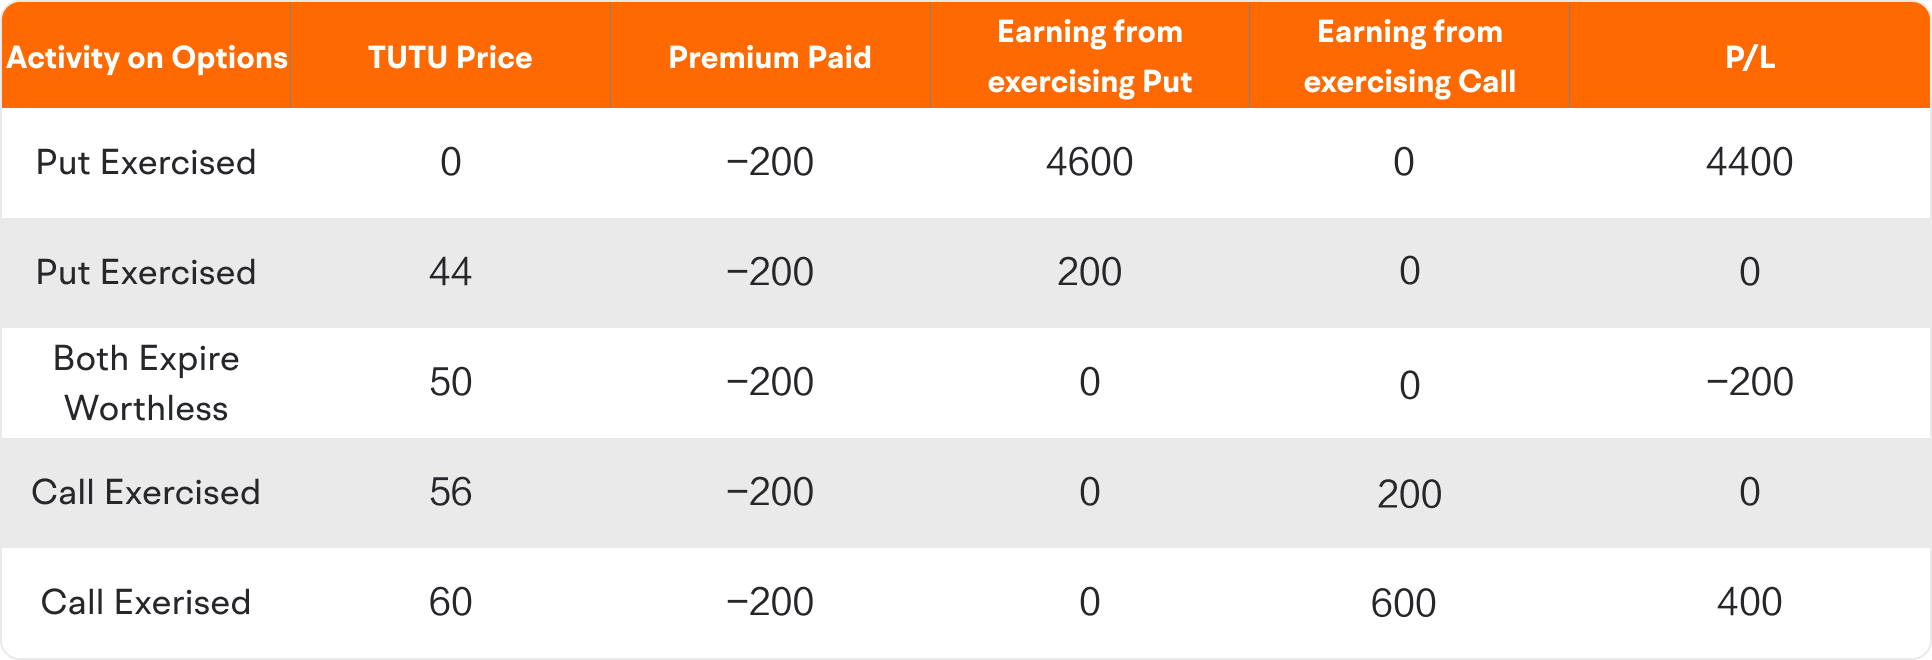
Cost of setting up the position:
Net premium from the put option: -$100 (-$1 paid per share).
Net premium from the call option: -$100 (-$1 paid per share).
Net premium in total: -$100 -$100=-$200 (-$2 paid per share).
In this case, the call option is out-of-the-money, while the put option is in-the-money.
If you choose to exercise the put option at expiration, you can sell TUTU stock for $46 and buy to close the short TUTU position at a cheaper price (assuming that the stock price remains unchanged from exercising the option to close the stock position).
When the stock price drops by the amount of the total premium paid per share at $44 (calculated as the $46 strike price minus the $2 total premium paid per share), the position reaches the lower breakeven. If the stock price continues to fall beyond this point, the strategy should yield higher positive returns.
You can also close the position before expiration. If the stock price drops significantly, the put option's value will likely increase more than the call option's value decreases. You can then try to sell both options at a higher net price to achieve a positive return.
In contrast to Scenario 1, in this case, the call option is in-the-money, while the put option is out-of-the-money.
If you choose to exercise the call option at expiration , you can buy TUTU stock at $54, which is now priced higher (assuming that the stock price remains unchanged from exercising the option to close the stock position).
When the stock price increases by the total premium paid per share, reaching $56 (calculated as the $54 strike price plus the $2 total premium paid per share), the stock price reaches the upper breakeven. As the stock price continues to rise, this strategy should yield higher positive returns.
You can also close the position before expiration. If the stock price rises significantly, the call option's value will likely increase more than the put option's value decreases. You can then try to sell both options at a higher net price than the initial cost, achieving a positive return overall.
If the stock price fluctuates between the lower breakeven and the upper breakeven through expiration, exercising the put or call options won't cover the cost of purchasing them, leading to a loss.
When $46 < stock price < $54, neither option yields any profit, and you lose the entire premium paid, resulting in the theoretical maximum loss of $200.
If the stock price has low fluctuations and you close the position before expiration and the stock price has low fluctuations, the options' value has likely decayed over time. This means the premium from selling the options may be less than the initial cost, resulting in a loss.
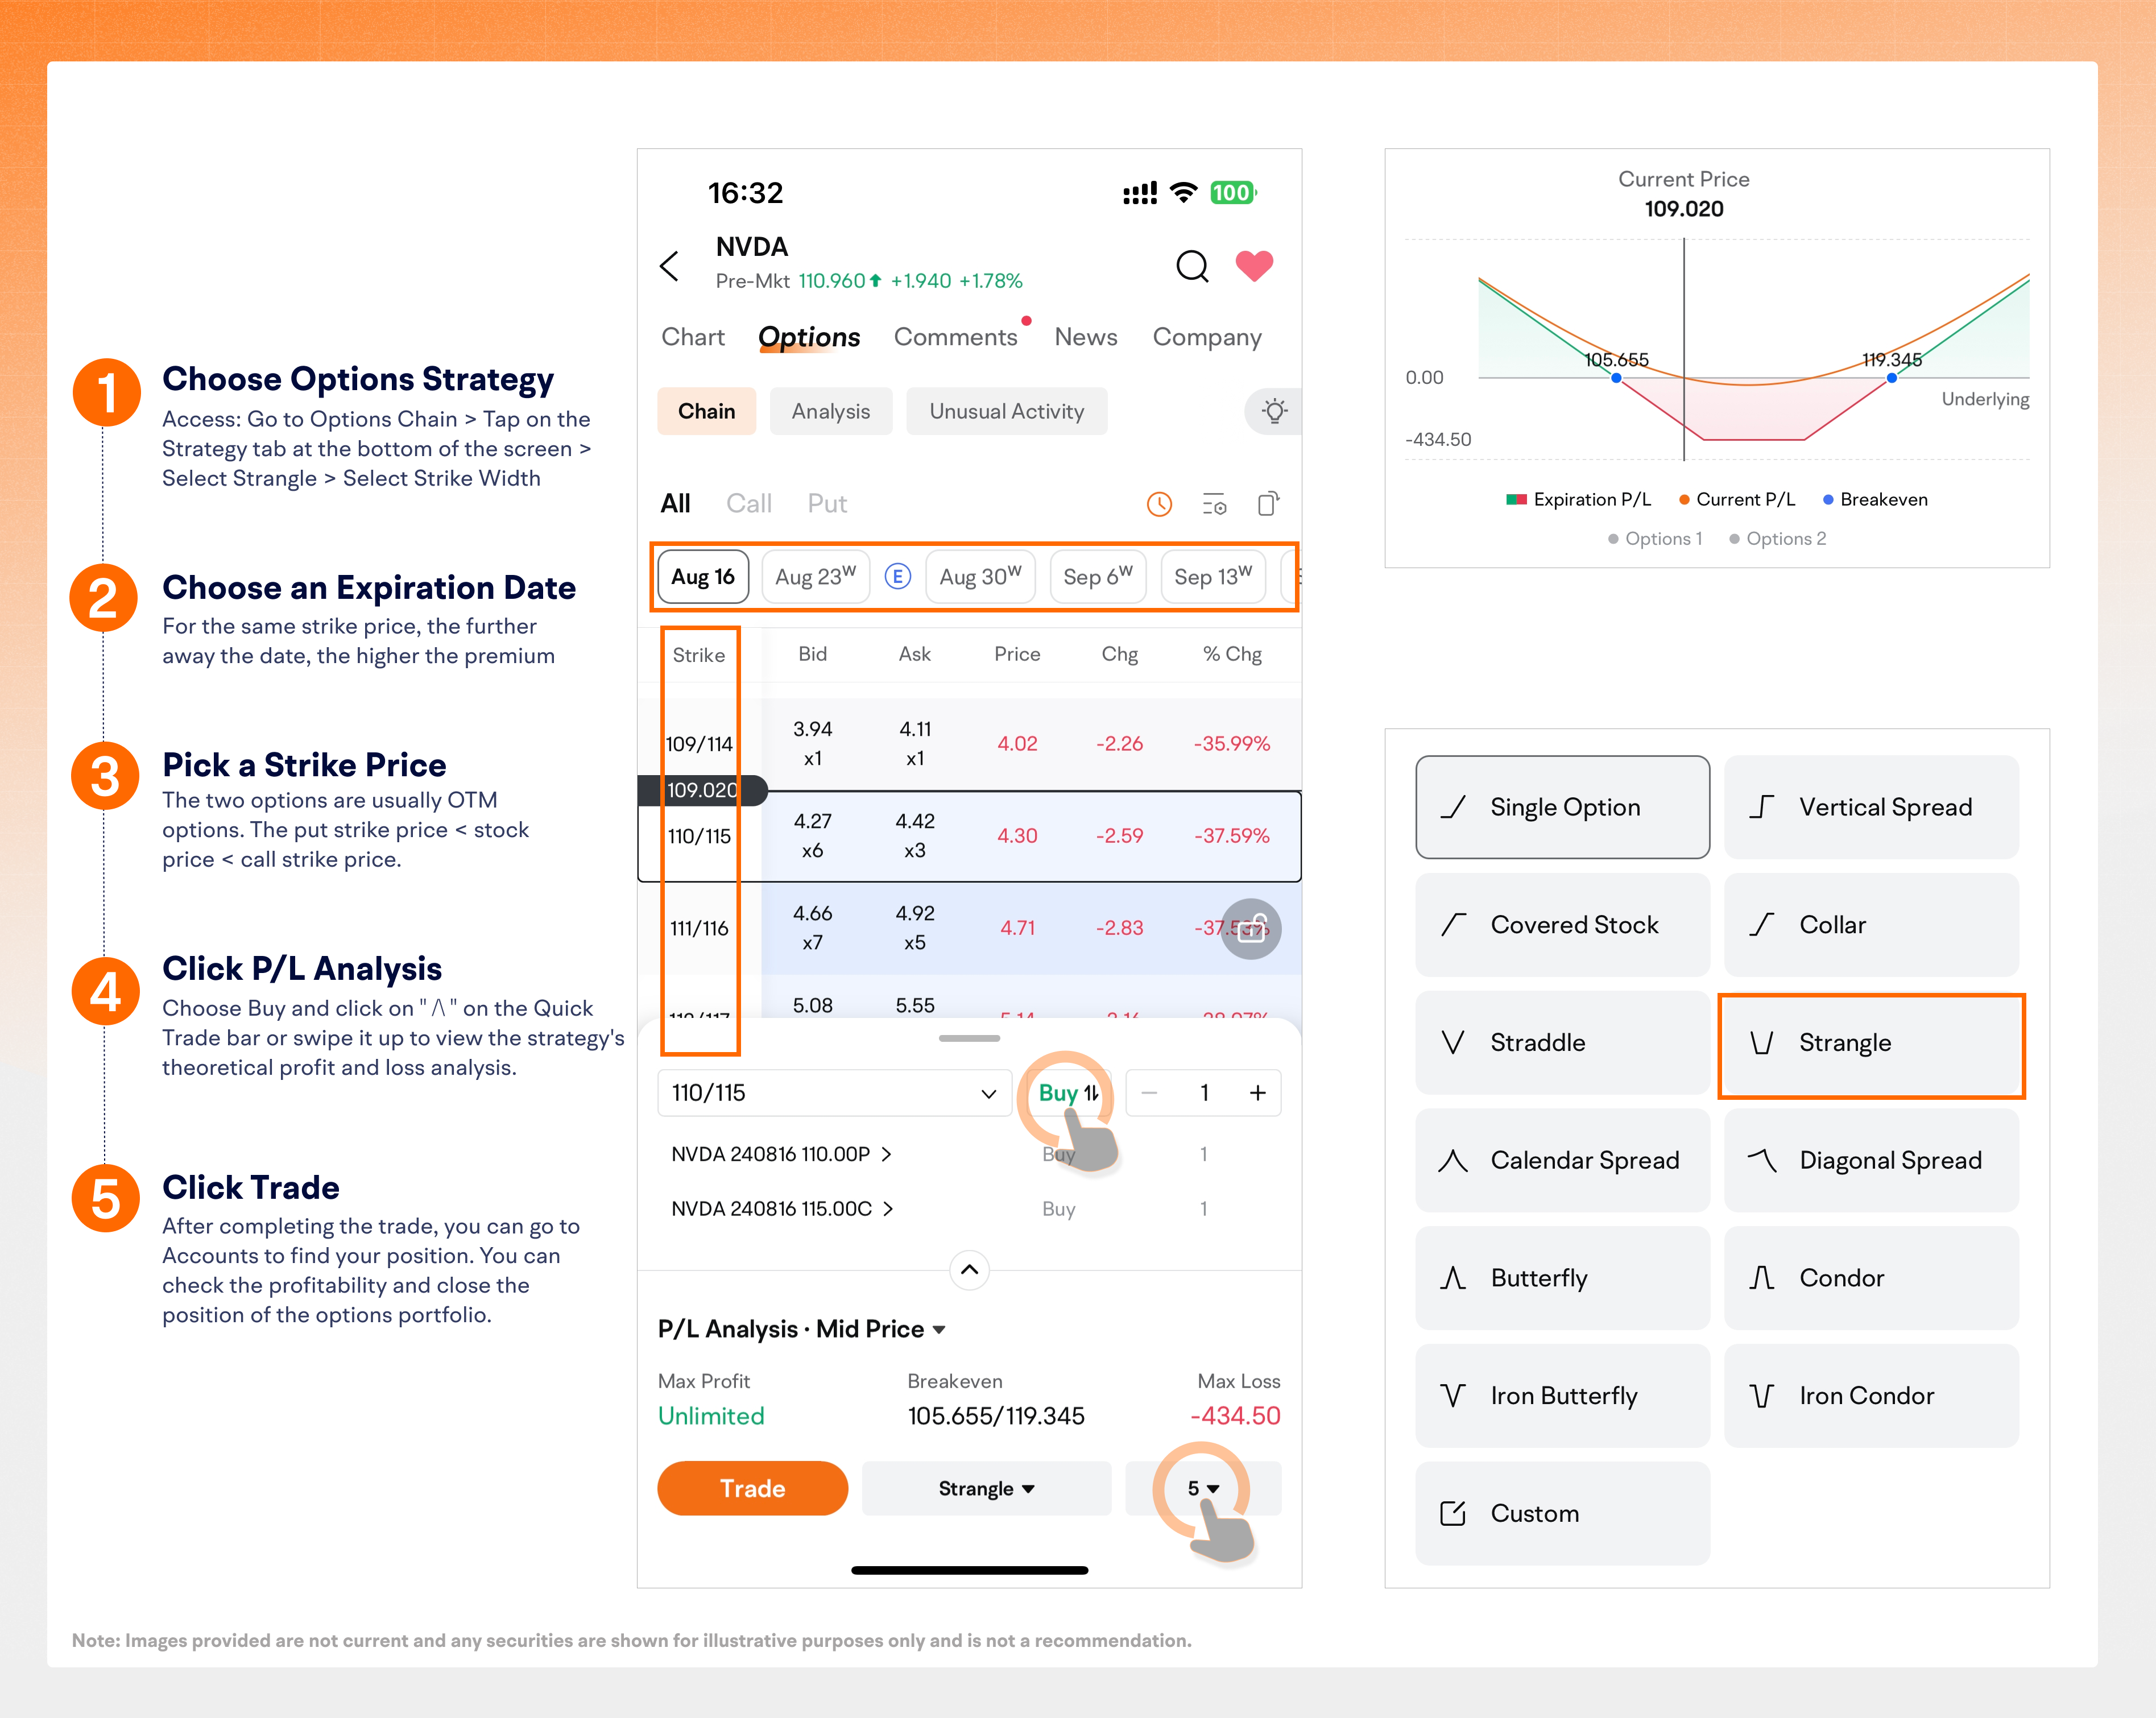
Go to Options Chain > Tap on the Strategy tab at the bottom of the screen > Select Strangle
Choosing Buy, the system will then automatically help you buy one put option and buy one call option, forming a long strangle.
Core Strategy: Delta Neutral + Long Vega
Delta neutral means the strategy is neutral to market movements (rises or falls), while long Vega indicates an expectation of increased volatility, i.e., anticipating significant price fluctuations in the market, regardless of the direction.
This strategy is commonly used when a major event is expected to cause substantial market volatility, and the direction of the price movement is uncertain. By holding both call and put options, you can potentially profit from a significant price movement in either direction.
Financial reports can have a significant impact on a company's stock price. Whether the impact is positive or negative, it may lead to substantial price fluctuations.
By constructing a long strangle, investors only need to anticipate significant price movement without having to predict the price direction.
Common practice:
Construct a long strangle before the financial report (when implied volatility is generally low).
Exit the position decisively at the time of the financial report release (when IV is generally high).
Events such as the Federal Reserve's interest rate decisions, CPI releases, elections, and policy changes can also lead to significant market fluctuations.
Through a strangle options strategy, investors can invest in this potential volatility without needing to predict the specific direction of the impact.
The long strangle strategy is also used in intraday trading. Typically, during certain periods, such as after the market opens or just before closes, market volatility tends to increase, making it difficult to predict stock price movements.
By constructing a long strangle strategy, traders seek to capture intraday price movements with minimal time value decay.
If market volatility is low, since intraday trades are typically closed within the same day, the potential loss from time decay is usually smaller than holding for a longer date.
If market volatility is high, investors that match this sentiment can potentially achieve gains.
 Q: What are the differences between long strangle and long straddle (Choosing strike prices)?
A: There is no fundamental difference between the two strategies; the distinction lies in the choice of strike prices. A long straddle typically involves buying two ATM (at-the-money) options, while a long strangle usually involves buying two OTM (out-of-the-money) options.
To try to create delta neutrality, the strike price of the call and put options should be equidistant from the stock price. The larger the difference between the call and put strike prices, the cheaper the initial cost of the position, but it usually requires a larger price movement to reach the profit range. The smaller the difference between the strike prices, the higher the initial cost, but usually a smaller price movement is required to reach the profit range. When the difference in strike prices is reduced to 0, it essentially becomes a long straddle strategy. Therefore, a long straddle can be considered a specific type of long strangle.
The choice of strike price difference determines the distance between the two breakevens, so it is very important to estimate the future volatility of the stock price. You can refer to the Expected Move value to estimate the market's current expectations of stock price volatility, and choose the distance between the strike prices and the current stock price.
Long Strangle | Long Straddle | |
Strike price | Different, put strike price <call strike price and put and call are usually OTM | Same, put strike price = call strike price and put and call are usually ATM |
Premium paid | Less, so the theoretical maximum loss is smaller | More, so the theoretical maximum loss is larger |
Profit possibility | The distance between the two breakeven points is larger, so greater stock price volatility is required to reach the profit range, making the profit probability relatively lower. | The distance between the two breakeven points is smaller, so less stock price volatility is required to reach the profit range compared to a long strangle, making the profit probability relatively higher. |
Q: Choosing an expiration date
A: As this strategy is more appropriate for short-term speculation in response to market changes, most investors usually choose shorter expiration dates in order to reduce the impact of time value decay.
Q: If the position shows a gain, how can we realize profits?
A: When a long strangle strategy is already profitable on paper, it usually indicates that the stock price has experienced significant one-sided movement. Assuming the value has exceeded the net debit paid, you can choose to close the position early to lock in profits, rather than hold it until expiration. This approach helps to avoid further time value decay of options.
Q: If the position suffers loss, what measures can be taken?
 Method 1: Close the position
If IV is low, the value of call and put options will quickly diminish over time. To avoid losing the entire premium, you can consider incurring some losses and proactively close the position before the expiration date.
Method 2: Strategy adjustment
For some conservative investors, the strategy can be adjusted to a long iron condor by adding two legs: selling a call with a higher strike price and a put with a lower strike price.
By doing so, you would be reducing the initial cost of the trade but capping potential profits.
Method 3: Rollover
Close the current position, realize the loss and open the position of call and put with further expiration dates.
You can also adjust the strike prices through the rollover to match your investment objectives.
This presentation is for informational and educational use only and is not a recommendation or endorsement of any particular investment or investment strategy. Investment information provided in this content is general in nature, strictly for illustrative purposes, and may not be appropriate for all investors. Read more
Recommend
How Short Put Works: Earning Premiums with Options
How the Options Market Can Signal When Earnings Events Are Too Risky to Trade
Options Earnings Series 1: What's Behind the Rise and Fall of Stock Prices After Earnings?

Options Earnings Series 2: Option Buying and Selling Strategies for Earnings
Options Earnings Series 3: Exploring Common Two-Legged Option Strategies for Earnings Season
Never Be Surprised Again: Understand the Eight Common Market Reactions to Earnings
Why Stocks Drop After Beating Earnings: 6 Key Reasons Behind the Post-Earnings Slump
Earnings unlocked: how options might enhance your trading approach
What should options buyers do if they no longer want to exercise their options?
Why did options buyers' exercise request fail?
A Closer Look at 0DTE Options: Short-Term Trading Explained
Approaching Post-Earnings IV Crush With Options
How to Hedge a Market Downturn with Options:Here's what you need to know
A Guide to the Long Put Strategy: Basics You Need to Know
Understanding Witching Days: What Investors and Traders Need to Know
Understanding Implied Volatility in Options Trading
Discovering Protective Puts: A Beginner's Guide
Why Investors May Consider Cash-Secured Puts in a Downturn
Why Pre-Earnings Volatility Attracts Option Traders
The Wheel Strategy: An Income Generating Options Strategy
What's next for a Short Put?
Long Call Options Strategy: Definition, Potential Benefits, and Risks
Short Put Options Strategy in Options Trading
How to set up a Short Put on moomoo?
What's next for a Long Put?
What is a Short Put?
Who are involved in the option exercise process?
Essential rules to understand about exercising options
When should options buyers exercise?
How can options sellers manage risk?
How does options buyers exercise their option?
What is XSP®
Closing vs. Exercising Options: What's the difference?
What's next for a Short Call?
How to set up a Short Call on moomoo
What is a Short Call?
What's next for a Long Call?
Understanding the Benefits of Index Options
XSP® vs SPY®
XSP® Use Cases
How to set up a Long Call on moomoo?
What is SPX®
Dispelling the Myths of Trading Index Options
What is a Long Call?
Short Put Butterfly
What Are Index Options and How Do They Work
Long Diagonal Bull Call Spread
Short Diagonal Bull Put Spread
Long Diagonal Bear Put Spread
Short Diagonal Bear Call Spread
Long Call Butterfly
Short Iron Butterfly
Short Call Butterfly
Long Put Butterfly
Bear Call Spread
Short Iron Condor
Covered Put
Short Put Condor
Bull Put Spread
Bull Call Spread
Long Collar
Short Strangle
Long Strangle
Long Iron Butterfly
Protective Put
Long Iron Condor
Long Put
Short Straddle
Short Call
Cash-Secured Put
Short Put
Long call
Index Options: An Introduction for Traders
Protective Call
Long Call Condor
Short Call Condor
Long Straddle
Long Put Condor
Short Collar
Bear Put Spread
Covered Call
How Short Put Works: Earning Premiums with Options
How the Options Market Can Signal When Earnings Events Are Too Risky to Trade
Options Earnings Series 1: What's Behind the Rise and Fall of Stock Prices After Earnings?
Options Earnings Series 2: Option Buying and Selling Strategies for Earnings
Options Earnings Series 3: Exploring Common Two-Legged Option Strategies for Earnings Season
Never Be Surprised Again: Understand the Eight Common Market Reactions to Earnings
Why Stocks Drop After Beating Earnings: 6 Key Reasons Behind the Post-Earnings Slump
Earnings unlocked: how options might enhance your trading approach
What should options buyers do if they no longer want to exercise their options?
Why did options buyers' exercise request fail?
A Closer Look at 0DTE Options: Short-Term Trading Explained
Approaching Post-Earnings IV Crush With Options
How to Hedge a Market Downturn with Options:Here's what you need to know
A Guide to the Long Put Strategy: Basics You Need to Know
Understanding Witching Days: What Investors and Traders Need to Know
Understanding Implied Volatility in Options Trading
Discovering Protective Puts: A Beginner's Guide
Why Investors May Consider Cash-Secured Puts in a Downturn
Why Pre-Earnings Volatility Attracts Option Traders
The Wheel Strategy: An Income Generating Options Strategy
What's next for a Short Put?
Long Call Options Strategy: Definition, Potential Benefits, and Risks
Short Put Options Strategy in Options Trading
How to set up a Short Put on moomoo?
What's next for a Long Put?
What is a Short Put?
Who are involved in the option exercise process?
Essential rules to understand about exercising options
When should options buyers exercise?
How can options sellers manage risk?
How does options buyers exercise their option?
What is XSP®
Closing vs. Exercising Options: What's the difference?
What's next for a Short Call?
How to set up a Short Call on moomoo
What is a Short Call?
What's next for a Long Call?
Understanding the Benefits of Index Options
XSP® vs SPY®
XSP® Use Cases
How to set up a Long Call on moomoo?
What is SPX®
Dispelling the Myths of Trading Index Options
What is a Long Call?
Short Put Butterfly
What Are Index Options and How Do They Work
Long Diagonal Bull Call Spread
Short Diagonal Bull Put Spread
Long Diagonal Bear Put Spread
Short Diagonal Bear Call Spread
Long Call Butterfly
Short Iron Butterfly
Short Call Butterfly
Long Put Butterfly
Bear Call Spread
Short Iron Condor
Covered Put
Short Put Condor
Bull Put Spread
Bull Call Spread
Long Collar
Short Strangle
Long Strangle
Long Iron Butterfly
Protective Put
Long Iron Condor
Long Put
Short Straddle
Short Call
Cash-Secured Put
Short Put
Long call
Index Options: An Introduction for Traders
Protective Call
Long Call Condor
Short Call Condor
Long Straddle
Long Put Condor
Short Collar
Bear Put Spread
Covered Call

