RRSP Calculator 2026: Estimate Your Tax Refund & Future Savings
As the March 2, 2026, contribution deadline approaches, many Canadians are asking the same question: How much should I contribute to actually see a difference on my tax return? While guessing might lead to missed opportunities, using a professional RRSP calculator allows you to turn tax season stress into a strategic wealth-building plan.
Whether you are looking for an RRSP return calculator to project your growth over the next thirty years or an RRSP contribution calculator to see exactly how much you can save on your 2025 taxes, having the right data is essential. In this guide, we’ll explore how to use an RRSP calculator Canada edition to navigate provincial tax brackets, avoid over-contribution penalties, and ensure your retirement nest egg is on track for the future.
Why You Need an RRSP Calculator in Canada for 2026
As we approach the March 2, 2026 deadline, the financial landscape in Canada has shifted. With updated federal tax brackets now in full effect—including the reduction of the lowest tax rate to 14%—relying on old "rules of thumb" is no longer enough. An RRSP canada calculator is a vital tool for 2026 because it provides the precision needed to navigate these three critical areas:
1. Navigating New Tax Brackets
In 2026, federal and provincial tax thresholds have been adjusted for inflation. A standard RRSP calculator helps you pinpoint exactly where your income falls within these new brackets. For instance, if your 2025 income puts you just inside a higher tax bracket (such as the 20.5% or 26% federal tier), a calculated contribution can "drop" your taxable income into a lower bracket, significantly increasing the value of every dollar you save.
2. Strategic "First 60 Days" Planning
The "First 60 Days" rule is your last chance to influence your 2025 tax bill. By using an RRSP Canada calculator during January or February 2026, you can perform a "stress test" on your finances. You can see the immediate impact of a $5,000 versus a $10,000 contribution on your potential refund, allowing you to make an informed decision before the window closes on March 2.
3. Avoiding Costly Over-Contribution Penalties
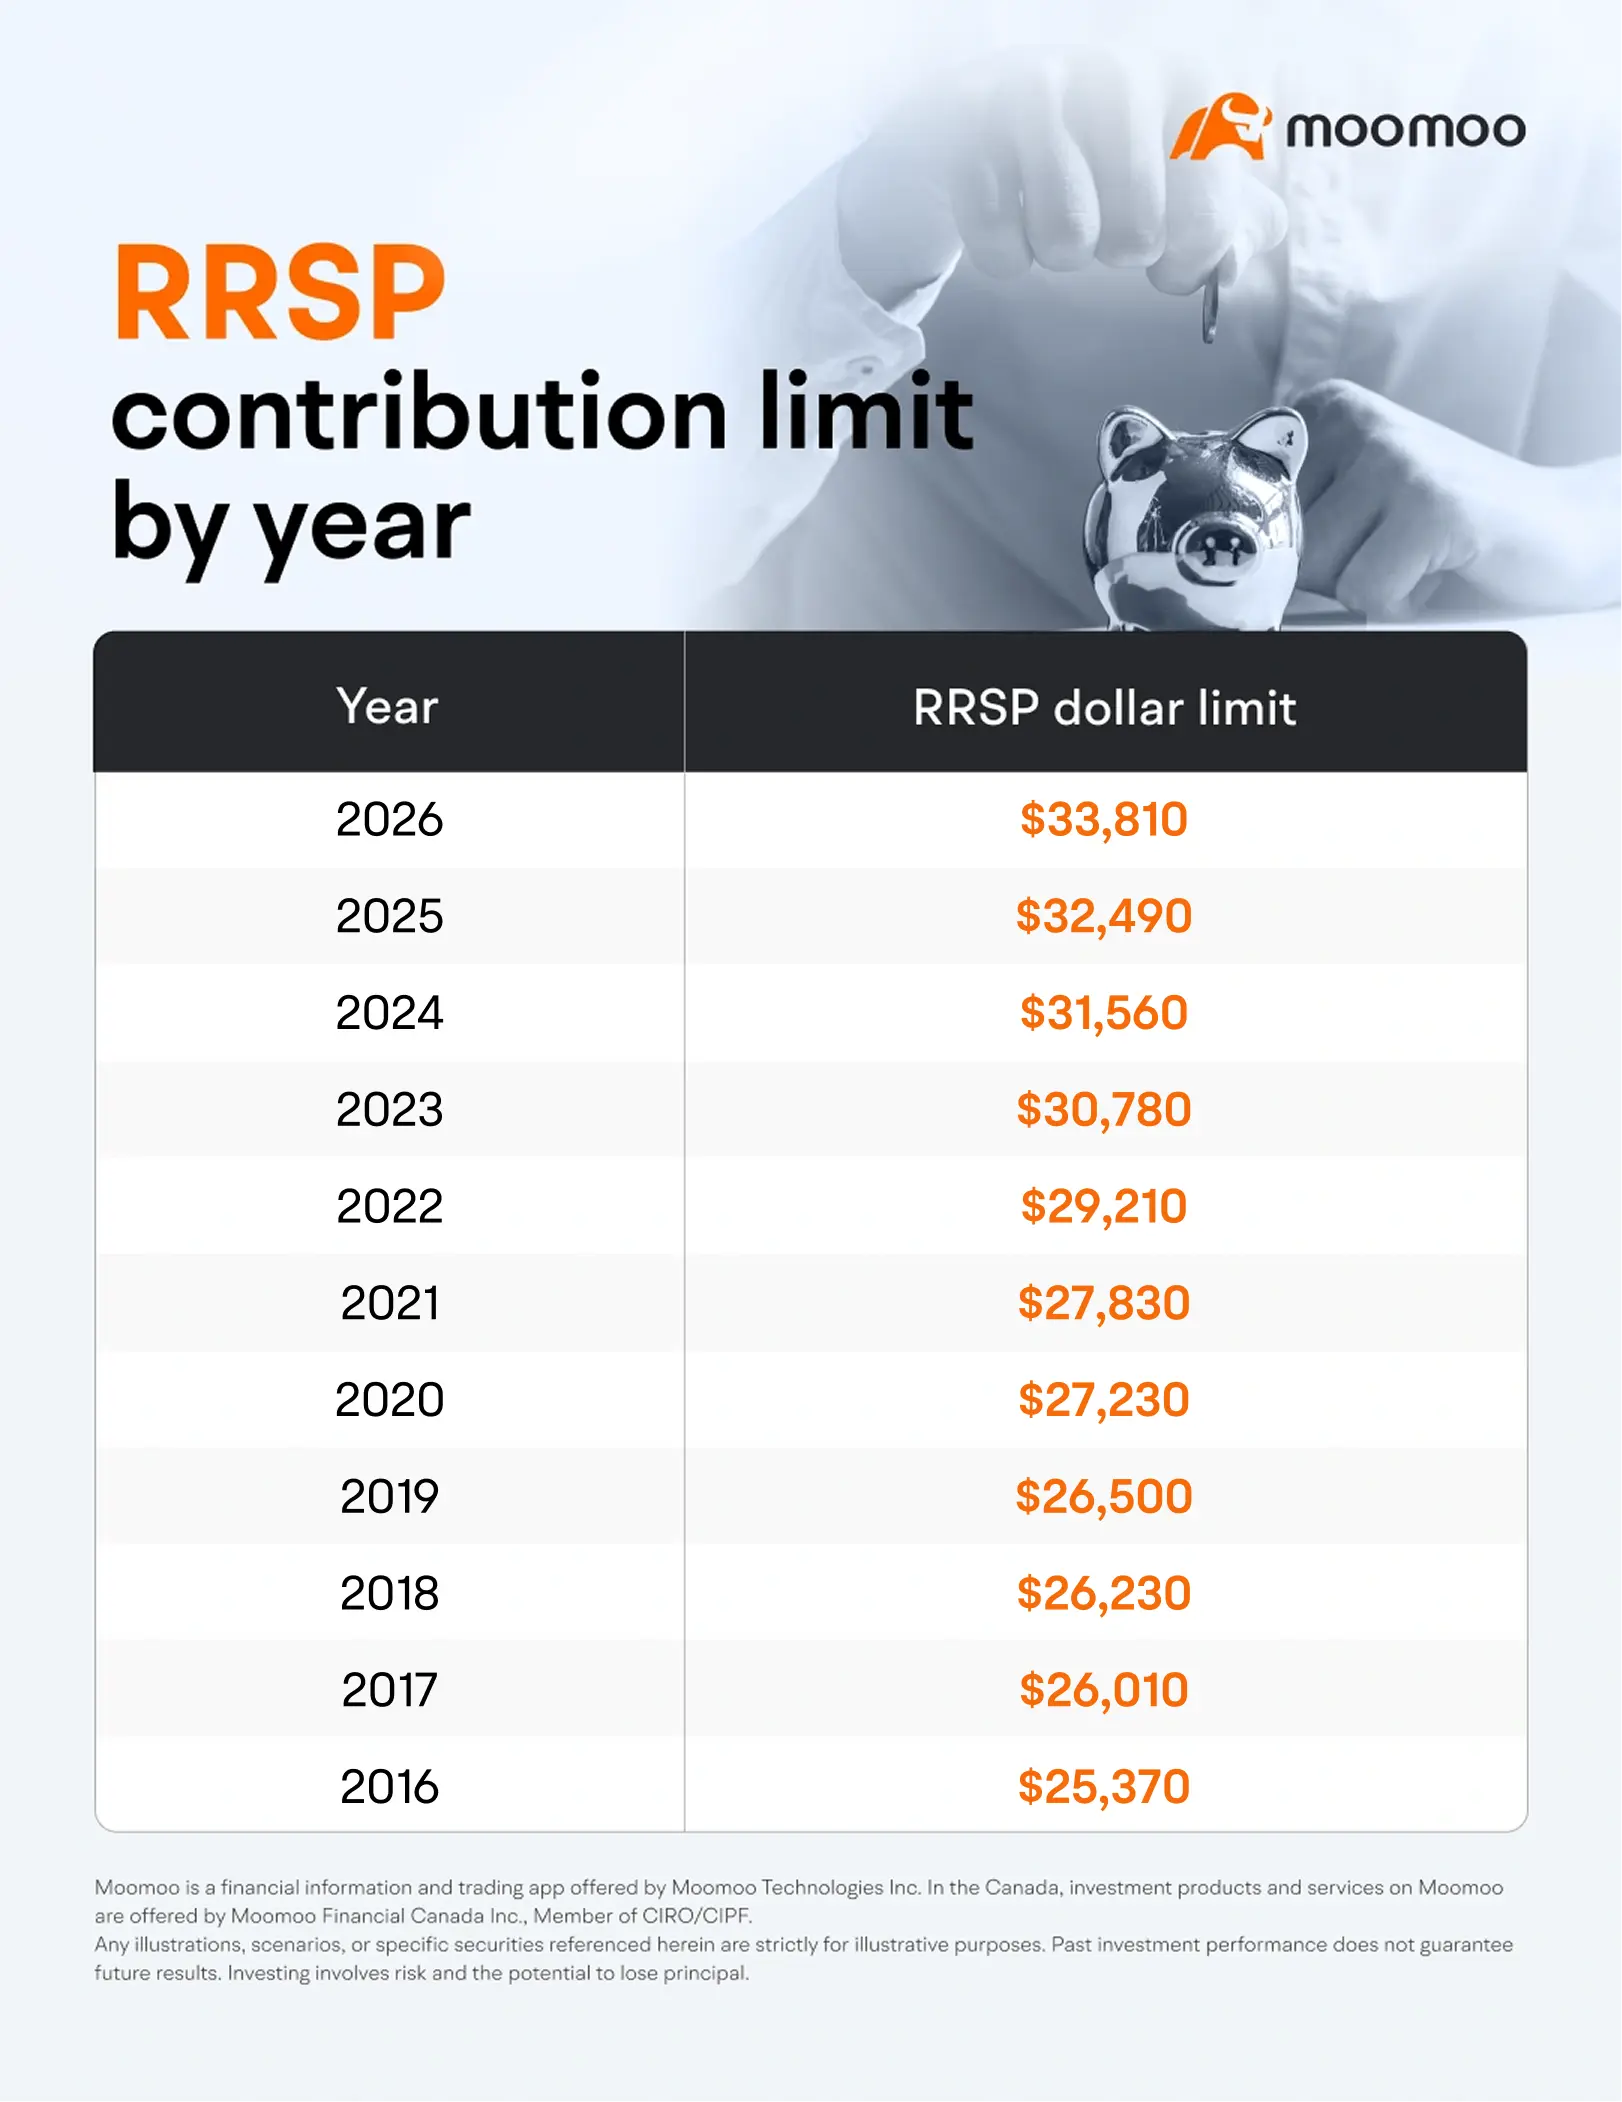
With the 2025 annual limit set at $32,490 and the 2026 limit rising to $33,810, keeping track of your "room" is more complex than ever. An RRSP calculator helps you integrate your current year's limits with any unused room carried forward from your Notice of Assessment (NOA). This prevents you from exceeding the $2,000 lifetime "buffer" and triggering the CRA’s 1% monthly penalty tax on excess contributions.
Moomoo Advantage: Tracking your contribution room shouldn't be a guessing game. Platforms like moomoo Canada allow you to monitor your RRSP and SRRSP (Spousal RRSP) activities in real-time. Also, moomoo Canada offers 24/7 online inquiry support via in-app chat and email for instant help.
How to Use an RRSP Contribution Calculator to Lower Your Taxes
To maximize your tax savings for the 2025-2026 season, understanding the mechanics of an RRSP contribution calculator is essential. This tool does more than just track savings; it acts as a strategic guide to help you decide exactly how much of your hard-earned money should be moved into your RRSP to minimize what you owe the CRA.
Step 1: Determine Your Marginal Tax Rate
The primary function of an RRSP contribution calculator is to identify your marginal tax rate. Because Canada uses a progressive tax system, your "top" dollars are taxed at a higher rate than your "bottom" dollars. By inputting your total annual income, the RRSP contribution calculator can show you how a deduction can lower your taxable income, potentially moving you into a lower tax bracket.
Step 2: Input the 2025 and 2026 Limits
Precision is key when using an RRSP estimator. For the current cycles, you need to be aware of the following ceilings:
2025 RRSP Limit: $32,490
2026 RRSP Limit: $33,810 A reliable RRSP contribution calculator will help you factor in these limits along with any "unused room" carried forward from previous years, ensuring you don't trigger over-contribution penalties.
Step 3: Calculate the "Tax Refund Effect"
The most rewarding part of using an RRSP contribution calculator is seeing your estimated refund in real-time. For example, if you are in a 40% tax bracket, a $10,000 RRSP contribution could effectively "buy" you a $4,000 tax refund. The RRSP calc helps you visualize this immediate return on investment, which many Canadians then choose to reinvest back into their RRSP or a TFSA to accelerate their wealth building.
Once your RRSP contribution calculator reveals your potential refund, the next step is execution. moomoo Canada makes it easy to open an RRSP with $0 account maintenance fees and $0 annual fees, meaning 100% of your tax-advantaged contribution goes directly toward your investments rather than administrative costs. This cost-efficiency is critical for maximizing the "net" benefit of your tax deduction.
Step 4: The "First 60 Days" Strategy
Between January 1st and the March 2, 2026 deadline, you have a unique tactical window. You can use your RRSP contribution calculator to perform "what-if" scenarios. By adjusting the contribution amount in the RRSP estimator, you can find the "sweet spot" where you maximize your refund without tying up more liquidity than necessary.
Pro-Tip: When using an RRSP contribution calculator, always ensure you are using your "Taxable Income" (Line 26000 of your return) rather than your gross salary for the most accurate results.
RRSP Return Calculator: Visualizing Your Long-Term Growth
While a tax refund is a great short-term win, the true power of an RRSP lies in its ability to act as a long-term wealth engine. An RRSP return calculator allows you to look past this year's tax filing and visualize how consistent contributions can transform into a substantial retirement nest egg through the power of tax-deferred compounding.
The Power of Tax-Deferred Compounding
The biggest advantage of using an RRSP return calculator is seeing the impact of "tax-free growth" over time. In a standard taxable account, you are taxed annually on interest, dividends, and capital gains, which acts as a "drag" on your portfolio. Within an RRSP, every dollar earned stays in the account to be reinvested.
An RRSP savings calculator often demonstrates that even a modest 5% to 7% annual return can lead to nearly double the wealth over 30 years compared to a non-registered account, simply because you aren't losing a portion of your gains to the CRA every year.
"Refund Recycling": The Secret to Exponential Growth
One of the most effective ways to use an RRSP return calculator is to model a strategy called "refund recycling." Instead of spending your tax refund, you reinvest it back into your RRSP.
The Cycle: Your initial contribution triggers a refund $\rightarrow$ You reinvest that refund before the next RRSP deadline $\rightarrow$ That new contribution triggers another (albeit smaller) refund the following year.
The Result: This creates a compounding "snowball effect" that can accelerate your retirement date by years.
Stress-Testing Your Assumptions
A high-quality RRSP return calculator allows you to toggle different variables to see how your future changes. By adjusting your RRSP calc inputs for different rates of return or retirement ages, you can answer critical questions like:
"What happens if I increase my monthly contribution by just $100?"
"How does a 1% difference in investment fees impact my total RRSP balance over 25 years?"
"If I delay my retirement by two years, how much more can my RRSP grow?"
By using an RRSP estimator to visualize these scenarios today, you can move from "guessing" about your future to "knowing" exactly what steps you need to take before the 2026 deadline.
>> Learn more: RRSP Growth Calculator: Maximize Your Retirement Savings
How Much RRSP Should I Have at 50?
Turning 50 is often described as the "financial home stretch." It is the decade where your earning potential typically peaks, and your focus shifts from wealth accumulation to retirement readiness. But how do you know if your RRSP is actually on track? While every financial journey is unique, 2026 benchmarks provide a clear set of goalposts to measure your progress.
The "6x Salary" Rule of Thumb
A widely accepted guideline for Canadian investors is the salary-multiple milestone. By age 50, financial experts suggest you should aim to have six times (6x) your annual gross salary saved for retirement.
Example: If you earn $100,000 per year, your target RRSP balance (combined with other retirement assets like pensions or TFSAs) should be approximately $600,000.
Looking Ahead: This milestone accelerates quickly, with the target jumping to 7x your salary by age 55 and 8x by age 60.
Median vs. Average: Where Do Canadians Stand in 2026?
If your RRSP calc results aren't hitting the 6x mark yet, you aren't alone. Recent 2026 data shows a significant gap between "ideal" milestones and reality:
The Median Reality: For Canadians in the 45–54 age bracket, the median RRSP balance sits closer to $72,600 for individuals. However, when factoring in employer-sponsored pensions and other private assets, the total median retirement fund for economic families rises to roughly $210,000.
The "Top Decile": Those in the top 10% of savings for this age group often report total retirement assets exceeding $730,000, aligning more closely with the 6x salary guideline.
What to Do If You're Behind at 50
If your RRSP estimator shows a "savings gap," don't panic—age 50 is the perfect time for a tactical pivot. In 2026, you can leverage two powerful tools to catch up:
Maximize Your 2026 Limit: With the RRSP contribution limit rising to $33,810 for 2026, high earners have more "tax-advantaged space" than ever to move capital into their accounts.
Unused Contribution Room: Check your latest Notice of Assessment. Many 50-year-olds have tens of thousands of dollars in "carry-forward" room from their younger years. Using an RRSP loan or a bonus to fill this room now can lead to a massive tax refund and a significant boost to your compounding power.
Expert Tip: By age 50, your RRSP savings calculator should also factor in government benefits. As of late 2025, the maximum CPP retirement benefit is over $17,000 per year, which can help offset a lower personal RRSP balance.
If your RRSP estimator shows you are behind at age 50, you need to make every dollar work harder.
For Canadians looking to diversify into the US market, moomoo offers $0 currency exchange fees on CAD/USD and highly competitive commissions on US stocks and ETFs. This allows you to invest your "catch-up" contributions into US tech or growth sectors without losing a significant chunk of your principal to high foreign exchange markups at traditional banks.
Conclusion: Start Your RRSP Calculator Today
Whether you are looking to secure an immediate tax refund or are carefully calculating your path to retirement at age 50, the decisions you make before the March 2, 2026, deadline will have a lasting impact on your financial future. An RRSP is more than just a savings account—it is a strategic vehicle that, when managed correctly, can significantly accelerate your wealth through tax-deferred compounding.
However, the growth of your RRSP isn't just determined by how much you contribute, but also by how much you pay in fees. This is where moomoo Canada stands out as a game-changer for Canadian investors. By choosing moomoo for your RRSP or Spousal RRSP, you can maximize your returns through:
Industry-Leading Cost Efficiency: Say goodbye to high management fees. Moomoo offers $0 account maintenance fees and $0 annual fees for RRSP accounts, ensuring more of your money stays invested.
Superior FX Rates for US Investing: If your RRSP strategy includes US stocks or ETFs, moomoo provides highly competitive currency exchange rates, allowing you to bypass the expensive 1%–2% markups typically charged by traditional Canadian banks.
Pro-Level Analysis Tools: Stop guessing and start strategizing. Access free Level 2 market data, advanced stock screeners, and AI-powered insights to help you pick the right assets for your portfolio.
Seamless Mobile Experience: Manage your RRSP contributions and monitor your long-term growth in real-time with an award-winning, user-friendly interface designed for the modern investor.
Don't let another tax year pass by without a plan. Use an RRSP calculator to find your optimal contribution amount, and then empower your portfolio with the professional tools and low fees of moomoo Canada.
This presentation is for informational and educational use only and is not a recommendation or endorsement of any particular investment or investment strategy. Investment information provided in this content is general in nature, strictly for illustrative purposes, and may not be appropriate for all investors. Read more



