Balance Safety and Returns with Cash Equivalents amid Market Uncertainty
While the equity markets are currently strong, with the S&P 500 hitting record highs over 36 times this year and the S&P/TSX Composite Index recently reaching new peaks, the second half of the year might face two main risks: uncertainty surrounding interest rate policies and the US presidential election.
To mitigate these risks, it is always wise for you to diversify a portion of your assets into cash solutions to secure stable returns. Notably, key central bank interest rates are still relatively high, hovering around 4%.
You might consider to seize the opportunity to join the 'late' high-interest-rate party.
There are several strategies available to capture stable returns.
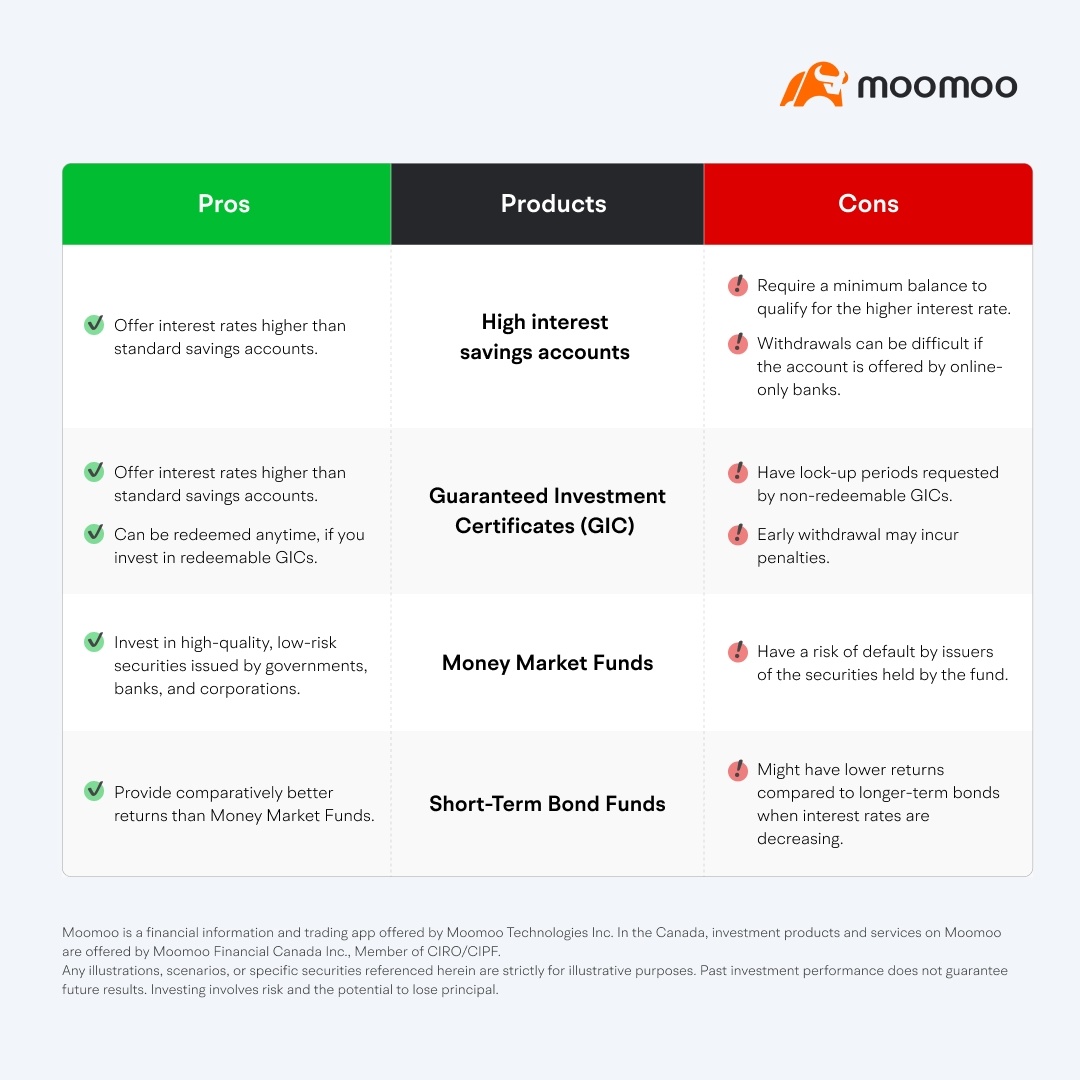
High-interest savings accounts
A high-interest savings account is a bank account that offers interest rates higher than standard savings accounts. Several major Canadian banks and online institutions offer rates of 4% to 5% or even higher. By depositing funds into these accounts, you can achieve a robust return without taking on substantial risk.
However, some banks require maintaining a minimum balance to qualify for the higher interest rate. It can also be more challenging to withdraw and spend money from these accounts offered by online-only banks since they do not provide chequing services or debit cards.
Guaranteed Investment Certificate
A GIC is a type of investment offered by banks and credit unions where you deposit a specific amount of money for a fixed period, ranging from months to several years. It is a low-risk option providing a higher yield than regular savings accounts. Currently, some Canadian banks and financial institutions are offering over 5% for GICs.
GICs come in two main types: non-redeemable and redeemable. Non-redeemable GICs generally offer higher interest rates due to their lock-up period. Early withdrawal may incur penalties. Redeemable or cashable GICs provide more flexibility to withdraw funds early, but the trade-off is a lower yield.
Money Market Funds
Money Market Funds are a type of mutual fund that invests in short-term, high-quality, low-risk securities issued by governments, banks, and corporations. You can park cash in these funds while earn a modest return. The primary goal of these funds is capital preservation and liquidity.
Even though it is considered relatively small, they are not entirely risk-free. There is still a small risk of default by issuers of the securities held by the fund.
Short-Term Bond Funds
If you have a slightly higher risk tolerance and are seeking better returns, you might consider investing in short-term bond funds. Short-term bonds are debt securities issued by governments or corporations with maturities typically ranging from one to five years.
It is important to note that short-term bonds generally carry less interest rate risk than longer-term bonds because their price is less sensitive to changes in interest rates. When interest rates are expected to decrease, buying longer-term bonds may potentially offer higher returns from capital gains due to falling rates.
Cash rebate
Nowadays, some trading platforms offer attractive cash rebate on idle cash. For example, with Moomoo Canada, if you deposit any amount into the platform, your uninvested money can earn 6% p.a. in monthly cash rebates. For amounts exceeding CA$10,000, you can get a 2% annual return.
Learn more about 6% our cash rebate here:
This presentation is for informational and educational use only and is not a recommendation or endorsement of any particular investment or investment strategy. Investment information provided in this content is general in nature, strictly for illustrative purposes, and may not be appropriate for all investors. Read more



