How to Open RRSP Account: Step-by-Step Guide for Canadians
How to Open RRSP Account: Step-by-Step
So, you’ve decided it’s time to start building your retirement savings and you’re wondering exactly how to open RRSP account. Maybe you’ve heard friends talk about it, or perhaps your accountant gave you “the look” during tax season. Either way, you’re in the right place—let’s walk through the process together, step by step.
1. Pick a financial institution
First things first: you need to choose where you want to open your RRSP. Most major banks, credit unions, trust companies, insurance firms, and online investment platforms offer RRSP accounts. Options include traditional institutions like Scotiabank and RBC, but also digital brokers like Moomoo.
Why consider Moomoo?
As an all-in-one trading and investing platform, Moomoo makes RRSP investing more seamless with:
In-App Exchange: Easy access to Canadian and U.S. markets for stocks, ETFs, funds, and more
Smart Order Types: Limit, market, stop, and other advanced orders to help you execute the way you want
Low Fees & Transparent Pricing: Keep more of your returns
Real-Time Quotes & Charts: For informed trading decisions
This means your RRSP isn’t just a savings bucket — it’s an active investment account you can use to grow your money.
2. Gather Information
Before you start filling out forms, make sure you have your essentials ready:
Social Insurance Number (SIN)
Government-issued photo ID (driver’s license or passport)
Employment details
Contact information (address, email, phone)
These details help verify your identity and ensure everything’s set up correctly from the get-go .
3. Start the Application
Let's use Moomoo as an example:
Register an account by clicking the "Open Account" button or on the App
Choose RRSP and click "Next"
Fill in the Basic Information and submit it
4. Next Steps
Once submitted, we will confirm your new RRSP account by email within hours or days. Now comes the fun part: picking investments! Whether it’s mutual funds, GICs, ETFs, or stocks—the choice is yours.
So go ahead—take that first step towards smarter retirement savings today!
5. What You Can Do Once Your RRSP Is Open
Once your RRSP is live, you can choose investments based on your goals and risk tolerance. Here are some ways Moomoo helps you grow your retirement savings:
? In-App Exchange
Trade a variety of assets (stocks, ETFs, funds) right within the app — fast and conveniently.
? Smart Screeners & Tools
Stock Screeners: Filter by industry, performance metrics, dividend yield, and more
ETF Screeners: Compare ETFs by theme, cost, yield, and asset allocation
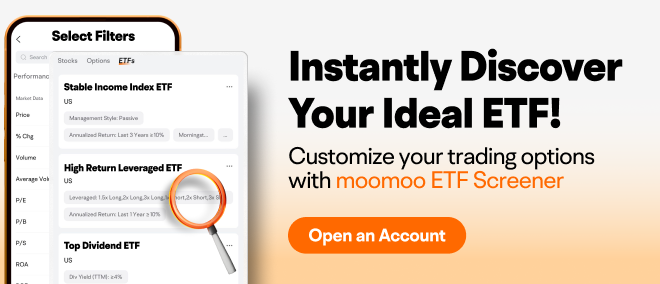
These help you find investment opportunities that fit your RRSP strategy.
>> Learn more: Best ETFs for RRSP in 2026: Maximize Your Tax-Free Growth
? Analytics & Insights
Analyst Ratings and Institutional Tracker provide context on market sentiment
Dividend Calendar & DRIP Options help you plan cash flow and reinvest dividends automatically
You may also like: Can I Use My RRSP to Buy Stocks? A Complete 2026 Guide
How Does RRSP Work?
An RRSP (Registered Retirement Savings Plan) is more than just a fancy acronym tossed around by financial planners. It’s a government-registered account built for Canadians who want their money to work overtime for retirement.
Tax-Smart Retirement Sidekick
Here’s the thing: when you contribute to an RRSP, every dollar you tuck away can be deducted from your taxable income. That means a lower tax bill now, and potentially a bigger refund come spring. And while your investments—be it stocks, mutual funds, GICs, or even plain old cash—sit inside your RRSP, they grow tax-deferred. You only pay tax when you finally withdraw the money, which (fingers crossed) will be when you’re retired and in a lower tax bracket .
Who Can Open RRSP Account
If you're a Canadian resident with earned income and a valid Social Insurance Number, you qualify to open an RRSP account. There’s no minimum age (though most start after their first job), but once you hit 71, you'll need to convert your RRSP into an income stream like a RRIF . Financial institutions across Canada make it easy to get started online or in person.
What you can hold with RRSP
Once you've opened an account, it's time to decide what goes inside. You’re not limited to cash; depending on where you open your RRSP, you can invest in stocks, ETFs, bonds, GICs, and mutual funds .
Flexibility
RRSPs aren’t just about golden years and sunsets on the dock. Need help buying your first home? The Home Buyer’s Plan lets you borrow from your RRSP without immediate tax consequences. Thinking about heading back to school or supporting your spouse’s education? The Lifelong Learning Plan is there for that too .
Catch-Up Room & Spousal Contributions
Didn’t max out last year? No worries—the unused contribution room rolls forward, letting you catch up when life (or income) allows . And if family financial planning is on your radar, contributing to a spousal RRSP can mean even more tax savings as a couple .
Choosing the Right RRSP Provider
Where Should You Park Your RRSP?
Banks, credit unions, robo-advisors, and investment firms all offer RRSP accounts—but they don’t all play by the same rules. Some Canadians swear by big banks for their brick-and-mortar comfort and easy access to advisors. Others lean into digital platforms for self-directed investing and lower fees. . If you’re itching for control, maybe you want to pick stocks or ETFs yourself, a self-directed RRSP from providers like Moomoo lets you trade thousands of investments and research to your heart’s content . It’s perfect for DIY investors who trust their own instincts.
Investment Options Comparison Table:
Investment Type | Description | Best For |
Mutual Funds | Instant diversification & professional management | Hands-off investors |
Guaranteed Investment Certificates (GICs) | Principal guaranteed; predictable returns | Conservative savers |
Savings Accelerator/High Interest Accounts | Competitive interest rates; high liquidity | Low-risk & short-term goals |
Stocks & ETFs | Potential higher returns; market volatility | DIY & growth-focused |
Bonds & Options | Add stability or portfolio flexibility | Moderate risk takers |
Segregated Funds | Like mutual funds plus guarantees against downturns | Risk-conscious investors |
RRSP Contribution Rules
Rule Type | Details | Example/Reference |
Annual Limit | Up to 18% of previous year's earned income; government-set maximum | $33,810 cap for 2026 |
Unused Room | Rolls forward indefinitely | Check Notice of Assessment |
Lump Sum/Automatic | Lump-sum deposits OR monthly transfers allowed | $500+/month may unlock rewards |
Employer Matching | Group plans may offer matching contributions | Free money! |
Spousal Contributions | Contribute on behalf of spouse/common-law partner | Tax splitting benefits |
Withdrawals | Allowed before retirement but taxed as income + withholding | Emergency use only |
Conversion Age | Must convert by age 71 | Switches to RRIF etc. |
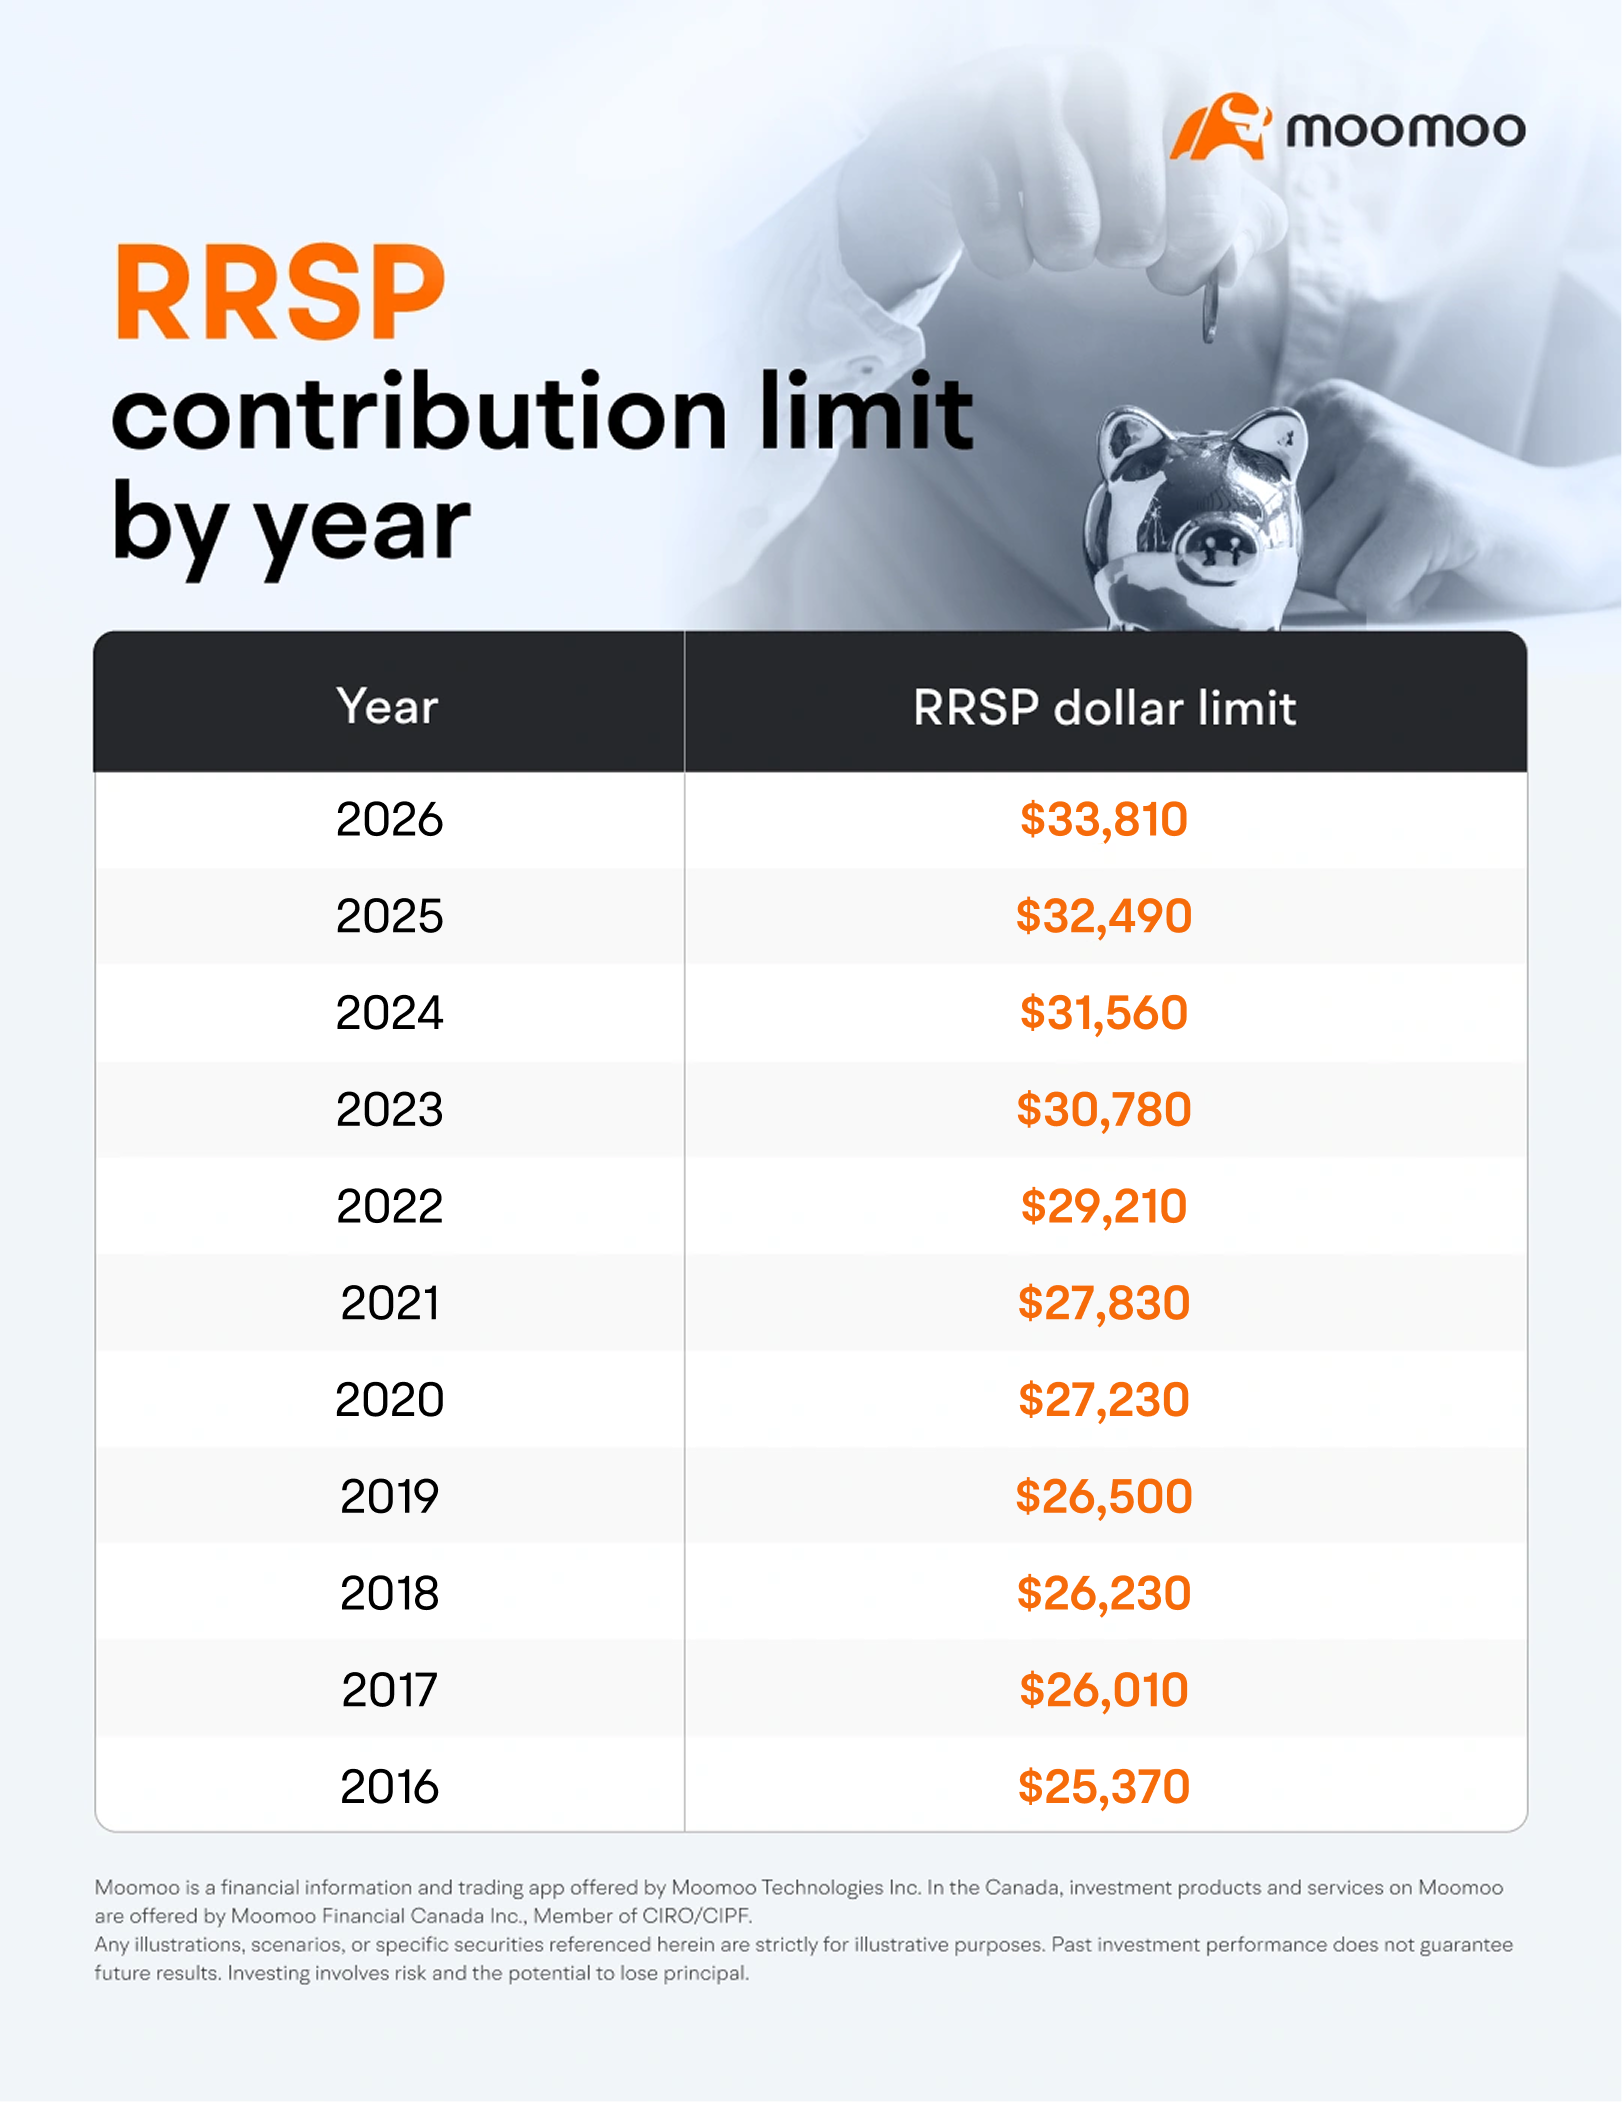
>> Learn more: RRSP Contribution Limit 2026
Conclusion
Starting early with regular contributions allows savings in an RRSP account to grow faster thanks to compounding interest and valuable tax advantages. Whether you're just beginning your career or planning for retirement soon, taking action today sets up comfort and peace of mind down the road. Remember: consistent contributions plus periodic reviews ensure you're always moving toward financial security as life changes.
This presentation is for informational and educational use only and is not a recommendation or endorsement of any particular investment or investment strategy. Investment information provided in this content is general in nature, strictly for illustrative purposes, and may not be appropriate for all investors. Read more



