CPF Investment in Singapore: How to Invest your CPF Savings with Moomoo
Key Takeaways
CPF can be invested, not just saved:CPF funds are not limited to earning guaranteed base interest. Eligible members can invest surplus OA savings under the CPF Investment Scheme (CPFIS-OA) for potential higher returns.
Core advantages of investing CPF on Moomoo:Moomoo SG, a MAS-regulated brokerage, delivers five core advantages for CPFIS-OA investors: access to approved SGX securities, powerful free research tools, Moomoo AI insights, transparent competitive fees, and unified portfolio management in one app.
Simple workflow to start CPF investing:To trade CPF-approved assets on Moomoo: open a CPFIA with DBS/OCBC/UOB, complete CPFIS prerequisites, link your CPFIA on Moomoo, filter CPF-eligible counters and place your order.
Key risks & rules to observe:Stay within CPF Board allocation caps, transfer sale proceeds back to OA manually if not reinvesting; CPF investing carries market risk, has no capital guarantee and suits investors without near-term housing needs.
Got a CPF Investment Account with DBS, OCBC or UOB? Link it to Moomoo today and put your CPF-OA savings to work on eligible SGX shares, REITs and ETFs.
Link your CPF Investment Account Now>>
Link your CPF Investment Account Now>>
CPF Investment at a Glance
CPF is Singapore’s Central Provident Fund: a mandatory savings scheme for citizens and permanent residents. You and your employer contribute a share of your wages each month. That money is meant for retirement, housing and healthcare. It stays with the CPF Board, earns CPF interest, and is not spendable cash in your bank account.
Most members leave their CPF savings in the system to earn that guaranteed interest. If you meet the eligibility rules, you can also use part of those savings for CPF Investment: buying approved products under the CPF Investment Scheme (CPFIS), without taking the money out as cash.
What can I invest my CPF savings in?
Under CPF Investment Scheme, approved assets include stocks, ETFs, unit trusts, SGS and T-bills. US stocks are generally not allowed under CPFIS.
Below is a quick comparison of common CPFIS-eligible investment instruments to help you evaluate your options:
Investment Instrument | Key Characteristics | CPF Investment Considerations |
Stocks | Equity ownership; price volatility; potential capital gains & dividends | Subject to the 35% stock allocation cap for CPFIS-OA; higher risk |
ETFs | Diversified basket of assets; lower cost than active funds | Popular for CPF investors; equity ETFs fall under the 35% equity cap |
Unit Trusts | Professionally managed portfolios; active fund fees | No 35% equity cap restriction; confirm CPF approval status before investing |
SGS / T-bills | Singapore government backed, low risk, fixed income | Lower returns, capital preservation option for CPF funds |
Where can you invest your CPF savings?
To trade CPF-approved securities, you need a platform that supports CPFIA linkage. Two main types of platforms are available:
Online brokerages: Allow you to trade stocks, ETFs and bonds directly, with self-directed investing.
Fund platforms: Usually limited to unit trusts, with no stock or ETF trading access.
If you want a single platform to trade stocks, ETFs and other CPFIS-approved instruments, you may consider supported online brokerages such as Moomoo.
You can open your CPF investment journey with platforms like Moomoo. Moomoo SG is a MAS-regulated online brokerage in Singapore, supporting CPFIS-OA investing. Once you link your bank CPFIA to Moomoo SG, you can trade SGX-listed CPF-eligible stocks and ETFs directly within the Moomoo app.
Why invest your CPFIS-OA funds with Moomoo?
Moomoo gives eligible CPFIS-OA investors a convenient way to access supported CPF-approved investments, research them with free and advanced in-app tools, get AI-powered market insights, and manage their investments through a seamless and integrated workflow, all within one app.
Choosing a platform for your CPF investment is not only about finding approved investment products. It is also about understanding the information, tools, costs and account processes available to help you manage a long-term retirement portfolio, while keeping in mind CPF’s guaranteed base interest and CPFIS rules.
If you already hold a CPF Investment Account (CPFIA) with DBS, OCBC or UOB and are looking to invest your Ordinary Account (OA) savings for the long term, moomoo offers five key advantages:
Access a suite of CPFIS-approved investment products
Make more informed investment decisions with free, powerful investing tools
Get AI-powered market insights for easier investment research
Trade with transparent, competitive fees for CPF trades
Link and manage your portfolio (including CPF investments) in one integrated workflow
Access supported CPFIS-OA investment products
With moomoo, eligible investors can use their OA savings via linked CPFIA to invest in supported SGX-listed CPF-eligible shares, REITs and List‑A ETFs.
Product | Currency |
SGX-listed CPF-approved shares & REITs | SGD |
SGX-listed List‑A CPF ETFs | SGD |
CPFIS-OA trades made through moomoo are settled via your CPF Investment Account (CPFIA) maintained with an appointed CPFIS agent banks. Funds remain inside the CPF system and are not withdrawable as cash.
The seven CPFIS-OA List-A ETFs currently supported on moomoo are:
SS SPDR STI ETF
Amova STI ETF S$D
GLD SG$
ABF SG BOND ETF
Amova SGD IGBond ETF
Amova STI ETF S$A
Amova-STC Asia REIT
Refer to CPFB official PDF for full details, risk classification and historical performance: CPFB List‑A ETF official document
For gold ETF inclusion criteria, see CPFB FAQ: CPFB Gold ETF eligibility criteria
You can review the official stock list published by SGX: SGX: Stocks under CPF Investment Scheme
For gold ETF inclusion criteria, see CPFB FAQ: CPFB Gold ETF eligibility criteria
You can review the official stock list published by SGX: SGX: Stocks under CPF Investment Scheme
Before placing an order, check that:
The counter is tagged and supported for CPFIS-OA trading in the moomoo app;
Your OA has investible funds above the mandatory S$20,000 OA minimum, with enough balance to cover the order value plus applicable fees;
You stay within CPF Board’s regulatory investment caps: maximum 35% of investible OA savings for shares, REITs and equity ETFs; maximum 10% for gold-related investments;
You have completed the mandatory CPFIS Self-Awareness Questionnaire (SAQ).
Note that US stocks, overseas-listed securities and instruments outside the official CPFIS approved list cannot be purchased with CPF funds on Moomoo. Certain CPFIS instruments such as unit trusts and investment-linked policies are not available via Moomoo’s CPF offering.
Make more informed decisions with free, powerful investing tools
Long-term retirement wealth building requires careful research, and Moomoo provides free in-app tools that can help CPF investors assess opportunities before committing their OA savings, which includes:
Real-time market data and price charts;
Company profiles, financial information and corporate actions;
Market news and stock-specific updates;
Analyst ratings, earnings information and research content;
Technical indicators and advanced charting tools;
Dividend calendars, yield tracking and historical performance data;
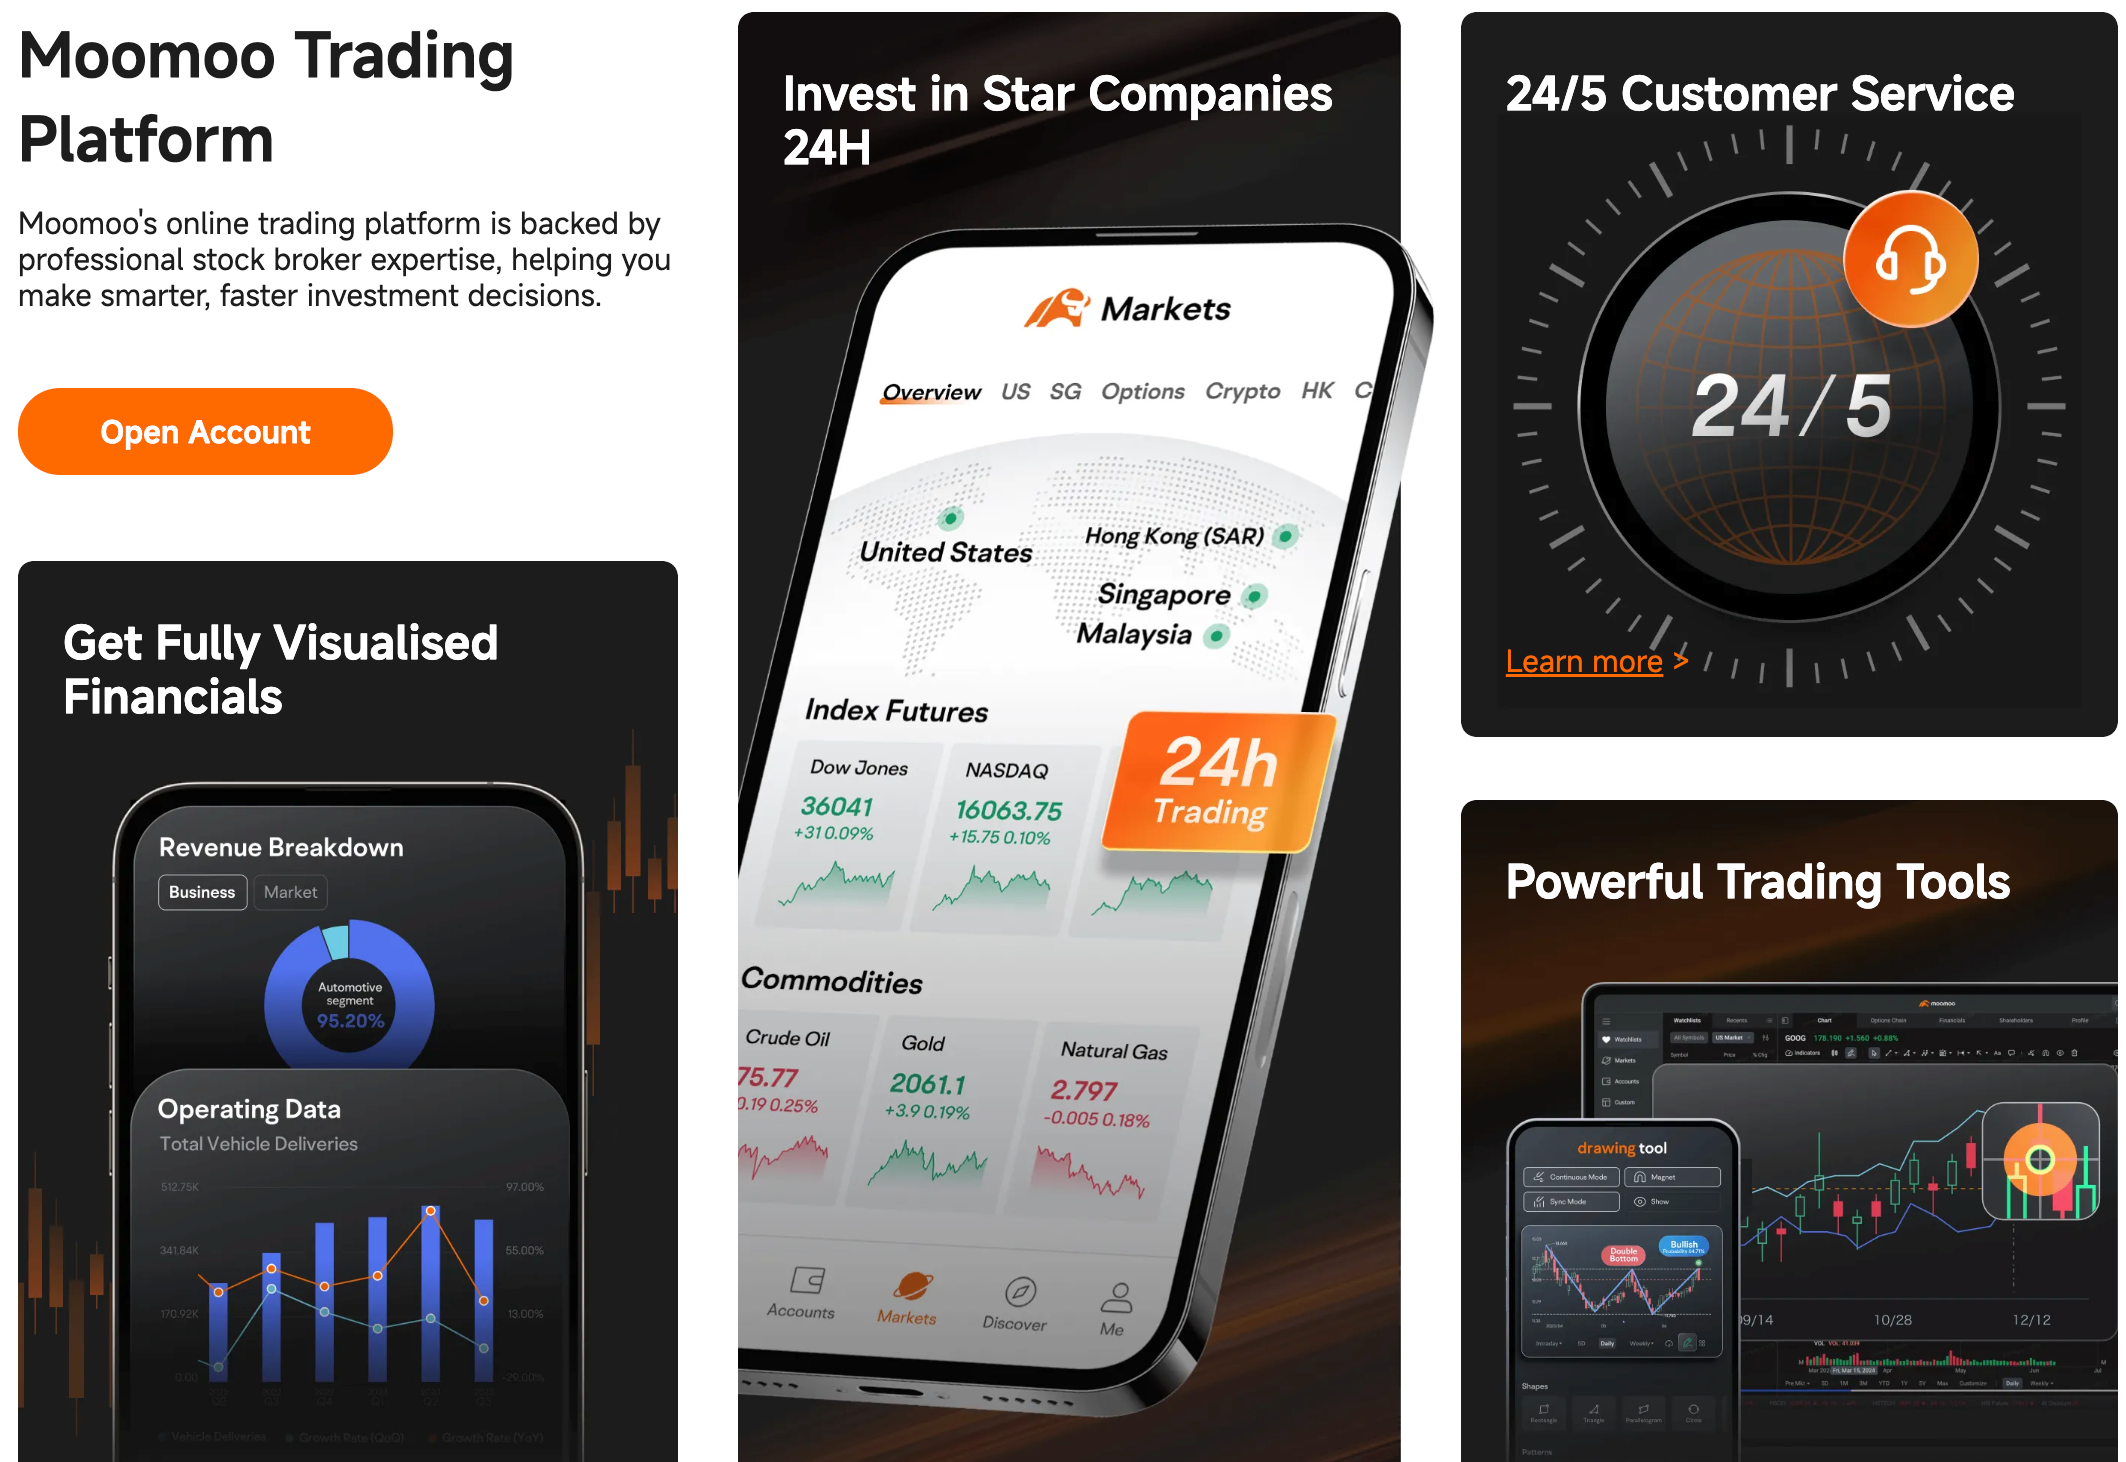
Note: 24/5 trading applicable to eligible US stocks & ETFs only.
Get AI-powered market insights for easier investment research
Investors often need help turning large amounts of market and portfolio information into clear next steps. With Moomoo AI enabled, users can ask questions inside the app and receive timely, relevant insights.
This can help investors:
Understand recent price movements of a CPF-eligible stock or ETF;
Summarise relevant company, earnings or market information;
Explore questions about a security before investing;
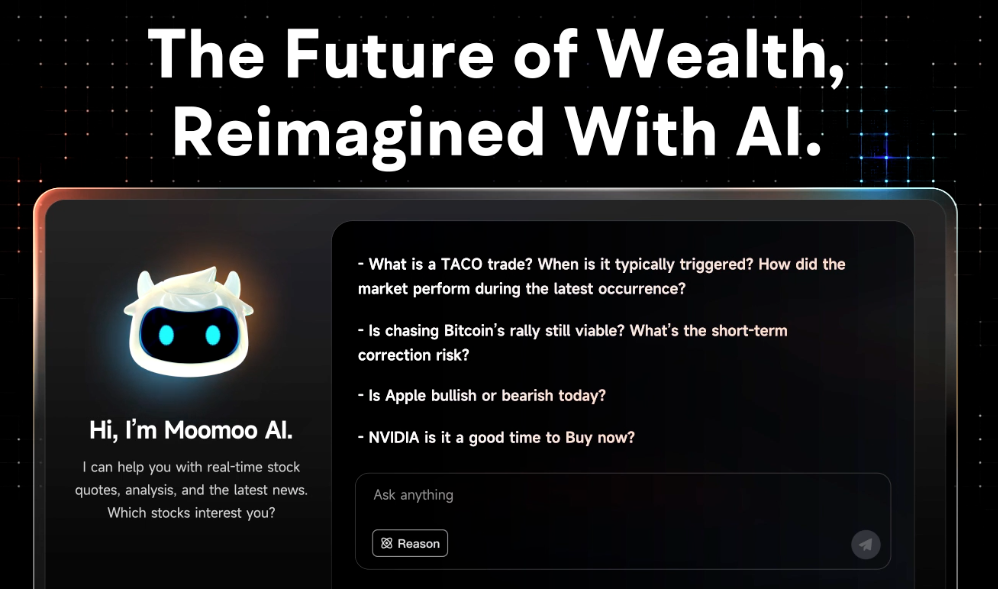
For CPF investors, this is especially useful because CPF investments should usually be considered as part of your broader long-term financial and retirement plan, not standalone speculative trades.
With this full set of powerful analytical and research tools right inside one app, you do not need to switch between multiple platforms to research and analyse for your CPFIS-OA investment. Equipped with robust market insights and practical investing features, Moomoo SG is well-positioned to support your CPF investment journey. Download moomoo and open account to explore and experience the full suite of investment tools for yourself.
MAS-Regulated & Secure Trading Environment on Moomoo
Moomoo SG is regulated by the Monetary Authority of Singapore (MAS) and holds a Capital Markets Services Licence (CMS101000). Client assets are segregated from Moomoo SG's house funds.
For CPF investing specifically, your funds never leave the CPF system: trades settle through your bank-held CPFIA with DBS, OCBC or UOB. Moomoo acts only as your order execution channel, which aligns fully with CPFIS rules and keeps your OA savings within the official CPF framework.
Link and manage your CPF investments in one workflow
Moomoo makes it easier for eligible investors to link their CPFIA and access supported CPFIS-OA investments through an integrated workflow, with fewer steps across separate platforms.
With moomoo, you can go from discovering an investment idea to placing an eligible CPF order all inside one app.
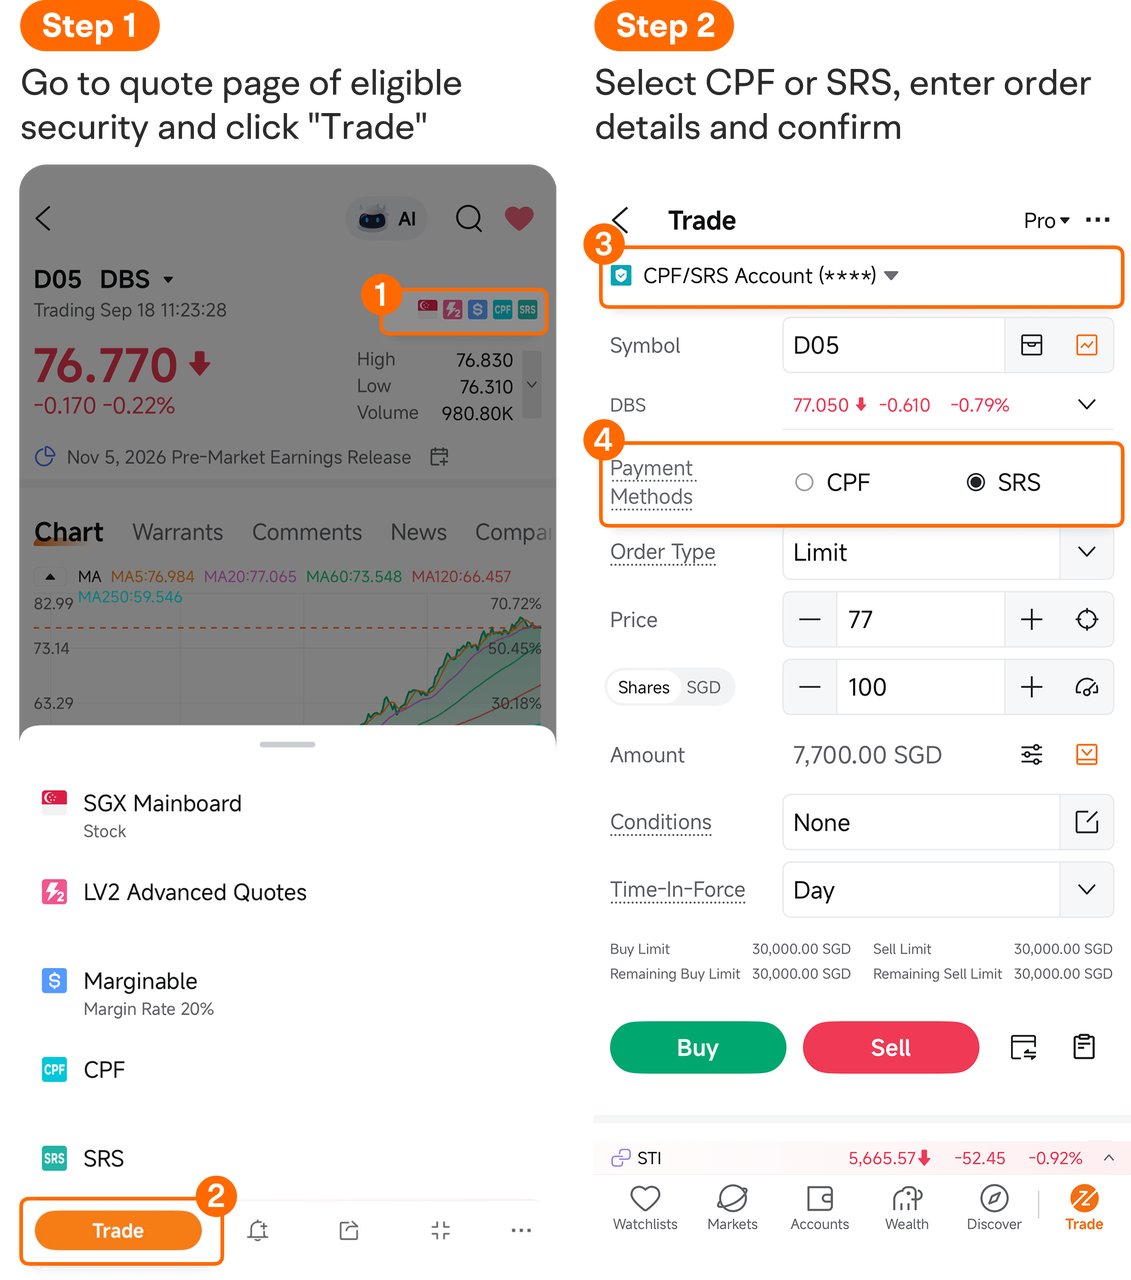
Research using moomoo’s market data, analysis tools and AI features. When you are ready to place an eligible trade, simply select your linked CPFIA as your payment method before confirming the order. This means you do not need to switch between separate platforms just to research and then place your CPF trade. You can also manage both your CPF and SRS retirement portfolios side‑by‑side within the same app.
How to Invest Your CPF Savings via Moomoo: step-by-step guide
Step 1: Open a CPF Investment Account with an approved CPFIS agent bank
To invest your CPF OA funds with moomoo, you need a CPF Investment Account (CPFIA) with one of the approved agent banks: DBS, OCBC or UOB.
You should also ensure that the CPFIA account details you enter in moomoo are accurate and belong to you.
A CPFIA account is held with the agent bank, not with Moomoo. Moomoo is the trading platform used to place supported CPFIS-OA orders.
Step 2: Confirm you have eligible investible OA savings before investing
If you decide to invest under CPFIS-OA, ensure the amount you deploy fits your housing, retirement goals and liquidity needs.
Before investing, review the mandatory OA minimum balance requirement of S$20,000, CPF Board’s regulatory investment caps and CPFIS withdrawal / transfer rules. You should also consider whether you are comfortable giving up CPF OA’s baseline guaranteed interest, and whether you intend to hold the funds as cash inside CPF system or invest them in CPF-approved products.
Step 3: Link your CPF account on Moomoo
Once your pre-requisites are ready, follow these steps to start CPFIS-OA investing on Moomoo SG:
Link your CPF Investment Account
Log in to Moomoo SG. Navigate to CPF / account linking, select your appointed agent bank (DBS, OCBC or UOB), input your CPFIA number and submit the request. Wait for linkage approval. CPF will not appear as a settlement method until approved.
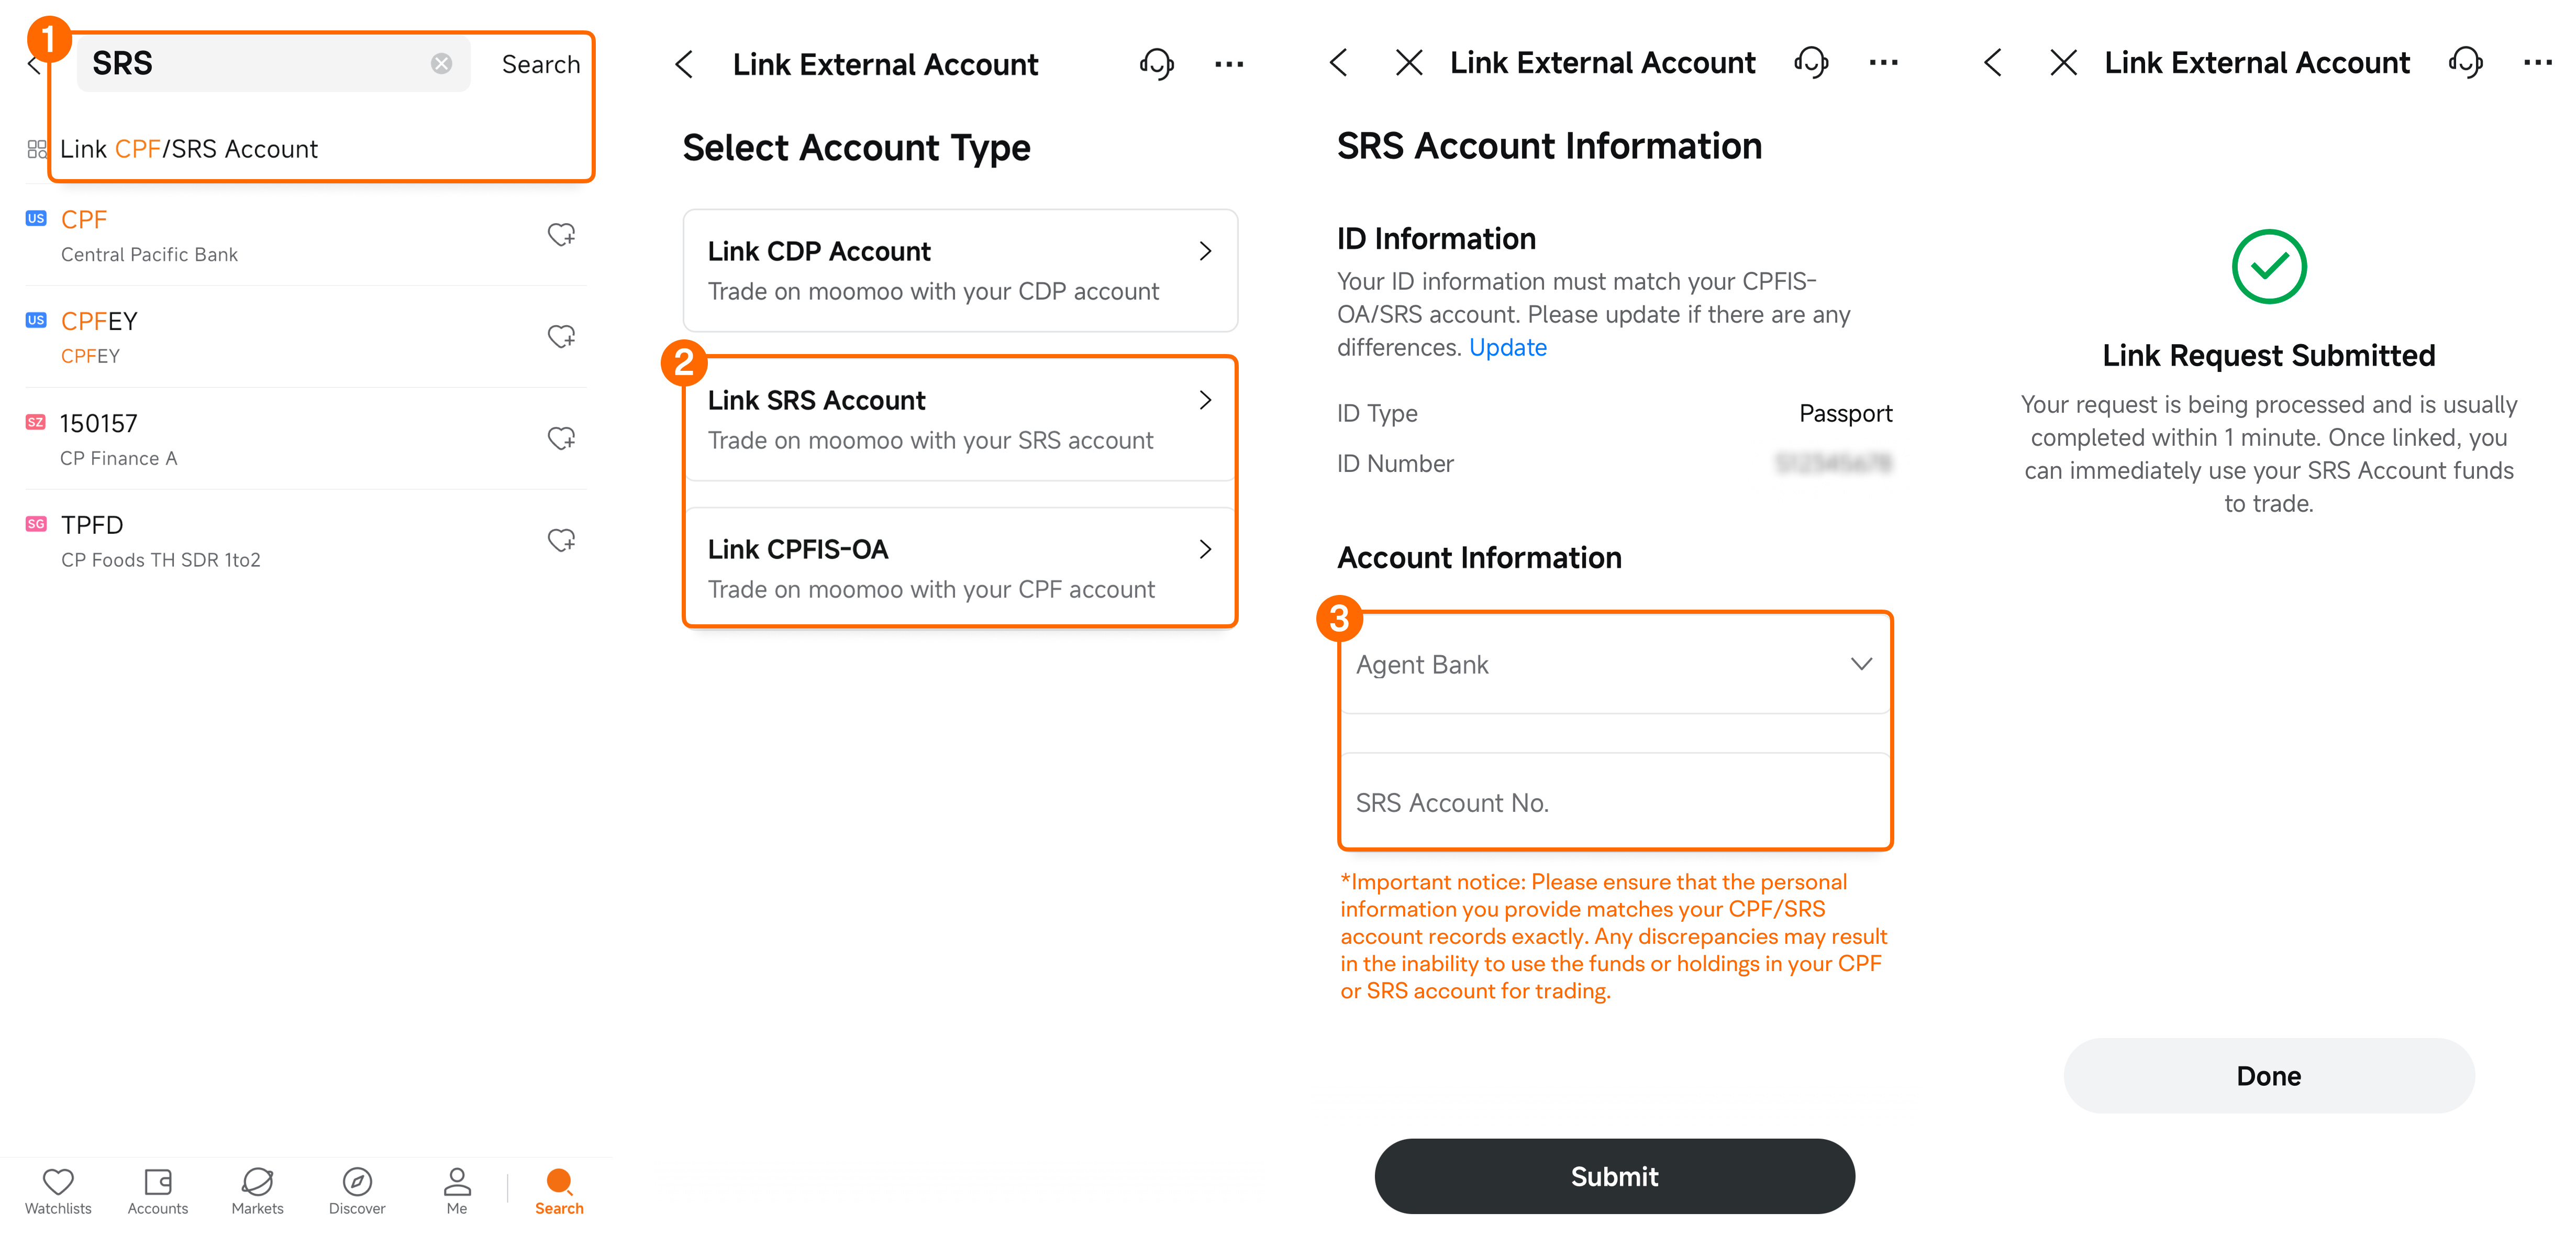
2. Filter CPF-eligible products
Switch your funding source to CPF instead of Cash. View only securities tagged CPF-eligible. Skip US stocks and any instruments without the CPF-eligible label.
3. Place the order with CPF funds
Confirm settlement method is set to CPF. Double-check order quantity, price and verify you are drawing from OA investible funds. After execution, holdings reside within your CPF investment position; they do not become cash inside your Moomoo SG account.
4. After you sell: transfer proceeds back to OA
Sale proceeds are credited to your CPF Investment Account and do not immediately flow back to your OA. If you do not plan to reinvest, you can transfer the funds back to your OA to start earning CPF interest earlier. Otherwise, unused funds will generally be automatically returned to your OA after two consecutive months of inactivity.
Once you have completed the checklist above, you can link your CPFIA on moomoo and begin investing in CPF-eligible instruments. The next section explains key reasons to consider using moomoo for your CPFIS-OA investments.
CPF investment serves as one component of holistic retirement planning. Beyond CPFIS, Moomoo offers a comprehensive range of investment and portfolio management tools to support your long-term financial goals. Discover more about wealth building on Moomoo.
Explore CPFIS-OA investment opportunities on Moomoo SG>>
Explore CPFIS-OA investment opportunities on Moomoo SG>>
Should I invest my CPF? CPF Investment risk and mistakes to avoid
CPF investing is optional and may not be suitable for everyone. The core rule to follow: only invest your CPF funds if you can tolerate market losses, are confident that your investments can outperform CPF interest rates after accounting for applicable fees and charges. Most importantly, CPF-eligible does not mean risk-free or capital-guaranteed.
Is CPF investing safe
CPFIS investments carry genuine market risk, even if they are approved under the official scheme. You can lose part or all of your invested capital, and the CPF Board does not guarantee any investment returns or endorse any brokerage platforms or products.
This risk carries real-life financial consequences tied to your core CPF benefits. Since your Ordinary Account (OA) funds are typically reserved for housing, significant investment losses may reduce the funds available for your property purchase or mortgage repayment. As you approach age 55, your OA and SA savings may be transferred to your Retirement Account to meet the Full Retirement Sum. Investment losses at this stage can be difficult to recover and may reduce your future retirement payouts.
By comparison, leaving funds inside the official CPF system delivers stable, risk-free compound returns based on current official rates. From 1 October 2026 to 31 December 2026, the OA base interest rate is 2.5% per annum, while SA, MediSave and RA earn a guaranteed 4% per annum. The government has extended the 4% interest floor for SA/MA/RA until 31 December 2027.
Members aged below 55 also enjoy an extra 1% annual interest on the first S$60,000 of combined CPF balances, with a maximum of S$20,000 eligible from the OA alone.
Once you allocate OA or SA funds to CPFIS investments, the invested amount stops earning guaranteed CPF interest and becomes fully exposed to market volatility. This creates a clear opportunity cost:
OA investible funds (above S$20,000): You forfeit a stable 2.5% annual return
SA funds: You forfeit a high guaranteed 4% annual return, creating a much higher performance hurdle for any investment
In short, CPF investing only makes sense if your net returns (after all commissions, platform fees, and fund expense ratios) can beat these baseline guaranteed rates.
When should I consider investing my CPF?
CPF-OA investing is only recommended if you meet all the following conditions, based on the eligibility and rules covered earlier in this guide:
Your OA balance exceeds S$20,000 and you have completed all CPFIS pre-requisites including the SAQ and CPFIA setup
You have no near-term housing plans and will not need OA funds for property downpayment or mortgage installments
You adopt a long-term horizon of multiple years and can withstand short-term market volatility without forced selling
You hold a low-cost, proven strategy that can consistently outperform 2.5% annually after fees
You actively monitor your portfolio and strictly comply with CPF’s 35% cap in shares, property funds and corporate bonds, and 10% gold investment cap
Conversely, you should keep your CPF funds uninvested (or only allocate a minimal amount) if:
You plan to use OA funds for housing within the next few years
You are approaching age 55 and need maximum liquidity for Retirement Account fund transfers
You are considering SA investing, with no clear strategy to beat the 4% guaranteed post-fee return
You lack a structured low-cost plan and rely solely on market optimism
For most CPF investors, only OA funds are worth considering for CPFIS; SA funds are almost always better left untouched for guaranteed retirement growth.
CPF Investing mistakes to avoid
Most CPF investment losses stem from avoidable behavioral and technical errors. Below are the most critical mistakes to steer clear of when investing via platforms such as Moomoo SG:
Trading ineligible instruments: Never use CPF funds for US stocks, overseas shares, or unapproved counters. Always confirm the CPF-eligible tag on moomoo before placing orders.
Ignoring fee drag: Brokerage commissions, platform fees, and fund TERs directly erode your returns. High-cost products can underperform fixed CPF interest even in flat market conditions.
Leaving proceeds idle in CPFIA: After selling CPF investments, funds remain in your CPFIA and stop accruing OA interest until manually transferred back. Do not wait for automatic bank transfers; move funds back to OA immediately if you do not plan to reinvest.
Investing SA blindly: With a 4% guaranteed floor rate, SA funds have a higher performance bar. Few retail strategies can consistently outperform SA’s risk-free returns after fees.
Buying illiquid assets near age 55: Avoid locking OA funds into illiquid products as you approach 55, as upcoming RA fund transfers may require accessible cash.
Treating CPF as disposable cash: CPF funds are designated for housing and retirement. Avoid over-concentrated stock bets or frequent speculative trading.
If you invest CPF on Moomoo SG, sticking to two core habits will eliminate 90% of common mistakes: only trade tagged CPF-eligible instruments, and always transfer sale proceeds back to your OA account promptly.
Disclaimer: CPF interest rates are reviewed quarterly by CPFB. Always verify the latest rates and approved product lists on official CPF and SGX websites before investing. This content is for educational purposes only and does not constitute personalized financial advice.
CPF vs. SRS Investing: What is the Difference?
CPF and SRS can both play a role in retirement planning, but they have different objectives, contribution rules, investment pathways and withdrawal conditions.
How are CPF and SRS different, and can investors use both?
CPF is Singapore’s compulsory social security savings scheme for eligible working Singaporeans and Permanent Residents. SRS is a voluntary scheme that may offer tax relief on eligible contributions.
Some broad differences include:
Consideration | CPF | SRS |
Nature of scheme | Compulsory savings framework for eligible employees and employers | Voluntary retirement savings scheme |
Contributions | Based on prevailing CPF contribution rules | Voluntary, subject to annual limits |
Tax treatment | Subject to prevailing CPF rules | Eligible contributions may qualify for tax relief |
Investment pathway | Subject to CPF Investment Scheme rules | Subject to SRS investment rules |
Withdrawal rules | Subject to CPF withdrawal policies | Subject to SRS withdrawal rules and tax treatment |
Some investors may use both CPF and SRS as part of their retirement planning. The appropriate approach depends on personal financial circumstances, investment knowledge, risk tolerance and retirement goals.
CPF Investment FAQs
What is a CPF account
A CPF account is where your monthly CPF contributions are deposited. It is not a single pool of money. CPF splits your savings into four separate accounts, each serving a unique purpose. Only selected accounts qualify for CPF investment.
CPF Account | Purpose in Singapore | Eligible for CPF Investment? |
Ordinary Account (OA) | Housing, insurance, education, and investment | Yes. This is the primary account used for CPF investing. You must retain a minimum of S$20,000 in your OA. |
Special Account (SA) | Retirement savings | Yes, but with a narrower list of approved products. You need to keep S$40,000 in SA. SA already earns a higher CPF interest rate, so investing SA funds is often less suitable. |
MediSave Account (MA) | Healthcare and medical expenses | No. MA funds cannot be used under CPFIS. |
Retirement Account (RA) | Created from age 55 to hold your retirement sum | Not used to initiate new CPF trades. From age 55, OA and/or SA funds may be transferred into RA, which can impact your existing CPFIS investments. |
In short: CPF in Singapore is first and foremost a social security savings system. Investment is entirely optional. In most cases, investors use OA, while SA is used occasionally, and MediSave funds cannot be invested.
What is the difference between CPF, CPFIS and CPFIS-OA?
CPF, CPFIS and CPFIS-OA are nested within one another. CPF is Singapore’s Central Provident Fund, a national savings scheme for retirement, housing and healthcare. CPFIS, or the CPF Investment Scheme, allows you to invest part of your CPF savings in approved products. CPFIS-OA is a CPFIS sub-scheme that lets you invest savings from your Ordinary Account.
In short, CPF encompasses CPFIS, and CPFIS encompasses CPFIS-OA. There is also CPFIS-SA, which allows you to invest savings from your Special Account and does not require a CPF Investment Account.
What is CPF Investment Account
A CPF Investment Account (CPFIA) is the dedicated settlement account you open with one of the three appointed agent banks: DBS, OCBC or UOB. It is required to invest OA savings via CPFIS. The CPFIA is separate from your OA account. You can think of it as an intermediate settlement account between your OA and your trades.
Key rules for CPFIS-OA:
The CPFIA is for Ordinary Account savings only; MediSave and Retirement Account funds cannot be used.
Only OA savings above S$20,000 can be invested. The first S$20,000 must remain untouched inside your OA.
Within your investible OA amount, up to 35% may be allocated to Shares (such as stocks, Equity ETFs, REITs), corporate bonds and property funds. Gold investments are capped at 10%. Many other approved products such as unit trusts are not subject to the 35% cap.
Funds within the CPF system remain as CPF savings. If your investments perform well, returns may exceed the standard OA interest rate. If investments decline, you may lose part of your invested capital. The CPF Board does not guarantee any investment returns.
Once your CPFIA with the agent bank is opened, you may link it on supported brokerage platforms such as Moomoo to purchase CPF-eligible products. This is the typical workflow for investing via your CPFIA: link your bank-held CPFIA to a qualified brokerage, select CPF-approved instruments, and settle trades using your OA funds. Your holdings stay within the CPF system. When you sell your investments, you may transfer sale proceeds back to OA if you do not wish to reinvest.
Am I eligible to invest my CPF savings?
You qualify for CPFIS if you meet all criteria:
Aged 18 years old or above
Not bankrupt
Your OA balance is over S$20,000 and/or your SA balance exceeds S$40,000
Completed the mandatory Self-Awareness Questionnaire (SAQ)
How the CPF Investment process work
Before you start trading with your CPF funds, follow this step-by-step workflow:
Check your available CPF investment amount
Complete the Self-Awareness Questionnaire (SAQ)
Open your CPF Investment Account (CPFIA) for OA savings via DBS, OCBC or UOB
Link your CPFIA to a supported brokerage platform such as Moomoo
Place orders for CPF-approved instruments
After selling, funds go back into your CPFIA. You may transfer the proceeds back to your OA account if you wish.
How much CPF savings can I invest?
For OA: only funds above S$20,000 are investible. Up to 35% of investible OA savings can be allocated to shares, with a 10% cap on gold exposure.
For SA: you must retain at least S$40,000 before investing the remaining balance.
You can check your available investible amount via CPF website or CPF app.
I am a foreigner in Singapore. Can I use CPF or SRS?
CPF is for Singapore citizens and PRs. Foreigners generally do not have CPF. SRS is voluntary, and foreigners can open an SRS account with DBS, OCBC or UOB. Because foreigners do not receive CPF tax relief, the SRS contribution cap is higher: S$35,700 a year, versus S$15,300 for citizens and PRs. Contributions must be made by 31 December to count for that year’s relief, subject to the overall personal relief cap.
How much CPF savings can I invest?
For OA, only the amount above S$20,000 is investible. Up to 35% of investible savings may go into stocks, and up to 10% into gold. Although certain unit trusts under the broader CPFIS framework may not be subject to the 35% share limit, you cannot invest in unit trusts through moomoo. For your Special Account (SA), you must retain at least S$40,000 before investing any remaining balance. You can check your current investible amount on the CPF website or app.
Is CPF investment safe?
No. CPF-eligible does not mean capital-guaranteed. You can lose part or all of the amount invested. The CPF Board does not endorse products or guarantee returns. Leaving the money in CPF is the lower-risk option: OA currently earns 2.5% a year, and SA earns 4% a year.
Why can CPF interest be as high as 4% to 6%?
CPF interest can be as high as 4% to 6% because CPF provides government-backed base interest plus extra interest on eligible balances. The OA earns 2.5% a year, while the SA, MediSave Account and Retirement Account earn at least 4%. Members below 55 receive an extra 1% on the first S$60,000 of combined balances; from age 55, they receive an extra 2% on the first S$30,000 and an extra 1% on the next S$30,000—so eligible savings can earn up to 5% or 6%, respectively. OA balances eligible for extra interest are capped at S$20,000.
CPF Board invests CPF monies in Singapore Government-guaranteed Special Singapore Government Securities. Members receive the announced CPF interest rates, not returns based directly on GIC’s annual performance. CPF savings are subject to rules on use and withdrawal, and are intended mainly for housing, healthcare and retirement.
Is CPF investing worth it?
Only if you can accept losses and still aim to beat CPF interest after fees. For OA, the hurdle is about 2.5%. For SA, it is about 4%, so SA is usually better left uninvested. It is more suitable if you have a long horizon and will not need those OA funds for housing soon.
What CPF investment products are available on Moomoo?
Moomoo CPF investing in this guide is CPFIS-OA. You can buy CPF-eligible Singapore-listed stocks and ETFs. You cannot use CPF on moomoo to buy US stocks, MediSave-funded products, or anything that is not tagged CPF-eligible. Always check the tag before you order.
How do I start a Moomoo CPF investment account?
Complete the SAQ, open a CPF Investment Account with DBS, OCBC or UOB, then open Moomoo SG and link that CPFIA. After the link is approved, switch settlement to CPF, choose a CPF-eligible product, and place the order. Moomoo does not open the bank CPFIA for you.
If I invest CPF or SRS on Moomoo, does the money move to the broker?
No. CPF and SRS funds are not transferred into moomoo as cash. OA trades settle through your bank CPF Investment Account (DBS, OCBC or UOB). SRS trades settle through your bank SRS account. Moomoo is the order channel. You cannot deposit or withdraw this money like a cash brokerage wallet, and these holdings are not treated as ordinary moomoo cash assets. After you sell, CPF proceeds to return to the CPFIA, then to OA if you transfer them back.
What happens to CPF investments when I turn 55?
At 55, CPF creates a Retirement Account and transfers SA and/or OA savings into it, up to your Full Retirement Sum. Existing CPFIS holdings are not automatically sold. After the FRS is set aside, you may apply to withdraw CPFIS investments; The holdings can be transferred to you rather than liquidated. Near 55, avoid locking OA into products you cannot sell or transfer in time, and check processing cut-offs before your birthday.
CPF interest rates are reviewed quarterly. Check the CPF Board for the latest figures. This is general information, not personal advice.
Disclaimer: This article is for educational and informational purposes only and does not constitute financial or investment advice. Investments in capital market products involve risk. Please consider your financial circumstances and investment objectives before investing. Full disclaimers at www.moomoo.com/sg/support/topic5_510. This advertisement has not been reviewed by the Monetary Authority of Singapore.
This presentation is for informational and educational use only and is not a recommendation or endorsement of any particular investment or investment strategy. Investment information provided in this content is general in nature, strictly for illustrative purposes, and may not be appropriate for all investors. Read more