Private Banking in Singapore: A Complete Guide
Key Takeaway
- Private Banking offers a personalized and comprehensive approach to wealth management for high-net-worth individuals (HNWIs).
- Traditional Private Banking vs. Modern Wealth Platforms: Modern wealth platforms differ from traditional private banks in lower entry barriers, transparent and competitive fees, client-centric services, and full digital experiences, suiting today's HNWIs better in evolving wealth management.
- Moomoo Private Wealth: Access private banking-level services with just S$1M. Enjoy transparent, competitive fees, a client-focused approach, and a fully digital platform offering real-time insights, seamless trading, and personalised investment support.
>> Explore Moomoo Private Wealth to grow your wealth safely and intelligently in Singapore.
- Private Banking offers a personalized and comprehensive approach to wealth management for high-net-worth individuals (HNWIs).
- Traditional Private Banking vs. Modern Wealth Platforms: Modern wealth platforms differ from traditional private banks in lower entry barriers, transparent and competitive fees, client-centric services, and full digital experiences, suiting today's HNWIs better in evolving wealth management.
- Moomoo Private Wealth: Access private banking-level services with just S$1M. Enjoy transparent, competitive fees, a client-focused approach, and a fully digital platform offering real-time insights, seamless trading, and personalised investment support.
>> Explore Moomoo Private Wealth to grow your wealth safely and intelligently in Singapore.

What is Private Banking?
Private Banking refers to a specialized range of financial services tailored to high-net-worth individuals (HNWIs) and ultra-high-net-worth individuals (UHNWIs). It goes far beyond the standard banking services, offering a personalized and comprehensive approach to wealth management. At its core, private banking provides clients with a high level of exclusivity, ensuring that their financial affairs are handled with the utmost confidentiality and discretion.
How Private Banking Works?
Private banking offers typical financial services such as checking and savings accounts, but in a more personalized way. Each customer gets assigned a “relationship manager” or “private banker” who takes care of all their financial matters. This private banker deals with everything, from complex tasks like setting up a jumbo mortgage to simple ones like paying bills.
Personalized core services: Unlike standard banking, it offers basic tools like checking and savings accounts with tailored support. Each client is assigned a private banker who handles tasks of all complexities—from arranging jumbo mortgages to managing daily bill payments.
Exclusive extended offerings: Beyond stocks and bonds, it provides high-end products (structured products, hedge funds, private equity access, IPO subscriptions) and customized services (portfolio management, estate planning, investment financing).
How it works: The private banker acts as a central advisor, ensuring confidentiality while aligning advice with the client's unique goals (e.g., retirement planning, wealth transfer) by understanding their risk tolerance and long-term plans.
Limitations of Private Banking for HNWIs in Singapore
As one of Asia's premier wealth management hubs, Singapore has attracted a growing number of affluent clients seeking sophisticated investment strategies and personalized service. However, private banking comes with several inherent limitations that HNWIs must carefully consider before committing to a long-term relationship with a private bank.
Limited Product Offerings
Private banks typically offer a curated range of financial products aligned with their internal investment strategy, market positioning, and approved third-party providers. While this ensures quality control and alignment with the bank's outlook, it may also result in a narrower product shelf compared to what independent wealth managers or digital platforms can offer.
Moomoo Private Wealth offers a variety of investment portfolios that include both traditional and alternative types of assets, including global stocks, private markets, cash management, fixed income, structured products, cryptocurrencies and more.
Advisory Conflicts and Sales-Driven Bias
One of the key concerns in private banking is the potential misalignment between the client's interests and the incentives of relationship managers (RMs) or advisory teams. Since many private banks operate on a sales-driven model, RMs are often evaluated based on the volume of assets under management (AUM) and product sales rather than the quality of advice or long-term client outcomes.
High Minimum Threshold
Access to private banking services in Singapore typically requires a certain investable asset threshold, which can range from SGD 1.5 million to several tens of millions of dollars, depending on the institution. This exclusivity ensures that banks can dedicate sufficient resources to serve each client effectively. However, it also excludes a significant portion of affluent individuals who are near the threshold but may still have complex financial needs.
Are You Eligible to be a Moomoo Private Wealth Client?
Moomoo Private Wealth is only for high-net-worth individuals (HNWIs) and accredited investors (AIs). The qualification requires depositing SGD 1 million and keeping an average daily balance of that amount in your account for 30 days.
Moomoo Private Wealth is only for high-net-worth individuals (HNWIs) and accredited investors (AIs). The qualification requires depositing SGD 1 million and keeping an average daily balance of that amount in your account for 30 days.
Traditional Private Banking vs. Modern Wealth Management
The landscape of wealth services has undergone a profound transformation over the past few decades, giving rise to a striking contrast between traditional private banking and modern wealth management. As we delve into aspects like entry barriers, fee structures, client focus, and operational models, the table reveals how modern wealth management is redefining the game compared to the more established traditional private banking.
Modern Wealth Management | Traditional Private Banking |
Lower Entry Barrier Accessible with a relatively lower asset threshold | High Entry Barrier Traditional private banking typically requires a higher asset threshold For example, *DBS Private Bank-*$5M, JP Morgan-$*5M |
Transparent and Competitive Fees Leverage fintech to offer clear, cost-efficient pricing, with fees aligned to service value. | Customized and Relatively Complex fees Can be complex; fees may be negotiable at higher tiers |
Fully Digital Experience Offer seamless, tech-enabled platforms for real-time trading, analytics, and smart wealth management. | Relationship-Driven Experience Blending growing digital adoption with continued reliance on the Relationship Manager's support |
Entry Barriers: Inclusivity vs. Exclusivity
Modern Wealth Management breaks down barriers to entry, welcoming clients with lower asset thresholds. This democratizes access to professional wealth-building tools, letting a broader range of individuals take charge of their finances. In contrast, Traditional Private Banking maintains higher entry barriers.
Fees: Transparency vs. Opacity
When it comes to fees, Modern Wealth Management leverages fintech to deliver transparent, competitive pricing. Fees are clear and tied to the value of services, so clients always know what they're paying for. Traditional Private Banking, however, faces challenges here. Heavy reliance on human resources drives up labor and operational costs, which may result in high, opaque fees.
Client Engagement: Long-Term Growth vs. Short-Term Revenue
Client-centricity defines Modern Wealth Management. It prioritizes clients' long-term wealth growth, offering tailored advice instead of pushing products. The focus is on building lasting financial health.
Operations: Digital Agility vs. Manual Tradition
Modern Wealth Management thrives on a fully digital experience. Tech-enabled platforms support real-time trading, data analytics, and smart wealth strategies, keeping pace with today's fast-moving financial world. Traditional Private Banking continues to emphasize personalized, relationship-based service, typically relying on direct interactions through phone or in-person meetings. While some banks are still evolving their digital capabilities, this high-touch approach remains valued by many clients who prefer tailored advice and deep advisory relationships.
Case Examples: DBS Treasures, UOB Privilege Reserve, Bank of Singapore
Singapore's financial landscape boasts a wealth of institutions offering private banking services, each distinguished by unique strengths and service models. In this section, we look closely at the private banking services from three well-known players in Singapore's market: DBS, UOB, and Bank of Singapore.
Here's a breakdown:
Features | DBS Treasures | UOB Privilege Reserve | Bank of Singapore |
AUM Entry Requirement | Minimum deposit or investment of S$1.5 million Source: DBS Treasures | S$2,000,000 minimum Source: UOB Privileges Reserve | $5 million minimum Source: Wealth briefing asia |
Lifestyle & Concierge Benefits | Lounge access, limousine transfers, exclusive events, 24/7 global services Source: DBS Treasures- Privileges | Tailored arrangements (dinner/travel/shopping/healthcare) | Exclusive events (CIO outlook), limited public perks, bespoke services Source: Bank of Singapore- Events |
Advisory & Investment | Insights from CIO, product-focused (product specialists, portfolio managers) Source: DBS Treasures- about | Wealth insights, risk-first approach, advisory tools, and financial literacy Source: UOB Privileges Official Website | Portfolio management, personalised investment advice, wealth planning Source: Bank of Singapore-Solutions |
DBS Treasures
In Singapore, there are several well-established private banking providers. DBS Treasures is a prominent offering from DBS Bank. It provides a comprehensive suite of private banking services. To gain access, a minimum deposit or investment of S$1.5 million is required as the AUM entry threshold. It enriches clients' lives with lifestyle and concierge benefits like lounge access, limousine transfers, exclusive events, and 24/7 global services.
UOB Privileges Reserve
UOB Privilege Reserve is a private banking service by United Overseas Bank, targeting high-net-worth clients. It sets a S$2,000,000 minimum entry threshold (applicable to deposits/investments) and offers tailored lifestyle concierge benefits (covering dinner, travel, shopping, healthcare arrangements) along with wealth management solutions like risk-first advisory, wealth insights, advisory tools, and financial literacy initiatives, addressing both wealth-building and lifestyle needs of its clientele.
Bank of Singapore
The Bank of Singapore is also a well-recognized name in the private banking sector. Bank of Singapore has a minimum AUM requirement of $5 million. In advisory and investment, services include portfolio management, personalised investment advice, wealth planning, etc.
How to Choose the Right Wealth Management Platform?
Selecting the right wealth management platform is a foundational step in securing long-term financial success. With a multitude of institutions offering tailored services, it's essential to approach this decision with a structured and informed mindset. This section explores two critical aspects to guide your selection: understanding your financial goals and risk tolerance, and evaluating key platform attributes such as reputation, service breadth, and technological capabilities.
Assessing Your Financial Goals and Risk Appetite
Before engaging with any wealth management platform, it's crucial to clearly define your financial objectives and personal risk tolerance. These factors form the cornerstone of your investment strategy and will significantly influence the suitability of the services offered.
Define Short-Term and Long-Term Goals Begin by identifying both immediate and future financial goals—such as retirement planning, education funding, or property acquisition. Each goal will have different time horizons and liquidity requirements, which will guide the type of investment products you should consider.
Evaluate Your Risk Tolerance Risk appetite is not just about how much volatility you can endure, but also about your financial capacity to absorb potential losses. Platforms in Singapore offer a wide array of investment products—from conservative fixed income instruments to high-growth equity portfolios. Understanding where you stand on this spectrum ensures the platform aligns with your comfort level.
Consider Income Stability A young professional with a stable income may afford a more aggressive growth strategy, while a retiree may prioritize capital preservation. Wealth management platforms often customize portfolios based on life stage, so being open and transparent about your personal financial situation helps ensure your investments align with your goal and needs.
Engage in Scenario Planning A reputable platform should assist in running “what-if” scenarios to stress-test your investment plan against market downturns, inflation, or unexpected life events. This helps in building a resilient portfolio.
Align with Personal Values (ESG Considerations)Increasingly, investors seek platforms that support environmental, social, and governance (ESG) principles. If this aligns with your values, look for platforms offering sustainable investment options or impact funds.
Key Selection Criteria: Reputation, Services & Technology
Beyond personal financial alignment, a platform's institutional qualities play a decisive role in ensuring a secure and satisfying wealth management experience.
Reputation and Regulatory StandingSingapore is home to a robust financial regulatory environment overseen by the Monetary Authority of Singapore (MAS). Ensure the platform is MAS-regulated and has a solid track record. Look for client testimonials, awards, and third-party ratings to gauge trustworthiness.
Range and Quality of Services OfferedA top-tier platform should provide a comprehensive suite of services, including portfolio management, tax advisory, and cross-border wealth solutions. Some may also offer exclusive access to hedge funds, private equity, or structured products—ideal for sophisticated investors.
Technology and Digital CapabilitiesIn a tech-savvy hub like Singapore, digital experience is a key differentiator. Evaluate the platform's online tools, mobile apps, and data visualization dashboards. Seamless integration with banking services, real-time portfolio updates, and AI-driven investment insights are becoming industry standards.
Client Service ModelUnderstand whether the platform operates on a relationship-based model with personal bankers or a more automated digital advisory. High-net-worth individuals often benefit from hybrid models that combine human expertise with digital efficiency.
Fee Structures and TransparencyCompare management fees, performance-based charges, and hidden costs across platforms. While higher fees may correlate with more personalized service, ensure you're receiving commensurate value. Transparent fee disclosure is a hallmark of reputable institutions.
Moomoo Private Wealth: Enjoy Tailored Wealth Management
In Singapore's competitive private banking sector, Moomoo Private Wealth stands out as a modern wealth platform by integrating cutting-edge technology with personalized service, designed to meet the evolving needs of high-net-worth (HNW) clients.
By focusing on flexibility, exclusivity, and holistic wealth management, the platform caters to modern investors seeking more than traditional banking solutions. Below is an in-depth look at its key offerings:
Priority Access to Exclusive Investment Products
Moomoo Private Wealth helps you build a truly diversified portfolio covering both traditional and alternative asset classes, including fixed income, cryptocurrencies, etc. From public equities and private deals to digital assets and tailored fixed-income products, you'll gain exclusive opportunities.

Personalized Service
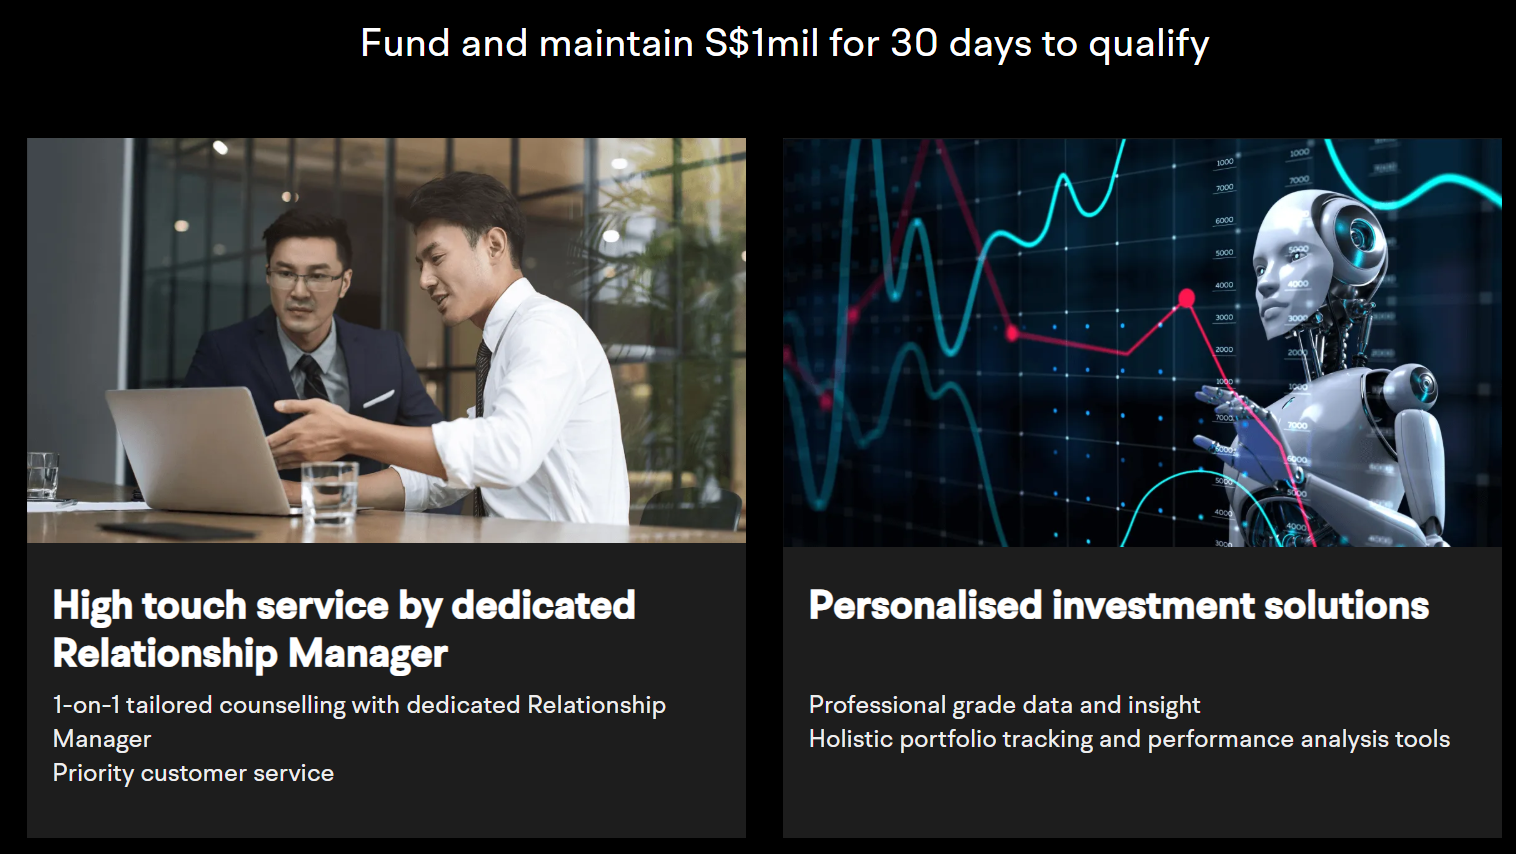
Moomoo Private Wealth centers on a client-focused approach, delivered via dedicated relationship managers and wealth advisors with specialized financial expertise. Each client receives a customized wealth advisory, combining fixed income, private investments, hedge funds, structured products, etc.

Moomoo believes effective private wealth management is not about offering one-size-fits-all products, but about understanding your goals and rhythm. With Moomoo Private Wealth, your Relationship Manager will conduct a personalized one-on-one counselling of your investment portfolio needs. You'll have easy access to portfolio tracking and performance analytics, along with forward-looking insights and product support from our research team.
One Solution for Wealth Management
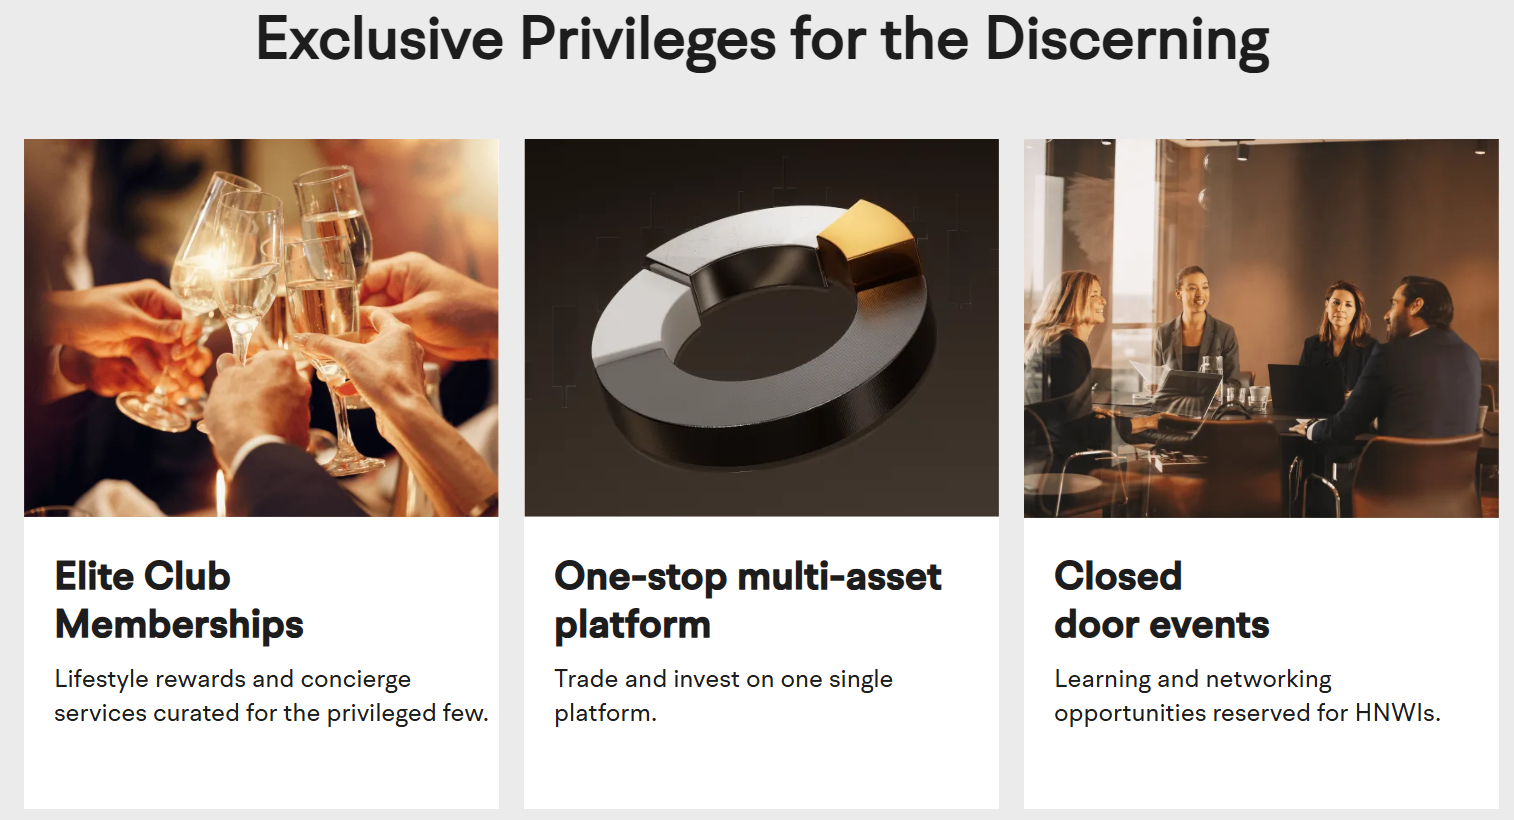
Moomoo Private Wealth streamlines financial management through an all-in-one digital platform, integrating investing, wealth tracking features, and more. Clients can manage equities, bonds, and cryptocurrencies, and monitor portfolio performance—all from a single interface.
Premium Lifestyle & Networking Access
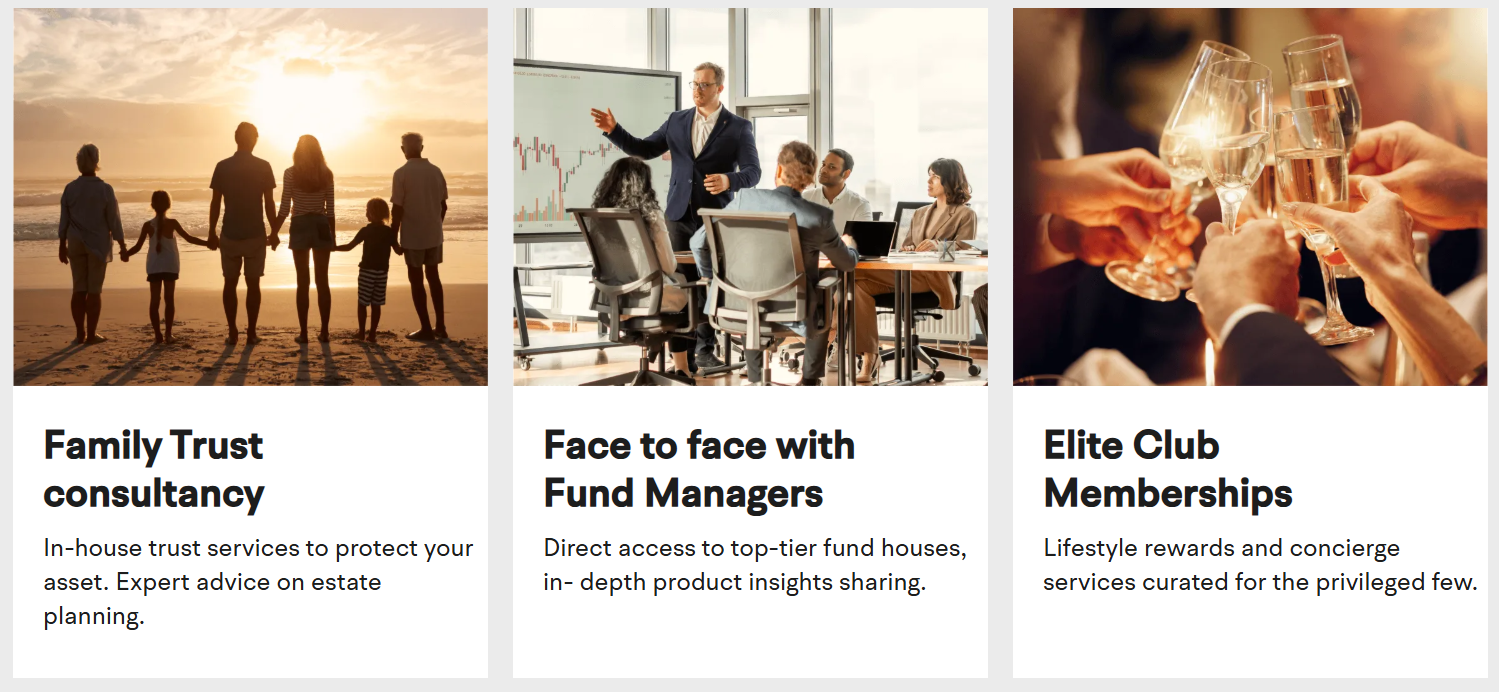
Beyond financial services, Moomoo Private Wealth enhances its value proposition by offering exclusive lifestyle benefits and networking opportunities. Clients gain entry to invitation-only events, including luxury product launches, art exhibitions, and industry summits featuring global thought leaders.
FAQs on Private Banking in Singapore
Is Private Banking the Same as Wealth Management?
Private banking and wealth management are related but distinct concepts. Wealth management is a broad term encompassing strategies to grow, protect, and transfer wealth, including investment advisory, tax planning, and estate management. Private banking, by contrast, is a specialized subset of wealth management offered by banks, tailored exclusively to HNW clients. It combines personalized financial services with preferential banking benefits, such as dedicated relationship managers, exclusive investment opportunities, and concierge services.
How Much Money Do You Need for Private Banking?
Eligibility for private banking in Singapore typically requires a certain investable asset threshold, though this varies by institution. Traditional private banks often set thresholds of $1.5 million to $10 million in assets under management (AUM).
What is the Difference between Private Banking and Normal Banking?
The core differences between private banking and normal (retail) banking lie in client segmentation, service depth, and exclusivity:
Client Focus: Retail banking serves the general public with standardized products (e.g., savings accounts, personal loans), while private banking targets HNWIs with bespoke solutions.
Services: Private banking offers holistic wealth management—including portfolio management, succession planning, and cross-border tax advice—alongside premium perks like priority banking, fee waivers, and global concierge services. Retail banking focuses on basic transactional needs.
Relationship Model: Private banking assigns dedicated relationship managers to oversee clients' financial lives, whereas retail banking relies on general customer service channels.
Pricing: Private banking services often involve higher fees but justify costs through personalized strategies and exclusive access, whereas retail banking prioritizes low-cost, mass-market pricing.
Which Private Bank is the Best in Singapore?
There is no universal "best" private bank, as suitability depends on individual needs. However, Singapore's private banks are globally recognized for stability, expertise, and innovation.
When evaluating options, prioritize banks with strong regulatory compliance (e.g., licensed by the Monetary Authority of Singapore), a track record in your target markets, and technology-driven tools for real-time portfolio management.
Conclusion: Beyond Private Banking
As the financial landscape continues to evolve, the role of traditional private banking in serving high-net-worth individuals (HNWIs) is being redefined. The modern investor pursues a combination of discretion, expertise, along with agility, transparency, and personalized digital access in wealth management. This shift has catalyzed the rise of next-generation digital wealth platforms that harness artificial intelligence, big data analytics, and secure cloud infrastructure to deliver tailored investment strategies. These platforms are not merely alternatives—they represent a paradigm shift in how wealth is managed, preserved, and grown.
While Moomoo Private Wealth does not operate as a traditional private bank, it provides a modern and innovative option for HNWIs interested in exploring technology-driven wealth management solutions.
In this new era, security remains paramount. Investors demand robust data protection, regulatory compliance, and a trusted environment in which to grow their assets. Platforms like Moomoo SG respond to these needs by combining advanced AI-powered tools with a personalized, human-centric approach. Operating under the stringent oversight of the Monetary Authority of Singapore (MAS), Moomoo Private Wealth Management integrates cutting-edge AI-powered tools with a human-centric approach, offering a comprehensive, accessible solution for HNWIs.
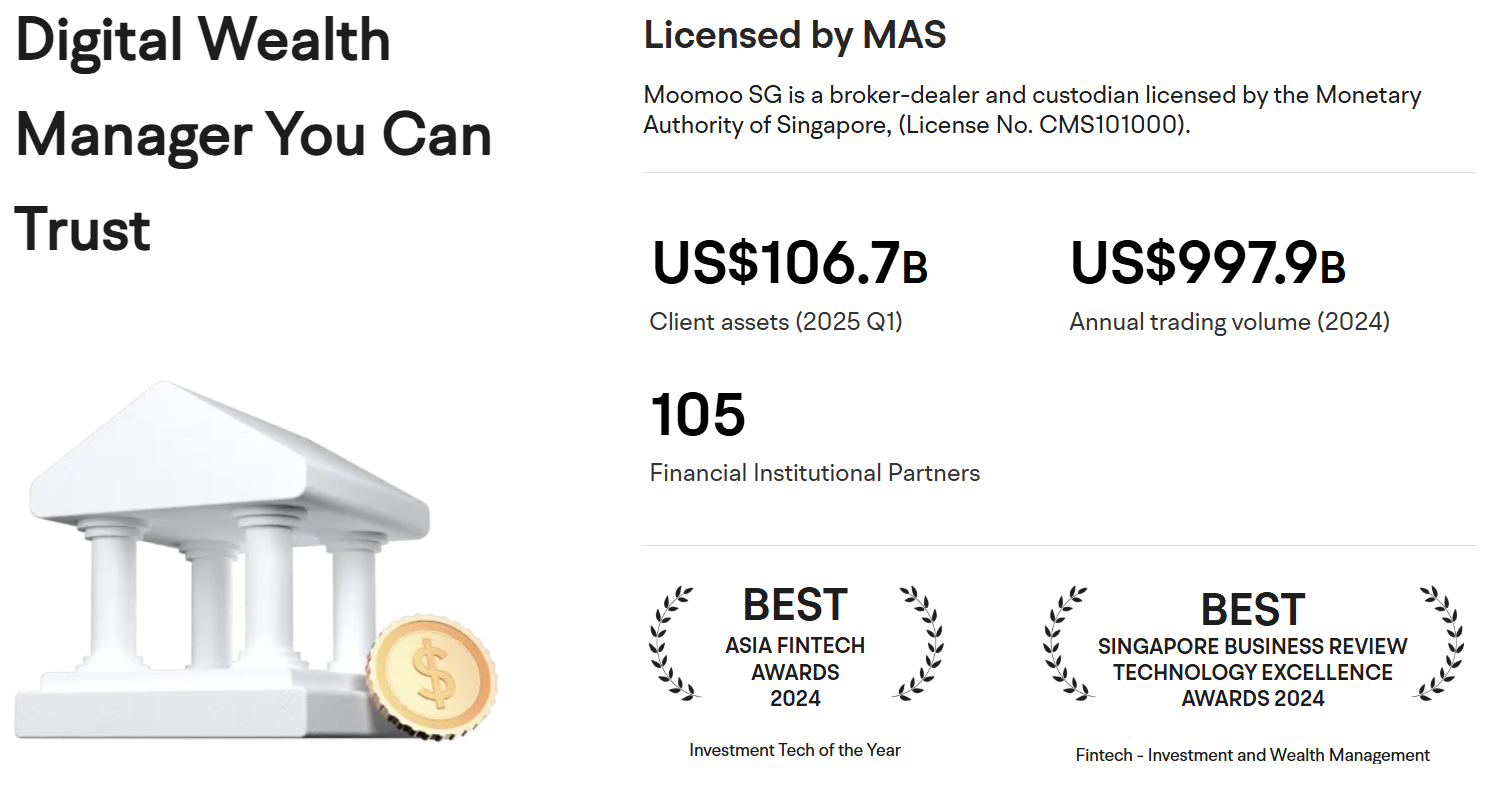
With Moomoo Private Wealth, clients enjoy priority access to exclusive investment products, bespoke wealth solutions, and seamless integration of technology that enables real-time portfolio management. Moreover, the platform goes beyond wealth management by offering premium lifestyle benefits and exclusive networking opportunities—an essential value-add for HNWIs who seek a holistic approach to wealth.
Ultimately, the future of private banking may depend on adaptability, transparency, and technological innovation. While traditional private banks may face challenges in meeting the evolving expectations of today's investors, platforms like Moomoo Private Wealth are innovating beyond traditional models, introducing new approaches that reflect the evolving landscape of 21st-century wealth management.
This presentation is for informational and educational use only and is not a recommendation or endorsement of any particular investment or investment strategy. Investment information provided in this content is general in nature, strictly for illustrative purposes, and may not be appropriate for all investors. Read more