Fed Holds Rates in Powell’s Final Meeting: What’s Next for Markets?

Where Smart Money Flows | Wall Street's Make-or-Break Earnings Week. Can the AI Rally Hold?
Weekly Market Update
Bursa Malaysia ended the week of April 20–24 firmer, with the $FTSE Bursa Malaysia KLCI Index (.KLSE.MY)$ rising about 1.5% to close at 1,720.34, supported by easing U.S.–Iran tensions and solid March trade data (+9.3% YoY). Sentiment peaked mid-week before profit-taking capped Friday's session, with plantations, utilities and healthcare leading the sectoral declines, while the ringgit drifted slightly weaker to around 3.96 against the U.S. dollar. The new week opened on a firmer note, with the FBM KLCI starting Monday up 4.14 points at 1,724.47 amid mixed sentiment as tech-led optimism partly offset lingering geopolitical and oil-price concerns.
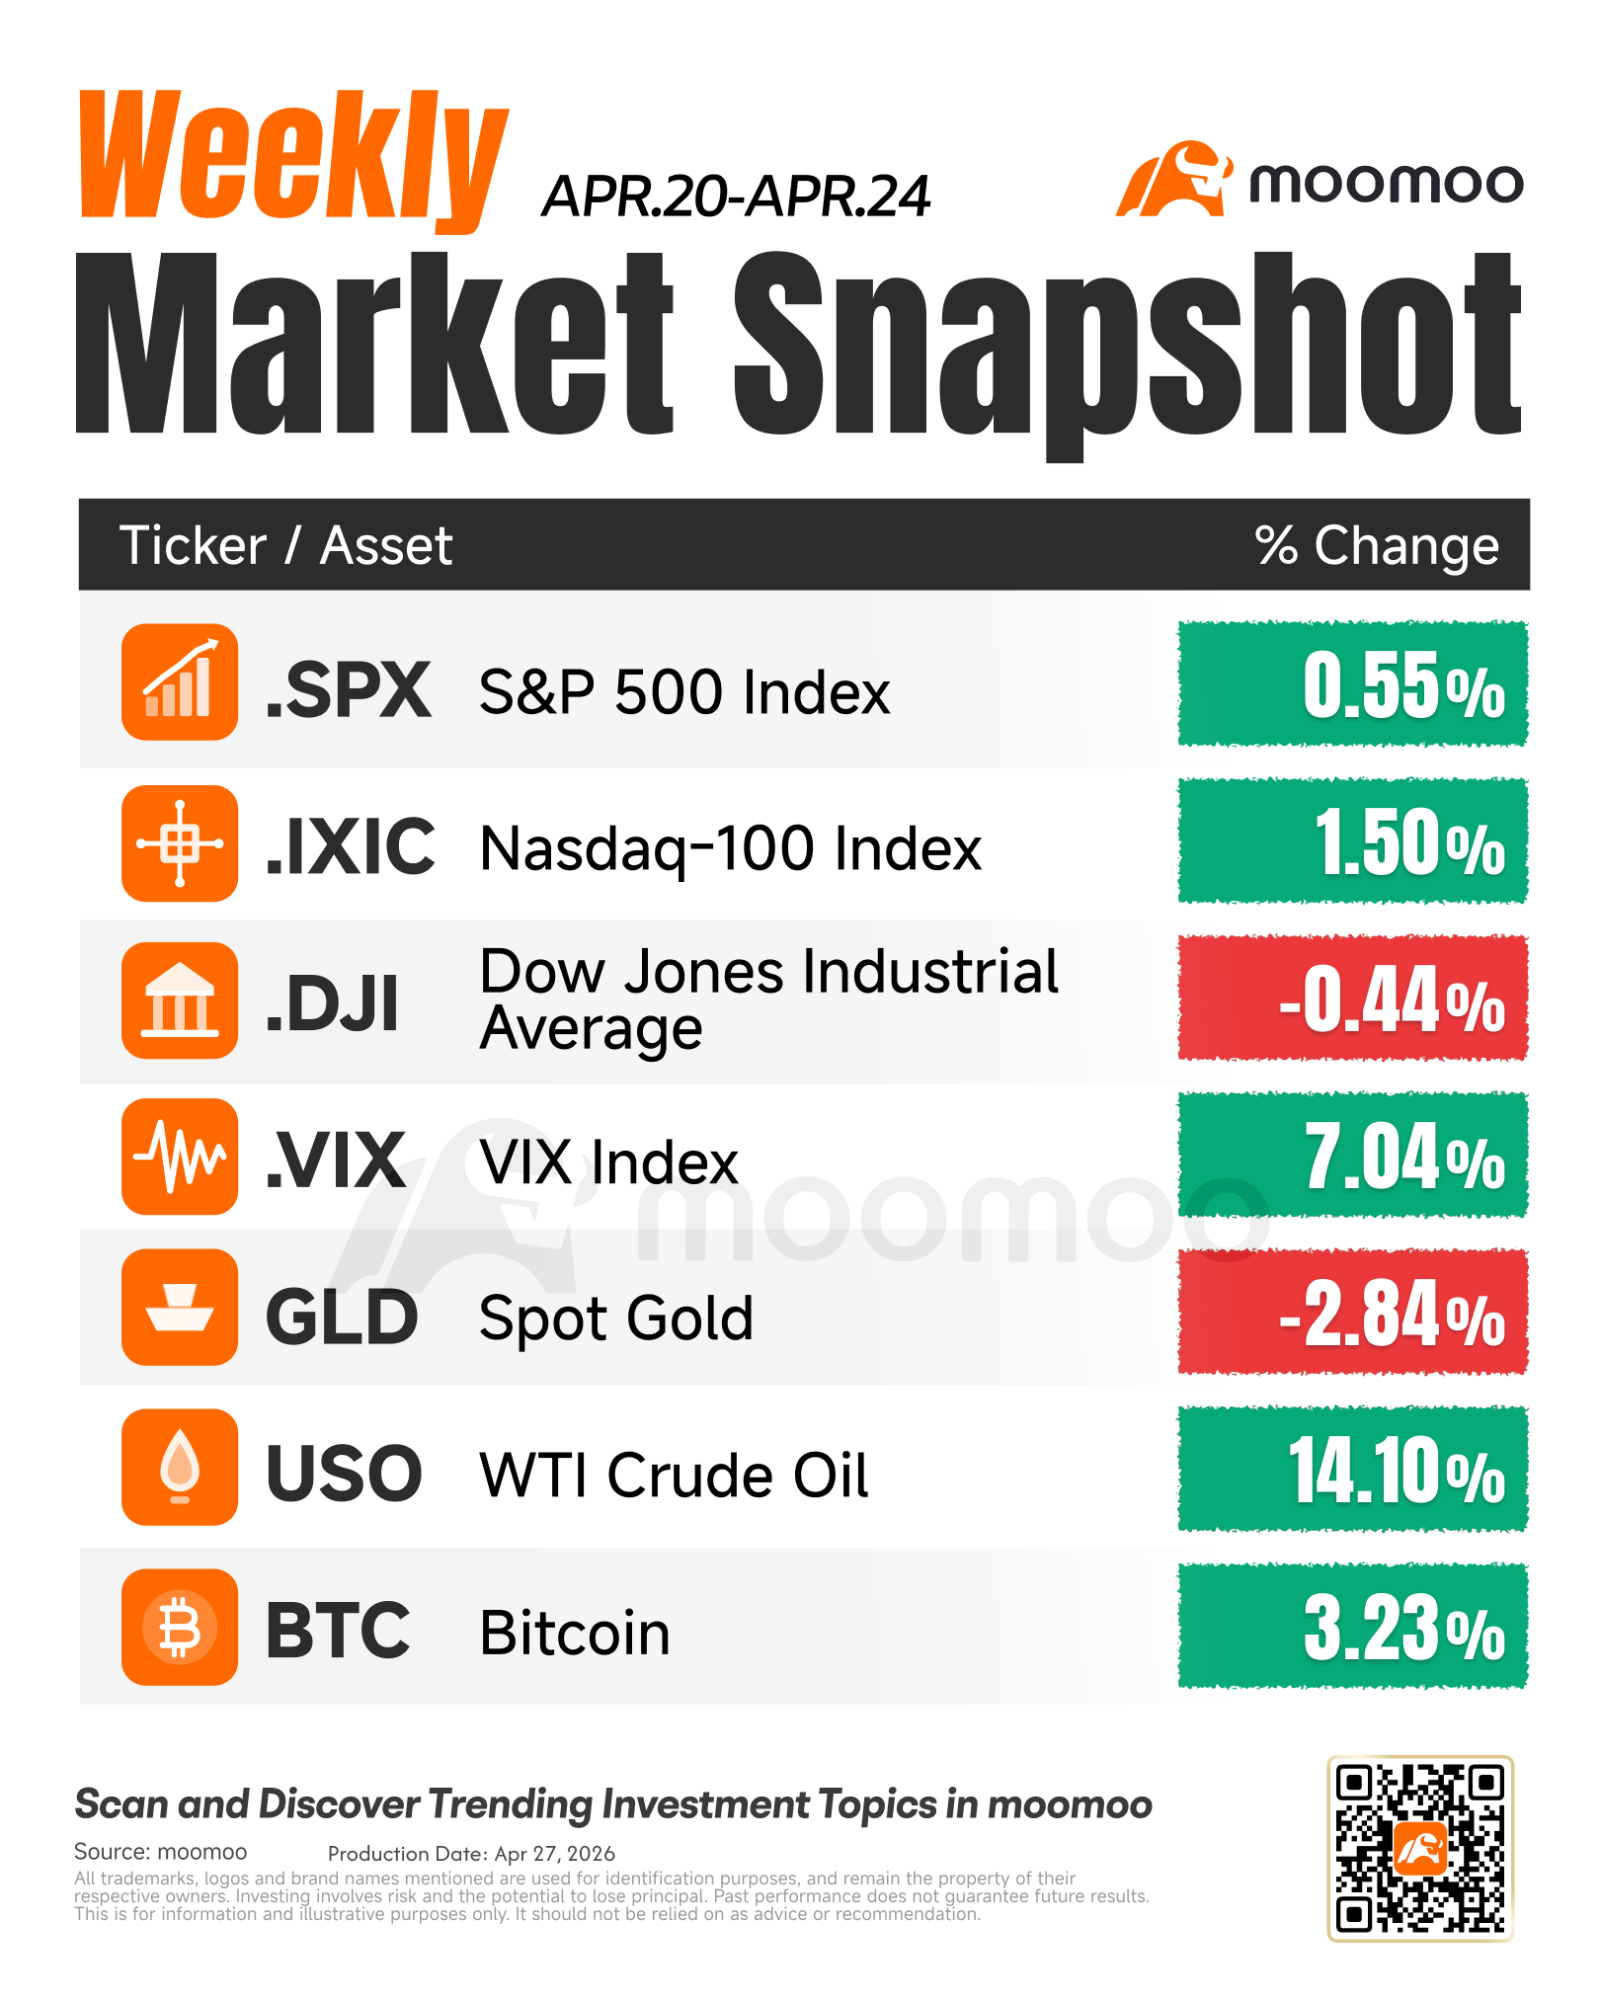
Last week, U.S. equities saw a mixed finish as a three-week rally leveled off. While strong semiconductor earnings managed to lift the $Nasdaq Composite Index (.IXIC.US)$ by 1.5% and edge the $S&P 500 Index (.SPX.US)$ to a new record, the Dow closed slightly lower. Beyond the stock market, shifting geopolitical tensions in the Middle East drove a sharp rebound in oil, pushing U.S. crude from $83 to roughly $95 per barrel, though it remains well below its April peak of $113.

--
--
--
Trading Heat Lists
According to last week's moomoo trading data,let's take a look at which companies everyone bet on:

--
--
--
MTTSL Slips Underwater on Lacklustre Bursa Debut
On Tuesday, April 21, $MTTSL (5352.MY)$ opened at RM1.08 (vs. its RM1.03 IPO price) before all gains evaporated within minutes; the stock closed at RM1.00 on debut day, down ~3% on volume of 62 million shares. The IPO raised RM652 million (Malaysia's largest transport & logistics offering since Westports in 2013), with retail demand oversubscribed nearly 3x and 95.7% of proceeds earmarked for at least 12 container vessels over three years; further profit-taking later in the week dragged the stock toward the mid-RM0.90s.
Twin "Buy" Initiations Lift SUNMED, Outweighing EPF's Exit as Substantial Shareholder
Maybank IB's Monday Buy initiation (TP RM2.01) lifted $SUNMED (5555.MY)$ 4.9% to RM1.93 on April 20; on April 21 The Edge reported EPF had ceased being a substantial shareholder after trimming its stake below 5%, with the stock holding flat at RM1.93. AmInvestment's Buy call on Wednesday (TP RM2.22) was followed by mild profit-taking to RM1.91 / RM1.89, before a 1.6% rebound on Friday to RM1.92 left the counter up ~4.3% for the week (RM1.84 → RM1.92), an outperformer in an otherwise softer healthcare sector.
AAX Whipsawed by Oil and Iran Headlines, Closes the Week Down Around 6%
$AAGB (5238.MY)$ endured a violent week, swinging from RM1.30 on Monday to RM1.40 on Tuesday before plunging to RM1.23 by Thursday, as Brent oil hovered near US$106 and analysts again flagged the airline as the most exposed regional carrier given its zero fuel hedges (a scenario PublicInvest had earlier modelled at jet fuel of up to US$200 per barrel). A modest 1.6% bounce on Friday to RM1.25 followed AAX's proposal to rename itself "AirAsia Group Bhd" as part of its RM6.8 billion takeover of Capital A's short-haul operations, but the stock still closed the week down about 6% from RM1.33 a week earlier.
Strategic Concerns Outweigh Tesla Q1 Earnings Beat
$Tesla (TSLA.US)$ reported a Q1 2026 earnings beat with $22.38 billion in revenue and $0.41 EPS, but the stock quickly reversed as investors reacted negatively to Elon Musk's earnings call. The sell-off was driven by three main concerns: a 25% increase in 2026 capex guidance to $25 billion, admissions that unsupervised Full Self-Driving (FSD) is not ready for scale, and confirmation that older Hardware 3 vehicles cannot support the new FSD system without upgrades. Combined with ongoing political exposure and tariff risks, these factors drove Tesla to its sixth consecutive weekly decline.
Solid Earnings and Strategic Wins Validate Intel Turnaround
$Intel (INTC.US)$ closed the week up nearly 21%, primarily fueled by a massive Q1 earnings beat that validated its turnaround strategy under CEO Lip-Bu Tan. The company reported $13.6 billion in revenue and $0.29 in adjusted EPS, easily topping estimates, with solid growth in both its Data Center & AI and Foundry segments. Adding to the momentum, Tesla confirmed plans to utilize Intel's 14A chip process, complementing recent backing from Nvidia and the U.S. government. Following this historic rally, Citi upgraded the stock to "Buy" with a $95 target, emphasizing Intel's unique strategic value as a leading domestic chipmaker.
Weekly Trends
The week ahead is expected to be choppy and liquidity-thin for Bursa Malaysia, with only four trading sessions before the Labour Day closure on Friday and the $FTSE Bursa Malaysia KLCI Index (.KLSE.MY)$ seen anchored on firm support above 1,700 but capped by its overhead downtrend line, pointing to a range-bound profile unless a fresh catalyst emerges.
Sentiment will hinge on three external swing factors — U.S.–Iran peace-talk progress, crude oil moves and foreign fund flows — while domestic investors position ahead of Malaysia's strategic response to U.S. tariffs at the May 5 special Dewan Rakyat sitting.
Within the index, sector rotation should continue to favour tech names riding regional momentum and AI/digitalisation themes, alongside large-cap defensives with visible earnings, while plantation and oil-sensitive counters remain hostage to commodity swings.
The bigger directional cue for global risk appetite, however, sits across the Pacific, where this week packs three of 2026's biggest catalysts into just four sessions with Wall Street already at fresh record highs: Wednesday's FOMC is virtually certain to hold the funds rate at 3.50-3.75% in Powell's final meeting before Kevin Warsh takes over, leaving the dot-plot tone and forward guidance — not the rate decision itself — as the real swing factor amid still-above-target inflation.
The same evening also brings four "Magnificent Seven" prints ($Microsoft (MSFT.US)$, $Alphabet-C (GOOG.US)$, $Amazon (AMZN.US)$, $Meta Platforms (META.US)$), where AI capex-versus-revenue conversion will be the litmus test, with $Apple (AAPL.US)$ following after Thursday's close to round out the AI-trade scorecard with iPhone-versus-Services in focus; layered on top of advance Q1 GDP, March PCE inflation and ADP/JOLTS, plus still-elevated oil and Iran headlines, the set-up points to a binary, high-volatility tape for U.S. equities.

Track the heat list, uncover market hotspots!

ข้อความสงวนสิทธิ์: Moomoo Technologies Inc. นำเสนอเนื้อหานี้เพื่อวัตถุประสงค์ในการให้ข้อมูลและการศึกษาเท่านั้นอ่านเพิ่มเติม


ความคิดเห็น (1)
เพื่อแสดงความคิดเห็น
20
2