
Where Smart Money Flows | U.S. Markets Snap Nine-Week Win Streak While KLCI Holds Firm
Weekly Market Update
Last week was a shortened three-day trading week. The $FTSE Bursa Malaysia KLCI Index (.KLSE.MY)$ traded in a tight range between 1,672 and 1,694, following a dip-then-rally pattern over the truncated session.The turnaround came on Thursday and Friday, with the KLCI surging more than 10 points on each day. Strength in the Finance Index and plantation heavyweights drove the index to close the week near the top of its range.
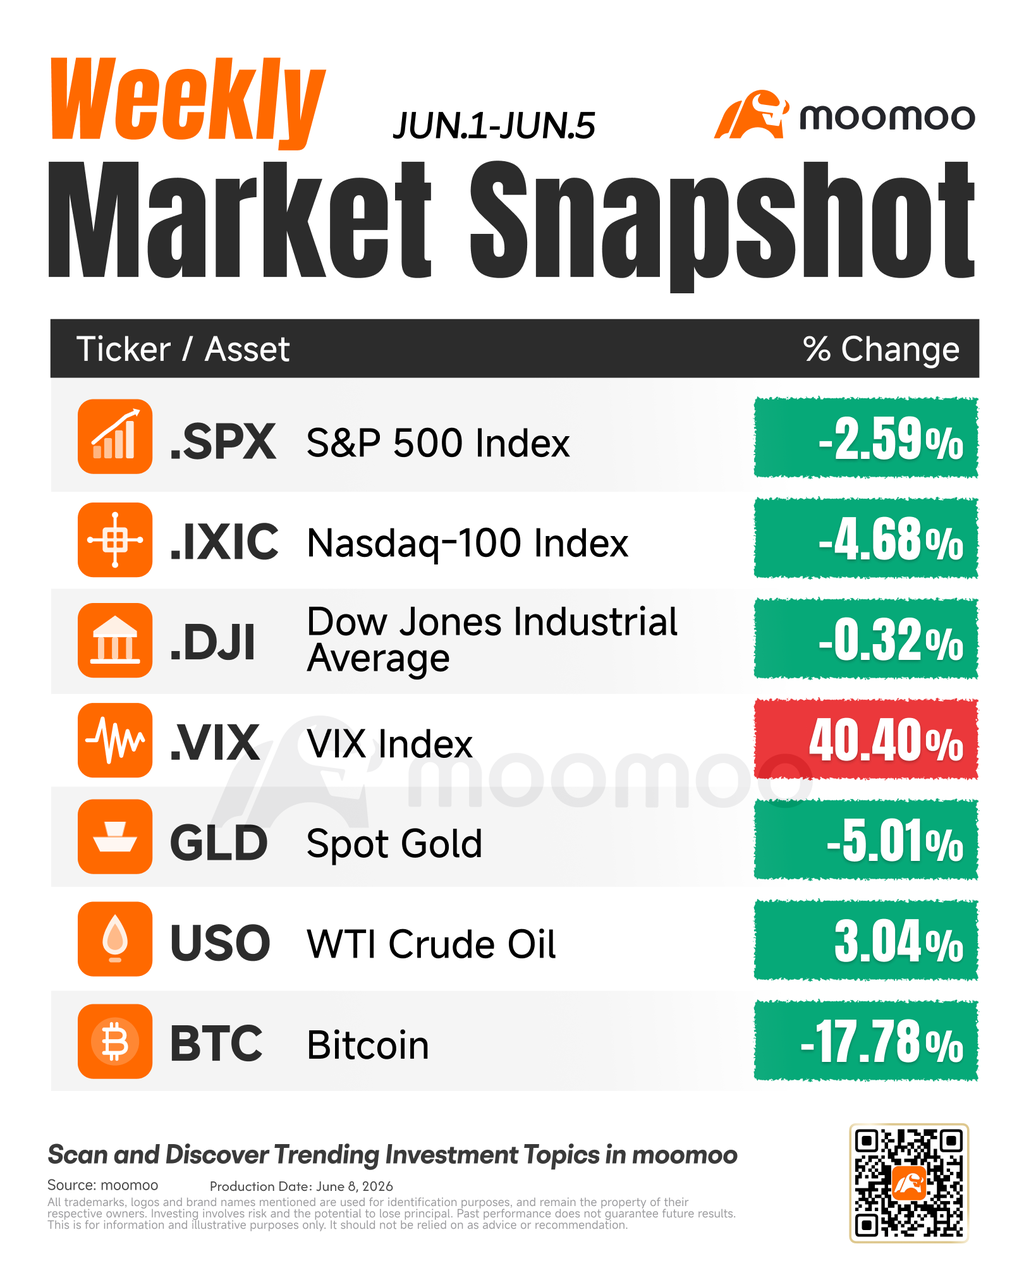
Major U.S. stock indexes snapped a nine-week winning streak last week, as a stronger-than-expected May jobs report reignited rate-hike concerns and a Friday semiconductor selloff erased early-week gains. For the week of June 1–5, the S&P 500 fell 2.6%, the Nasdaq dropped 4.7%, and the Dow slipped 0.3%. The $CBOE Volatility S&P 500 Index (.VIX.US)$ surged 40% as hedging demand returned.
West Texas Intermediate crude rose about 3% amid Middle East volatility, while spot gold fell 5% and Bitcoin slid nearly 18% — its weakest level since September 2024. May payrolls rose 172,000, topping expectations for a third straight month, pushing Treasury yields higher and lifting market-implied odds of a Fed rate hike by year-end.

--
--
--
Trading Heat Lists
According to last week's moomoo trading data,let's take a look at which companies everyone bet on:

--
--
--
CIMB Sees Institutional Accumulation Emerge After Softer Q1 Earnings
$CIMB (1023.MY)$ slipped ~1.20% last week, trading within RM7.35–7.49 as markets digested a softer Q1 2026 result (net profit RM1.92b, -2.9% YoY) driven by higher consumer provisions and a 2bp NIM compression. However, fee income improved sequentially, funding costs fell 7bp, and Thursday's broad institutional bid across financials suggests smart money may be positioning strategically post-weakness. At ~RM7.35 — the lower end of its 52-week range (RM6.45–8.95) — the FY25 record dividend payout of RM5.1b keeps the value case intact. Watch for a sustained reclaim of RM7.50 as the key near-term signal.
Skyechip's Post-IPO Distribution Pattern Persists as a Structured Warrant Launch Amplifies Volatility
$SKYECHIP (5357.MY)$ continued its post-listing retreat, trading RM2.90–3.03 before softening to ~RM2.88 — down 24% from its May 20 debut high of RM3.80. The mid-week launch of structured warrant SKYECHIP-CA, less than two weeks after listing, signals strong derivative demand but also increased arbitrage activity likely to amplify near-term volatility. The price action since IPO reflects classic smart money distribution into retail strength. Support is referenced at RM2.75–2.81. IPO holders may consider partial profit-taking with RM2.75 as a stop-loss reference; new entrants should await price stabilisation and volume contraction before initiating positions.
Buscap Delivers an Impressive ACE Market Debut
$BUSCAP (0455.MY)$ debuted on June 3 at an IPO price of 23 sen, surging to a 36.5 sen intraday high before closing at 31.5 sen (+37%) on turnover of 124 million shares. However, smart money signals flashed early: a director sold at 34 sen on listing day, while major shareholders had already offloaded over 19 million shares at IPO price before debut. The stock has since consolidated around 30 sen. IPO subscribers retain ~30% paper gains but should watch for further selling as moratorium periods expire. Fundamentally a niche bus body manufacturer with a capacity expansion narrative, BUSCAP offers limited near-term catalysts and suits a longer-term holding horizon.
Marvell Surges 29% on Huang Endorsement and S&P 500 Entry
$Marvell Technology (MRVL.US)$ recorded a 28.52% weekly gain to top the U.S. heat list, fueled by Nvidia CEO Jensen Huang's declaration at COMPUTEX that Marvell could be the "next trillion-dollar company" for AI data-centre connectivity. The rally accelerated after S&P Dow Jones Indices confirmed Marvell will join the S&P 500 on June 22, a move that could draw passive inflows. Nvidia's prior US billion strategic investment added further credibility to the networking-chip narrative. Marvell's surge stood out against a bruising week for semiconductors, underscoring how stock-specific catalysts can still dominate even when the broader AI complex sells off.
Micron Extends Gains as AI Memory Trade Proves Resilient
$Micron Technology (MU.US)$ rose 11.02% last week, remaining among the most-traded U.S. names on moomoo even as profit-taking hit parts of the semiconductor sector. Traders continued to treat high-bandwidth memory as a core AI infrastructure bet, with Micron benefiting from sold-out capacity and a string of analyst target upgrades following its push above a US trillion market capitalisation in late May. The stock's resilience during a volatile week suggests memory demand remains a favoured expression of the AI buildout — even when custom-chip leaders such as Broadcom disappoint on guidance.
Weekly Trends
This week, market attention turns to inflation and a fresh wave of technology earnings. May CPI on Wednesday is the headline macro release: investors will watch whether headline inflation stays hot on energy while core pressure eases — a mix that could keep both rate-hike and rate-cut narratives alive.
On earnings, $Oracle (ORCL.US)$ reports after Tuesday's close, with Adobe following on Thursday — both will be read as tests of whether AI spending is translating into durable cloud and software revenue. In the U.S., the long-awaited SpaceX IPO is set to price on Friday, June 12, marking a landmark moment for public markets.
The most significant structural catalyst this week is the upcoming KLCI constituent reshuffle. FTSE Russell officially announced on June 4 that $IOIPG (5249.MY)$ will replace $SIME (4197.MY)$ in the FBM KLCI, effective June 22. With just two weeks until the change takes effect, passive index-tracking funds will be required to buy IOIPG and sell down SIME on the effective date — and the market typically front-runs these flows well in advance. Near-term fund flows into IOIPG are worth watching, while SIME may face sustained passive selling pressure in the lead-up.
The global AI narrative continues to underpin risk sentiment. U.S. equities posted fresh all-time highs last week, led by $NVIDIA (NVDA.US)$ and $Broadcom (AVGO.US)$, with enthusiasm for the tech trade showing no signs of fading. This has positive spillover implications for local technology-linked names, including $SKYECHIP (5357.MY)$.

Track the heat list, uncover market hotspots!

ข้อความสงวนสิทธิ์: Moomoo Technologies Inc. นำเสนอเนื้อหานี้เพื่อวัตถุประสงค์ในการให้ข้อมูลและการศึกษาเท่านั้นอ่านเพิ่มเติม


ความคิดเห็น (2)
เพื่อแสดงความคิดเห็น
13
3