Retirement Planning in Malaysia 2026: A Complete Guide
Key Takeaways
Retirement Planning in Malaysia: Emphasizes proactive financial planning, including use of the Employees Provident Fund (EPF) and diversified investments like stocks, bonds, mutual funds, and real estate.
Key Steps: Set retirement goals, save and invest early, account for healthcare costs, monitor investments, and adjust contributions if needed.
Top Strategies: Leverage the power of compounding, maximize EPF contributions, diversify investments (including dividend-paying stocks, bonds, blue-chip REITs), and avoid over-reliance on EPF.
For Late Starters & Self-Employed: Increase savings rate, invest in growth-focused assets, and consider private plans like Solo 401(k) or SEP IRA.
Moomoo MY Products & Solutions: Moomoo Cash Plus offers guaranteed returns (5% p.a.* for 30 days), zero fees, and flexibility for trading stocks or withdrawals, making it a viable retirement option. It includes Shariah-compliant funds.
Understanding the Retirement Planning in Malaysia
Retirement planning in Malaysia is a crucial aspect of financial security that individuals must consider to ensure a comfortable life after ceasing employment. Malaysia, known for its diverse culture and growing economy, offers a unique set of opportunities for those planning for their retirement.
Government Schemes: The government offers initiatives like the Employees Provident Fund (EPF), a mandatory savings plan for private sector workers, to help accumulate retirement funds.
Personal Savings & Investments: Individuals are encouraged to save and invest wisely in options such as stocks, bonds, mutual funds, and real estate to supplement their retirement income.
Healthcare Planning: Considering the rising medical costs, purchasing medical insurance or joining healthcare plans is advisable to manage potential healthcare expenses.
How to Prepare Yourself for Retirement in Malaysia?
Retiring in Malaysia requires careful preparation to ensure a smooth transition from working life to a fulfilling retirement. Here are some tips and steps to help you prepare:
Understand Government Benefits: Familiarize yourself with the retirement benefits offered by the Malaysian government, such as the Employees Provident Fund (EPF) and any applicable pension schemes. Learn about the withdrawal rules and conditions to maximize your benefits.
Assess Your Financial Situation: Start by evaluating your current financial status, including your savings, investments, and debts. Determine your retirement income sources, such as pensions, social security, and investment returns. Calculate your estimated retirement expenses, considering factors like housing, healthcare, and daily living costs.
Stay Active and Engaged: Plan for social and recreational activities to keep yourself active and engaged during retirement. Explore hobbies, volunteer opportunities, or part-time work to maintain a sense of purpose and fulfillment.
Easy Steps for Retirement Planning in Malaysia
In Malaysia, retirement planning may appear to be a far-off consideration; however, the reality is that initiating it earlier will ensure you are more adequately prepared for your senior years. In this section, we'll outline easy-to-follow steps to help you navigate the process of retirement planning in Malaysia, ensuring you have the resources and knowledge to make informed decisions and achieve your retirement goals.
1. Set Clear Goals for Retirement Age and Money
Decide on the age at which you plan to retire and the lifestyle you wish to uphold during retirement firstly. Consider factors like housing, travel, healthcare, and daily expenses. And calculate the exact amount of money you need to save to meet these retirement goals.
2. Save Up and Invest Your Money
To potentially increase your retirement savings, consider investing in stocks or financial products such as mutual funds, exchange-traded funds (ETFs), or unit trusts. Diversify your investments to spread risk, and consider consulting a financial advisor to help you make informed investment decisions based on your risk tolerance and retirement goals.
3. Plan for Healthcare Costs
Healthcare expenses are a significant concern in retirement. Consider purchasing long-term care insurance or setting aside a separate fund for healthcare costs. Stay informed about Medicare and other healthcare options available to you in retirement.
4. Monitor and Adjust Your Investments
Consistently assess your investment portfolio to guarantee that it corresponds with your retirement objectives and risk appetite. Implement necessary modifications, including rebalancing your assets or disposing of investments that are not performing well.
5. Adjust Your Contributions as Needed
If you find yourself falling short of your retirement savings goals, don't panic. Take a closer look at your budget and see where you can make adjustments. Consider increasing your contributions to your retirement plans, even if it's just by a small percentage. Every little bit counts and can make a big difference over time.
Top Retirement Planning Strategies in Malaysia
Retirement planning is a crucial financial endeavor for Malaysians, ensuring a comfortable and secure future. In a dynamic economic landscape, having a well-thought-out retirement strategy is essential. Here are the top retirement planning strategies in Malaysia to help you achieve your long-term financial goals.
Start Early and Leverage the Power of Compounding
Starting to save for retirement earlier allows your money more time to grow via compounding, enabling even modest, consistent contributions to amass into a significant retirement fund over the span of several decades.
Maximize Contributions to the Employees Provident Fund (EPF)
The Employees Provident Fund (EPF) is Malaysia’s primary retirement savings tool, offering tax relief (up to RM100,000/year) and stable returns (5–6% historically). Boost savings by making voluntary contributions and using investment schemes like MIS to diversify into stocks/bonds. Note withdrawal restrictions before retirement age.
Build a Diversified Investment Portfolio
Diversify your investment portfolio to reduce risk. Alongside the EPF, consider investing in stocks, bonds, unit trusts, and real estate in Malaysia stock market. Stocks may offer high returns but come with higher volatility, while bonds provide more stability.
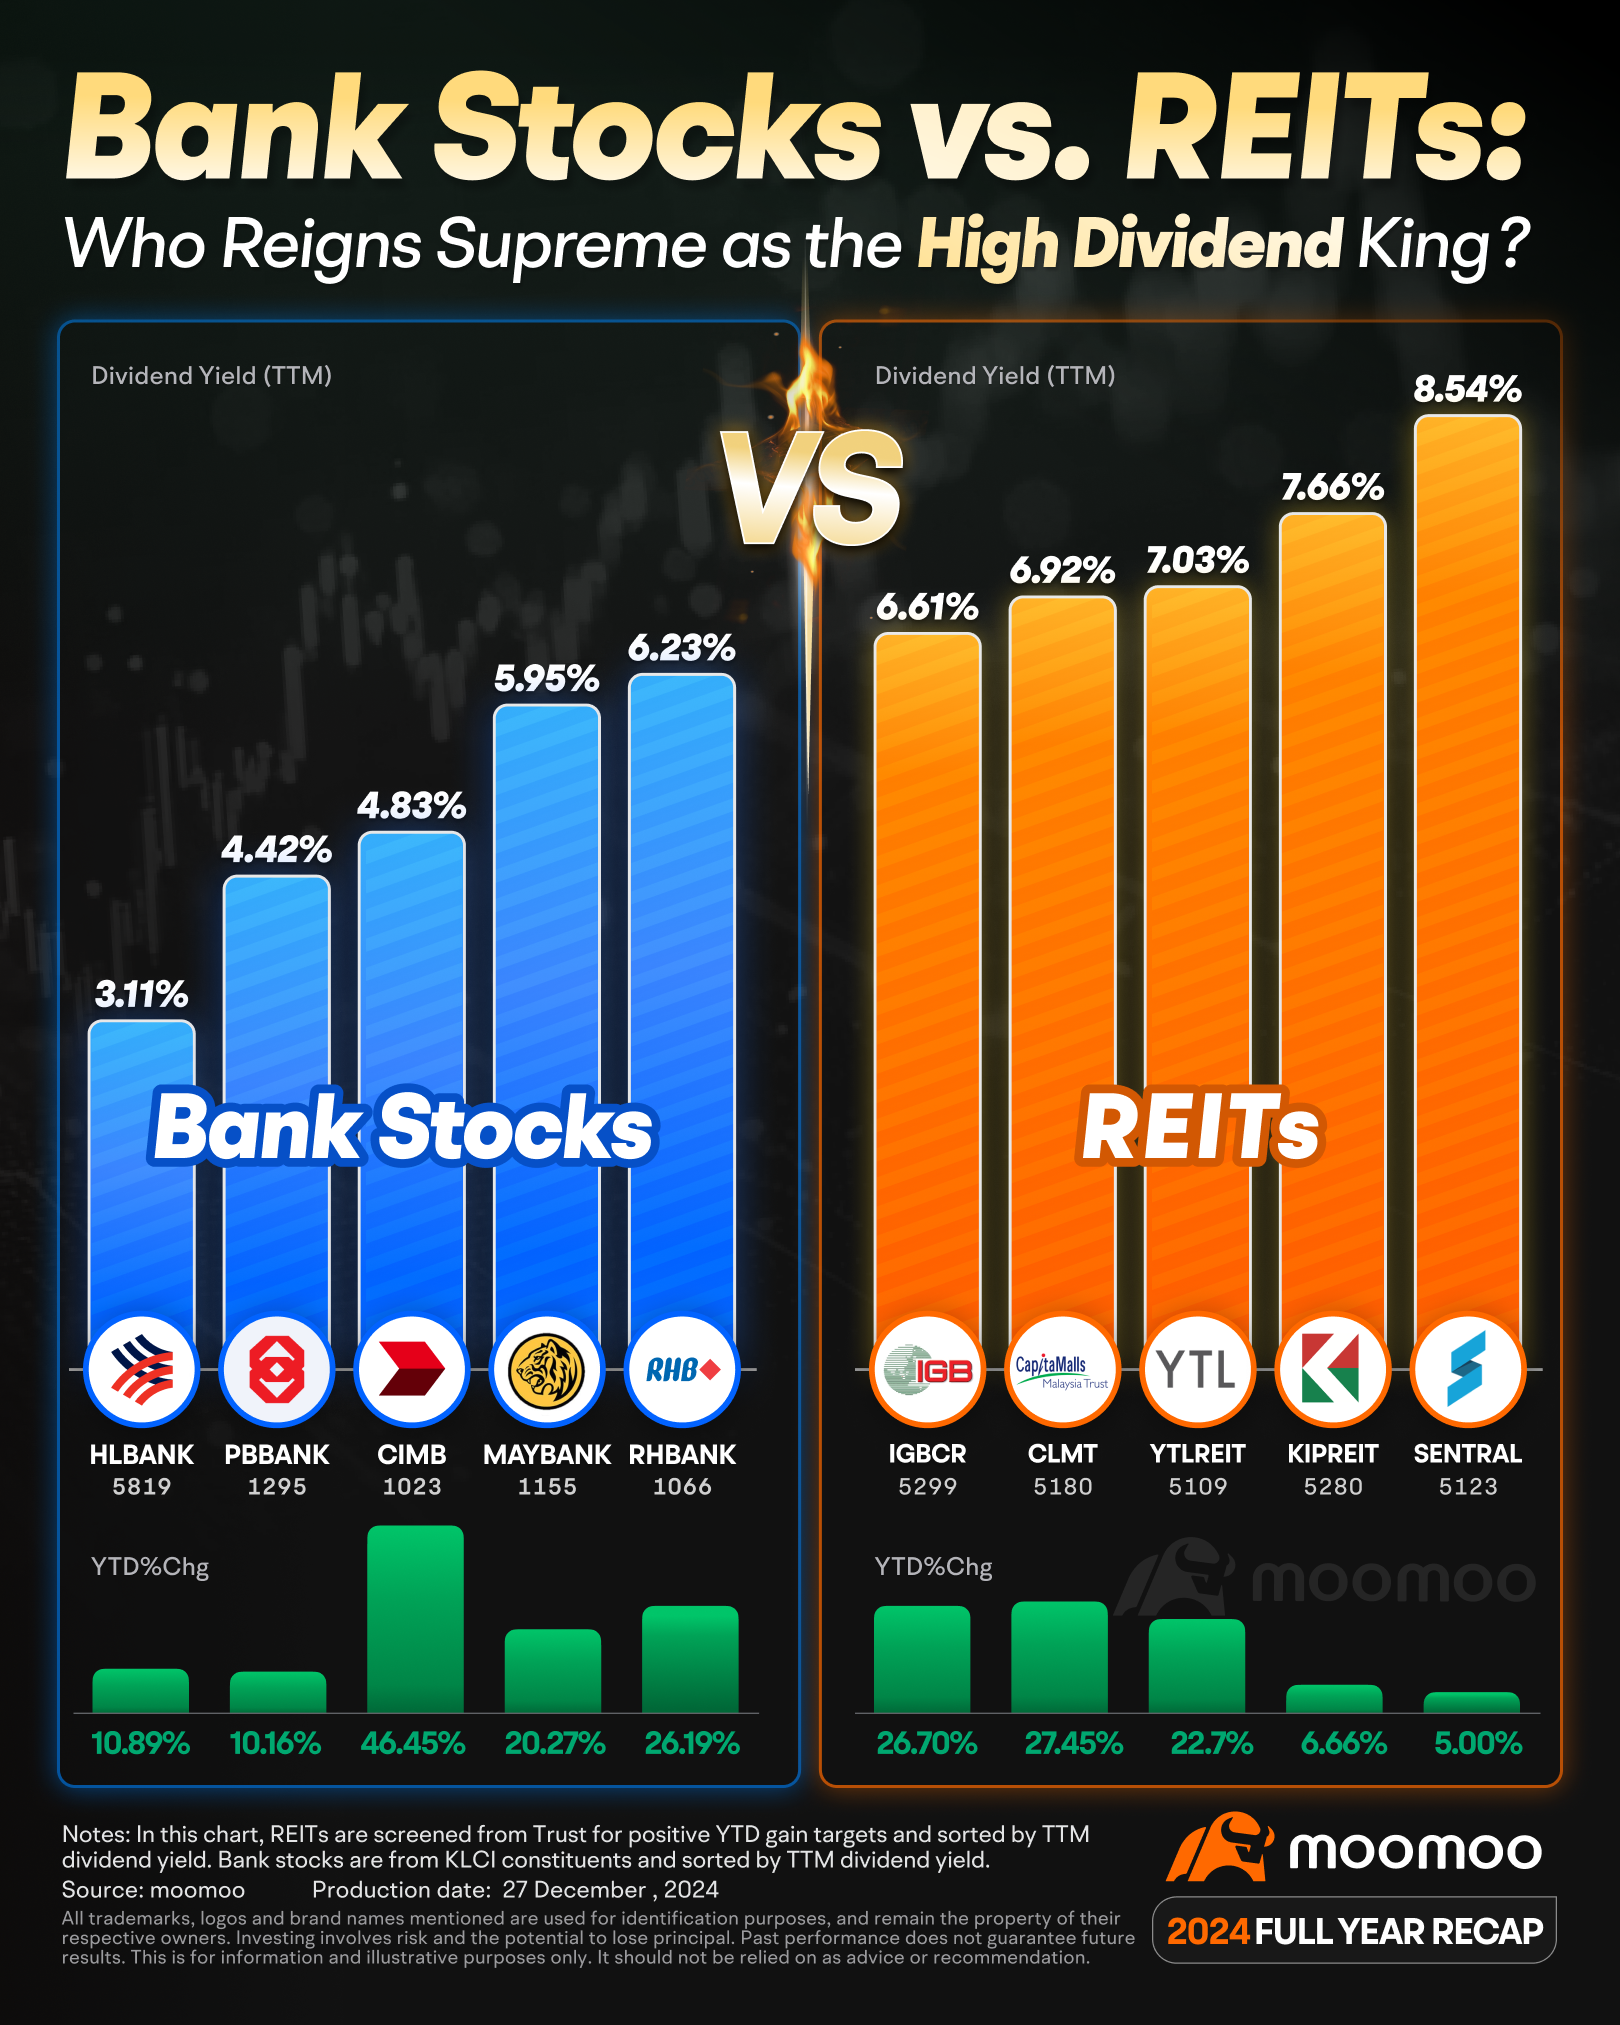
Stocks: Opt for high-dividend stocks that can provide a steady income stream. These stocks are often issued by large, stable companies with a history of consistent dividend payments. To further enhance your stock portfolio, consider investing in bank stocks that have a strong track record of performance and dividend payments.
Bonds: Invest in bonds for more stability and predictable returns. Government bonds, in particular, are considered low-risk investments.
Blue-chip REITs and Dividend Stocks: These investments offer a combination of stability, growth potential, and regular income, making them ideal for retirement portfolios. Blue-chip REITs provide exposure to the real estate market, while dividend stocks offer a steady income stream from large, established companies. To further enhance your retirement portfolio, consider investing in specific blue-chip REITs that have a proven track record of stability and growth.
Retirement Planning Mistakes to Avoid
Retirement planning is a lifelong journey, but even small missteps can derail decades of savings. In Malaysia’s evolving economic climate—marked by inflation volatility, rising healthcare costs, and policy shifts—avoiding these five critical mistakes is essential to securing a stress-free retirement.
Underestimating living expenses
Many Malaysians assume retirement lasts 15–20 years, but life expectancy now exceeds about 76 years (DOSM, life table 2024). A 65-year-old retiree may need RM300,000–RM500,000 for basic healthcare alone, excluding chronic disease management. EPF withdrawals (limited to RM600/month under Skim Pelara) may fall short of covering long-term care.
Solutions:
Purchase medical insurance with lifetime renewability.
Allocate 20% of retirement funds to a dedicated healthcare reserve.
Over-reliance on EPF as the Sole Retirement Pillar
Over-reliance on the Employees Provident Fund (EPF) as the sole retirement pillar can be risky, as it may not provide sufficient income during retirement to maintain your desired lifestyle. While the EPF is a critical component of retirement planning in Malaysia, it's essential to diversify your retirement savings to mitigate risks and ensure financial stability. The EPF's primary focus is on capital preservation rather than growth, which may not align with your long-term retirement goals.
Solutions:
Diversify with Private Retirement Schemes (PRS): Opt for growth-focused funds.
Build a side portfolio in blue-chip REITs or dividend stocks in Malaysia (e.g., Public Bank) for liquidity. What is the best investment in Malaysia?
Why Choose Moomoo Cash Plus for Retirement Planning?
Introduction to Moomoo Cash Plus
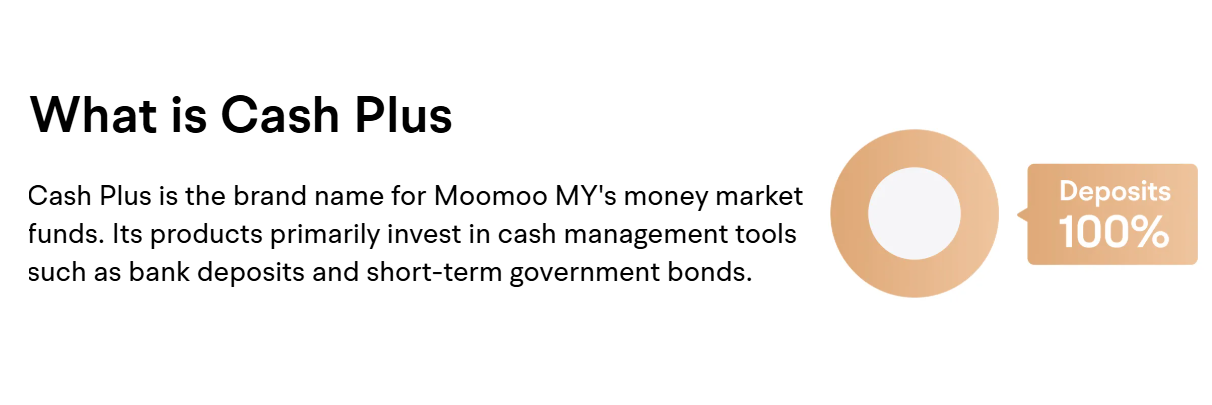
Moomoo Cash Plus, a prominent offering from Moomoo MY, represents a trusted and innovative foray into the realm of money market funds. This brand serves as a gateway to a suite of financial products meticulously designed to optimize cash management for investors. By primarily investing in secure and liquid instruments such as bank deposits and short-term government bonds, Moomoo Cash Plus ensures a balanced approach to growing your wealth while maintaining capital accessibility. Whether you're an individual seeking to maximize your savings potential or a business looking to efficiently manage your working capital, Moomoo Cash Plus offers a reliable and flexible solution tailored to meet.
Why Choose Cash Plus for Retirement Planning
When it comes to securing your financial future, Moomoo Cash Plus stands out as an exceptional choice for retirement planning. Here are three compelling reasons why Cash Plus should be an integral part of your retirement strategy:
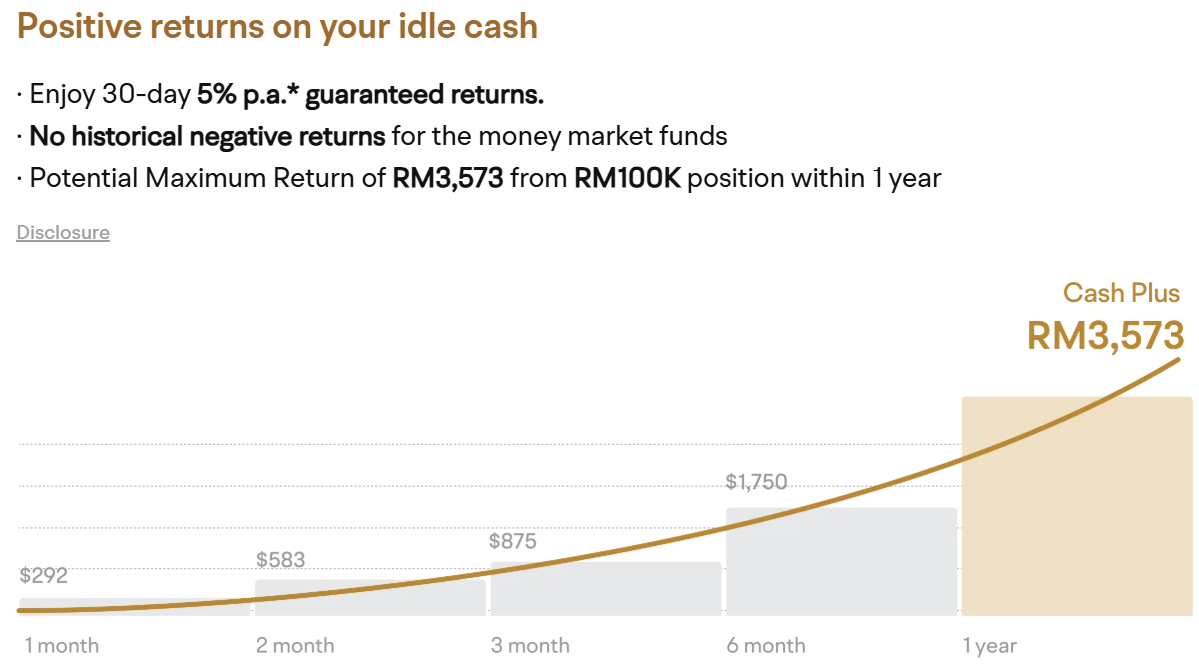
1. Guaranteed Returns on Your Idle Cash: With Moomoo Cash Plus, you can enjoy a guaranteed 30-day annual return rate of 5% p.a.* on your invested funds. What's more, if the annual return rate of your subscribed fund falls below this threshold, Moomoo MY will subsidize the difference for up to 30 days in the form of cash coupons, capped at RM10,000 for your first subscribed fund. This unique feature ensures that your idle cash is always working for you, providing a steady and predictable income stream. For new users, this subsidy becomes available 30 days after their initial subscription, offering an immediate boost to your retirement savings.
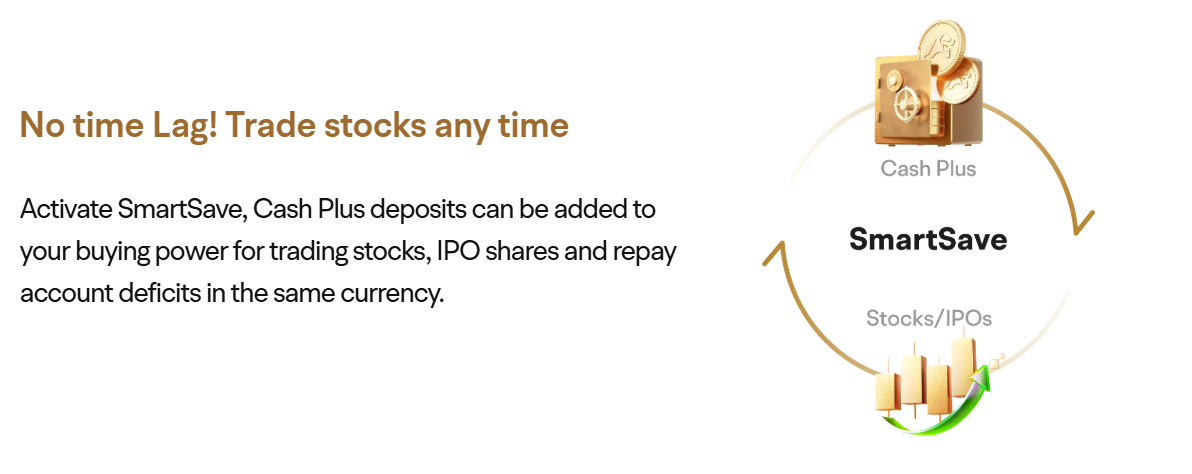
2. Buy and Sell Stocks Instantly: Flexibility is key in retirement planning, and Moomoo Cash Plus offers unparalleled access to your funds. Unlike traditional investment vehicles that may restrict your access to capital, Cash Plus allows you to trade stocks at any time without any delays. This means you can seize market opportunities as they arise, adjust your portfolio as needed, and maintain full control over your financial future.
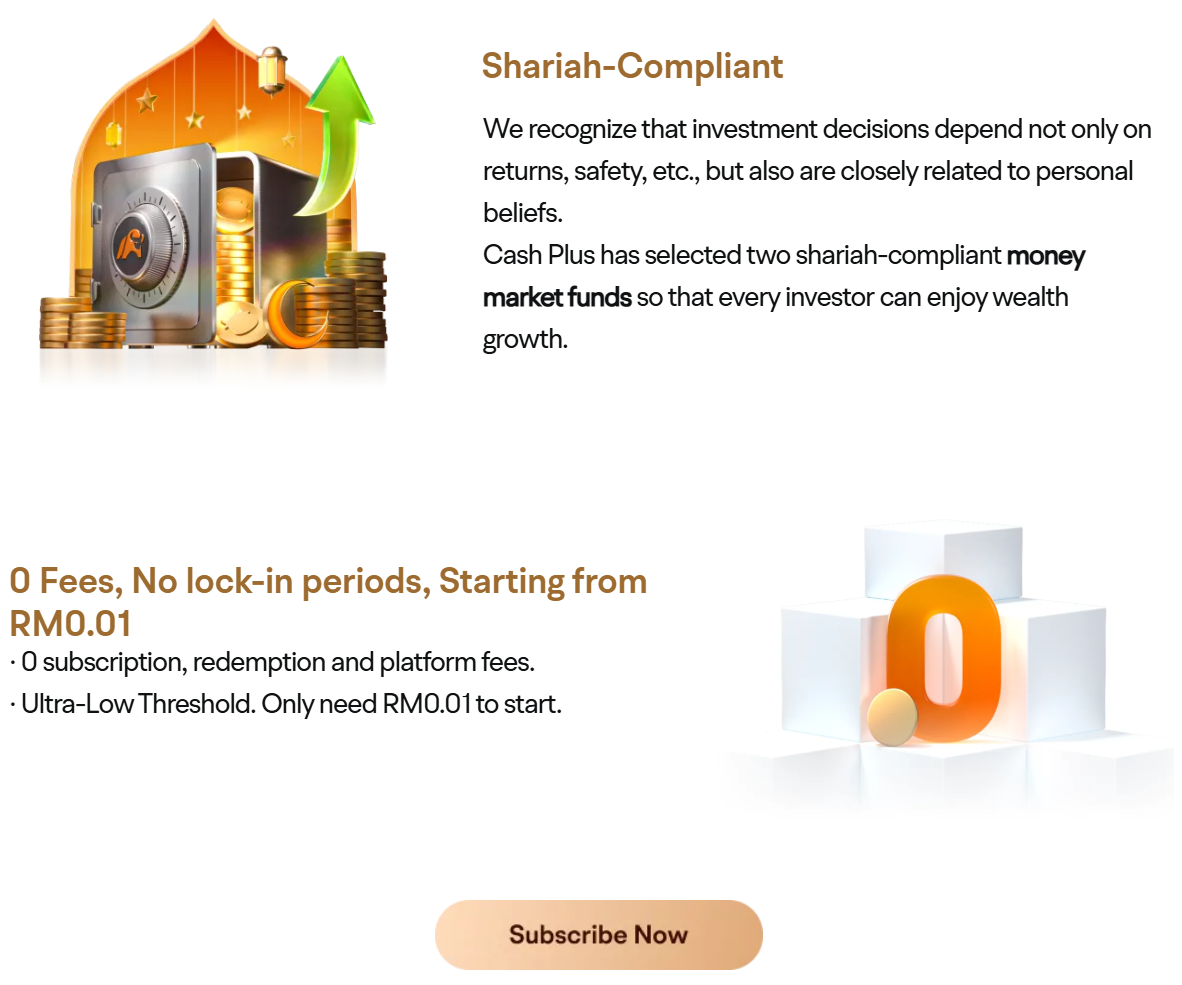
3. Zero Fees, No Commitment, Invest from Just RM0.01: Moomoo Cash Plus is designed to be inclusive and accessible to all. With zero fees and no lock-in periods, you can start investing with as little as RM0.01. This low barrier to entry makes it easy for you to begin building your retirement fund, regardless of your current financial situation. Whether you're just starting out or looking to supplement your existing retirement savings, Cash Plus provides a hassle-free and cost-effective way to grow your wealth over time.
How to Invest in Cash Plus in Malaysia
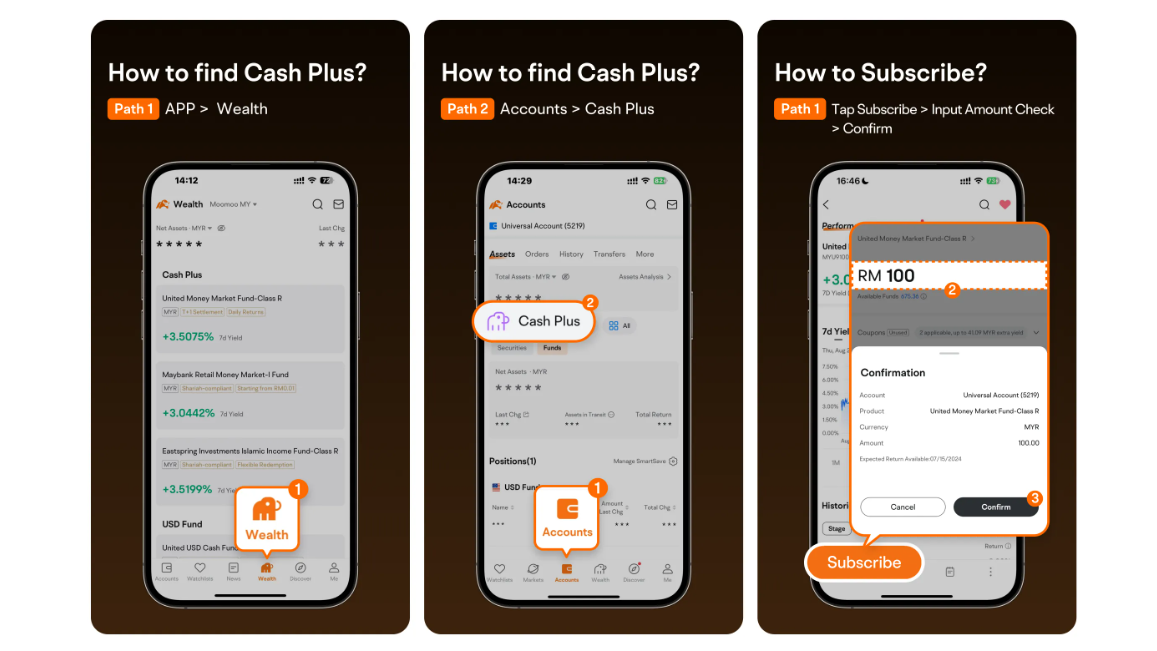
1. Finding Cash Plus
Path 1: Open the app and tap on "Wealth". You'll find Cash Plus listed among the options.
Path 2: Go to "Accounts" and then select "Cash Plus".
2. Subscription
Tap "Subscribe", input the amount you want to invest (e.g., RM 100 as shown), and then confirm the details.
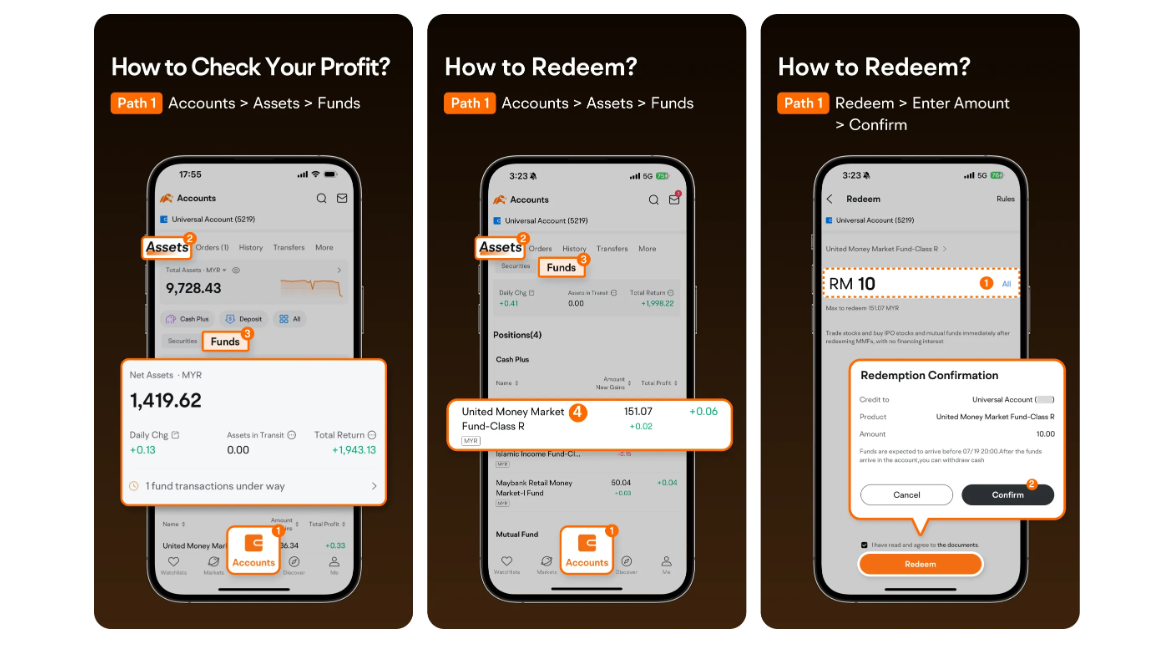
3. Checking Profits
Navigate to "Accounts", then "Assets", and select "Funds". Here, you can view your net - assets, daily changes, and total returns. How to invest in money market funds?
FAQs on Retirement Planning in Malaysia
How much should I save for retirement?
Determining how much to save for retirement depends on several factors, including your current age, desired retirement age, lifestyle expectations in retirement, and expected income sources such as pensions or Social Security. Typically, financial experts suggest saving a minimum of 10-15% of your yearly income for retirement as a standard guideline. However, it's essential to conduct a detailed retirement planning analysis to tailor the savings amount to your specific needs and goals.
What should I do if I start saving too late for retirement?
If you find yourself starting to save for retirement later than ideal, don't panic. There are still steps you can take to maximize your retirement savings. Focus on increasing your savings rate as much as possible, consider catching up with contributions to retirement accounts if allowed, and invest in growth-oriented assets to potentially make up for lost time. Additionally, revisiting your retirement goals and adjusting your expectations or lifestyle plans can help ensure you're on the right track.
How do I plan my retirement as a self-employed individual?
As a self-employed individual, planning for retirement requires a proactive approach. Since you likely don't have access to employer-sponsored retirement plans, such as a 401(k), you'll need to establish your own retirement savings strategy. Consider opening a Solo 401(k) or a SEP IRA, which are designed for self-employed individuals. Additionally, focus on maintaining a consistent savings discipline, diversifying your investments, and regularly reviewing and adjusting your retirement plan to align with any changes in your income or goals.
Why are money market funds safe with Moomoo MY?
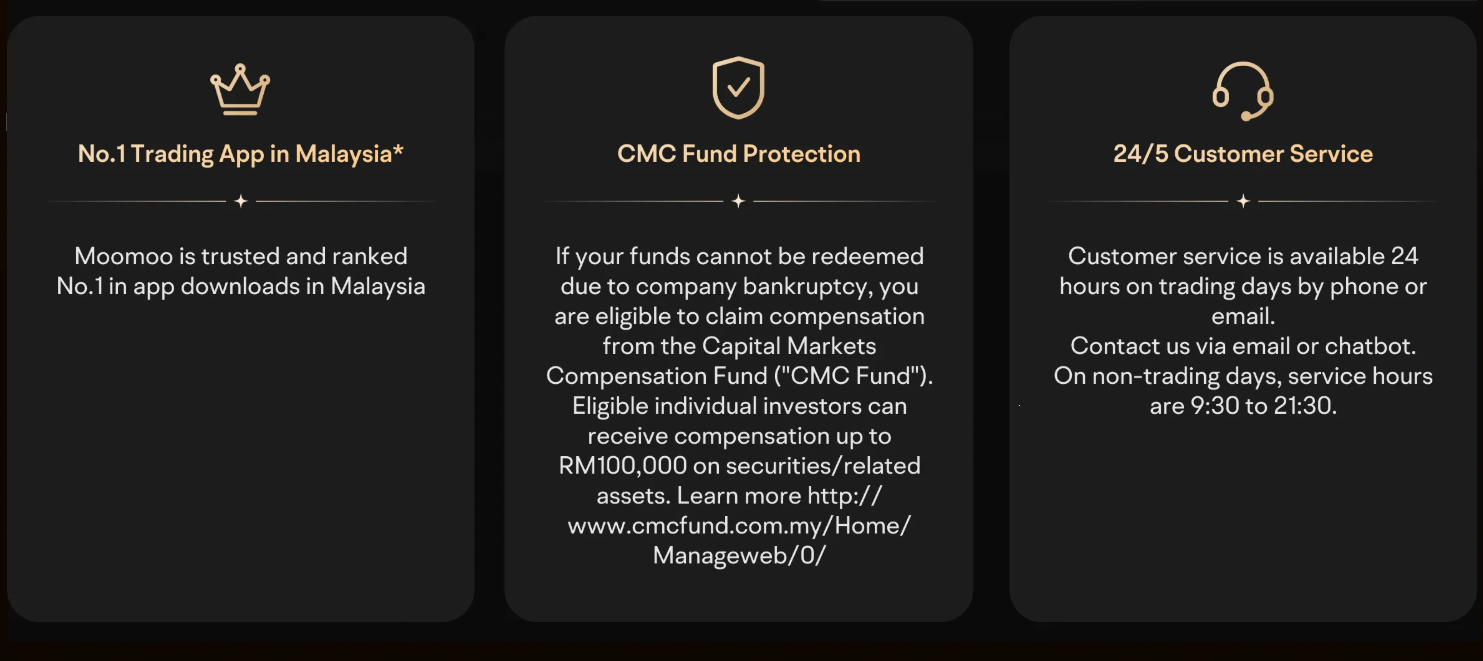
Clients' funds and assets held by Moomoo MY are completely segregated from those of Moomoo MY, ensuring that the platform cannot misappropriate clients' assets without authorization, making money market funds a secure investment choice.
Are the three money market funds offered by Moomoo MY Shariah-compliant?
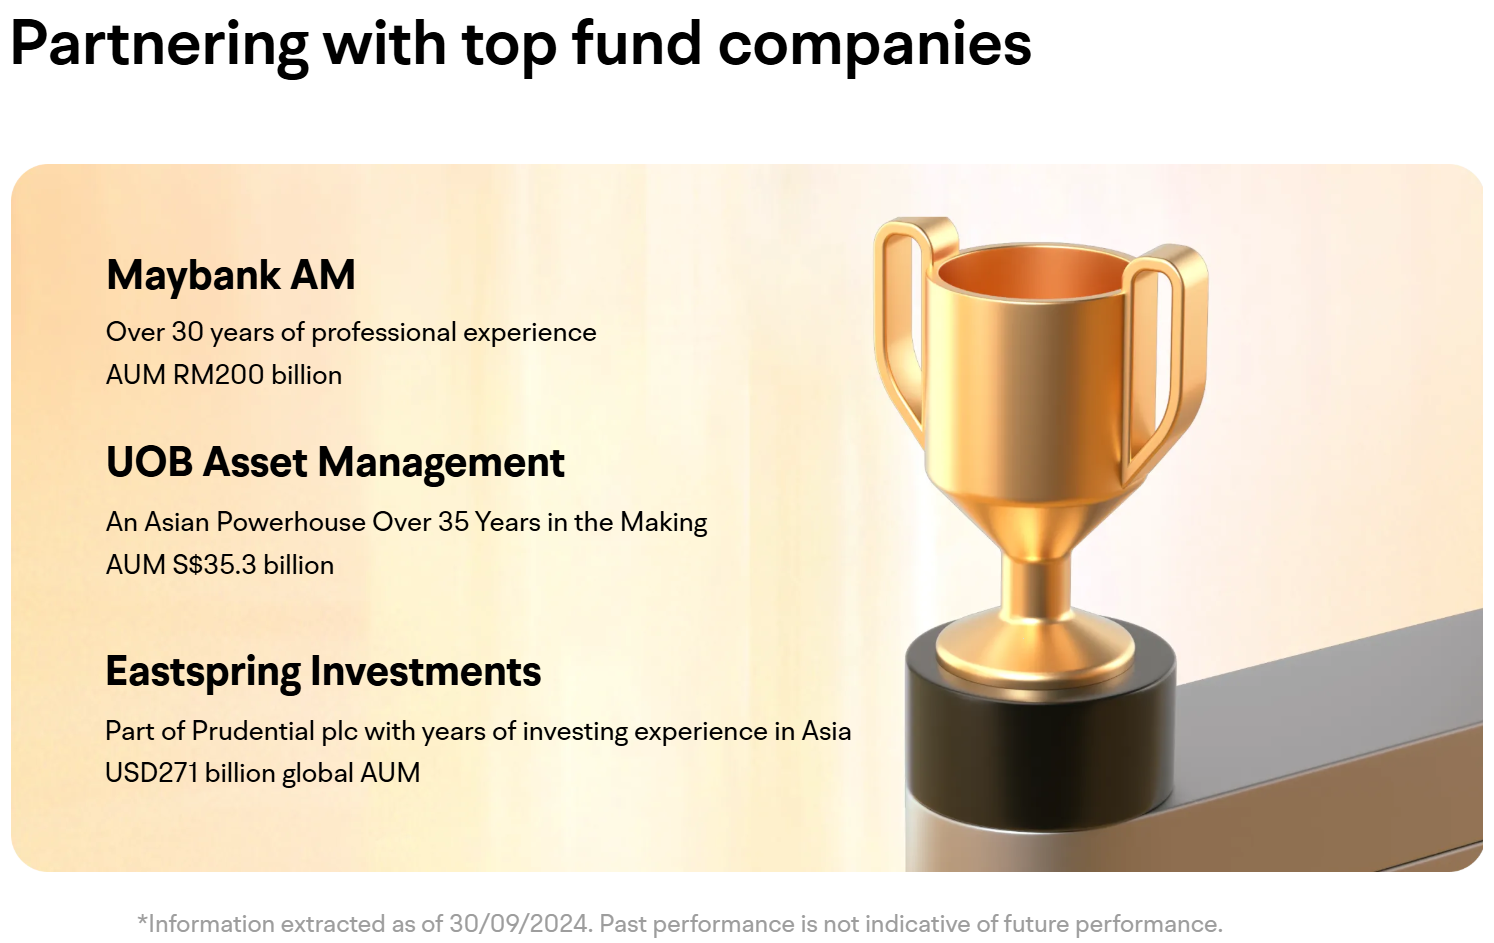
Yes, two of the money market funds offered by Moomoo MY are Shariah-compliant. In particular, the Maybank Retail Money Market - I Fund and the Eastspring Investments Islamic Income - Class R comply with Shariah principles.
Can I use my Cash Plus position to trade stocks or is it redeemable anytime?
Yes, funds holding positions in the MYR money market fund under Cash Plus can be directly used to trade stocks, IPO shares, and other securities. Additionally, the redemption amount can be used to make a withdrawal after the arrival of funds, providing you with flexibility and liquidity when you need it.
Conclusion: Build a Reliable Retirement Plan in Malaysia
Retirement planning in Malaysia in 2026 requires a comprehensive and proactive approach. By understanding the unique aspects of retirement planning in this context and following the easy steps outlined in this guide, you can set yourself on the path to a secure and comfortable retirement.
Building a diversified retirement portfolio is crucial to mitigating risks and maximizing returns. By exploring various investment options, such as blue-chip REITs, dividend stocks etc., you can create a balanced portfolio that aligns with your long-term goals.
It's equally important to avoid common retirement planning mistakes, such as underestimating the cost of retirement, failing to diversify investments, or neglecting to plan for contingencies. By being aware of these pitfalls and taking proactive steps to avoid them, you can increase the likelihood of achieving your retirement objectives.
For those seeking a reliable and innovative solution for their retirement savings, Moomoo Cash Plus offers a compelling option. With its seamless trading platform, zero fees, and the potential for positive returns on idle cash, it provides a convenient and efficient way to manage your retirement funds.
In summary, by taking a holistic and informed approach to retirement planning, you can ensure that you are well-prepared for your future. Start early, stay informed, and make strategic decisions to secure your financial well-being in retirement.
This presentation is for informational and educational use only and is not a recommendation or endorsement of any particular investment or investment strategy. Investment information provided in this content is general in nature, strictly for illustrative purposes, and may not be appropriate for all investors. Read more