CPI Gives No Surprise, 10Y Yield Nears 5%. What's Next?

Weekly Setup | Strong Jobs, Surging Semis — One CPI Print Decides the Rest
The report everyone feared turned out to be the catalyst markets needed. August payrolls beat consensus by a wide margin, pushing September rate-hike odds toward 60% — yet equities barely moved, and surged more than 3%. The logic: when the debate shifts from "will they hike?" to "they almost certainly will," policy uncertainty resolves into direction — and sectors with the hardest industrial thesis stop waiting for rate cuts and start moving on clarity alone. Last week's NFP delivered that moment. This week, Friday's CPI will either lock it in or reopen the debate.
The report everyone feared turned out to be the catalyst markets needed. August payrolls beat consensus by a wide margin, pushing September rate-hike odds toward 60% — yet equities barely flinched. $PHLX Semiconductor Index (.SOX.US)$ surged more than 3%, and the momentum carried into the new week: Korean equities posted sharp gains, with $SK Hynix (000660.KR)$ and $Samsung Electronics (005930.KR)$ staging a forceful return to the fore. The logic: when the debate shifts from "will they hike?" to "they almost certainly will," policy uncertainty resolves into direction — and sectors with the hardest industrial thesis stop waiting for rate cuts and start moving on clarity alone. Last week's NFP delivered that moment. This week, Friday's CPI will either lock it in or reopen the debate.
The Payroll That Didn't Break the Market
August nonfarm payrolls produced the cycle's sharpest upside surprise — 162,000 jobs added, prior months revised higher, and average weekly hours reaching their highest since early 2024. The more important detail was in wages: average hourly earnings slowed to a cycle-low 3.1% year over year, signaling labor supply recovery without reigniting the wage-inflation spiral. That combination — strong hiring, restrained wages — is the one outcome that genuinely complicates the most hawkish read of the data.
The rate story's engine has quietly shifted. Ten-year Treasury yields are no longer driven by growth expectations; since August, diesel and energy prices have been pushing inflation expectations — and break-even rates — higher. Brent crude sits near $97, with OPEC+ holding October output flat and commercial traffic through the Strait of Hormuz at its lowest since May. The year-end trend for yields remains lower, but the path will be uneven until energy stabilizes.
The Fed's Last Chance to Blink
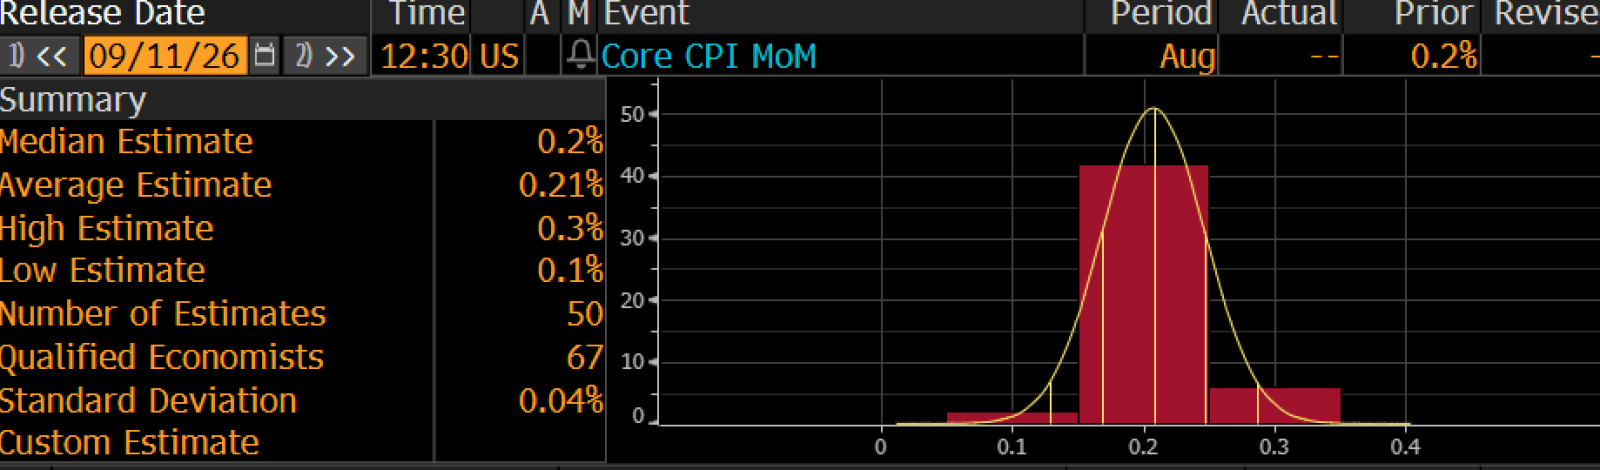
The September 15–16 FOMC is the most closely watched meeting of Chair Warsh's tenure. CME FedWatch pricing currently stands near 58% for a hike — nudged there by Friday's payrolls — and Friday's CPI is the final evidence before the vote. Bloomberg consensus sits around 0.29% month-over-month core, but institutional buy-side positioning has clustered closer to 0.20%–0.23%, a gap that encodes three distinct market regimes and three very different rate paths.

A hot print at 0.25% or above is ironically the most contained scenario: hike odds jump sharply, risk assets sell, but supply-driven tightening cycles historically resolve within six to eight weeks. A cool print below 0.18% could meaningfully reduce hike odds and spark a short-lived rally, capped by the absence of forward guidance. The genuinely dangerous outcome is the 0.20%–0.23% middle band: it leaves the Fed suspended between conviction and caution, and Warsh has already hesitated twice. A third ambiguous pause begins to price a structural discount on Fed independence into long-duration assets.
Storage Leads, Oracle Follows, Apple Surprises

The storage complex moved first. $Micron Technology (MU.US)$ reclaimed $1,000 on a 6% single-session surge last Friday — the second-highest single-day options volume in the stock's history. $SanDisk (SNDK.US)$ , $Western Digital (WDC.US)$ and $Seagate Technology (STX.US)$ followed. $Broadcom (AVGO.US)$ 's earnings confirmed the structural integrity of AI custom silicon demand, even if the print fell short of elevated expectations. The broad $S&P 500 Index (.SPX.US)$ trades near 19x earnings, leaving limited room for multiple expansion without macro support, but the semiconductor and storage complex has found momentum independent of the rate cycle. Notably, Micron, SanDisk, the Korea-focused ETF EWY, and DRAM-linked assets broadly are beginning to clear near-term descending trendlines that capped the group through much of the summer.

Thursday's $Oracle (ORCL.US)$ report is the near-term verdict on AI infrastructure. OCI cloud revenue growth guidance of 58%–64% year over year, if confirmed, validates that enterprise AI compute demand has not peaked and could reignite the storage rally. $Adobe (ADBE.US)$ 's concurrent earnings test whether generative-AI monetization translates into enterprise SaaS pricing power. Wednesday's $Apple (AAPL.US)$ event — the first launch under new CEO John Ternus — introduces the first foldable iPhone and asks whether premium hardware can reopen a meaningful upgrade cycle. The Goldman Sachs Technology Conference on September 10 provides a platform for semiconductor executives to front-run the AI narrative ahead of Anthropic's mid-October IPO target.
Crypto: $80K Is the Line
$Bitcoin (BTC.CC)$ ended the week near $80,000, up roughly 2%, briefly touching $82,200 on dovish Fed commentary before retreating on the NFP print. U.S. spot Bitcoin ETFs attracted approximately $987 million — including a $731 million single-day inflow on September 3, the strongest since January. $Ethereum (ETH.CC)$ held near $2.48K. Key levels: $77,000 near-term support, $80,000 pivot, $82,800 resistance — a clean break higher reopens $85,000–$90,000. Friday's CPI is the direct catalyst.
Your Navigation Guide
Two variables govern the week: Friday's CPI and whether the September hike lands, and Thursday's Oracle earnings and whether the AI infrastructure trade has legs into Q4.
Three scenarios shape the positioning map. A cool CPI print below 0.18% could push hike odds meaningfully lower and open a short-window tech rally; calls on QQQ offer cheap upside participation, though the absence of Fed guidance limits the window. A hot print at 0.25% or above would likely lift hike odds well above current levels, making put protection and defined-risk spreads on small caps the relevant structure — $iShares Russell 2000 ETF (IWM.US)$ 's put/call ratio at 3.57, the highest since April 2024, suggests this scenario is at least partially priced. In the ambiguous middle band, calls on $SPDR Gold ETF (GLD.US)$ and $iShares Bitcoin Trust (IBIT.US)$ offer asymmetric leverage to the credibility unanchoring trade. $CBOE Volatility S&P 500 Index (.VIX.US)$ at 13.80 keeps tail protection cheap.
For $Oracle (ORCL.US)$ , implied move is 12% vs. a three-year average of 9% with IV at the 70th percentile — spread structures over outright long premium. GEX puts walls at $140 and $200; the stock enters at $159.

The Setup
Four sessions this week. Wednesday, Apple tests whether the first foldable iPhone under new CEO John Ternus can reopen a hardware upgrade cycle worth billions. Thursday, Oracle and Adobe answer whether AI spending has peaked or just paused — the Goldman Sachs Technology Conference adds live commentary to the verdict. Friday morning, CPI decides whether Warsh hikes or hesitates for the third time. The week has one question. Only one answer matters.
General ETF disclosure: Before investing in an ETF, you should read both its summary prospectus and its full prospectus, which provide detailed information on the ETF's investment objective, principal investment strategies, risks, costs, and historical performance (if any). You can find prospectuses on the websites of the financial firms that sponsor a particular ETF, as well as through your broker. Investment returns will fluctuate and are subject to market volatility, so that an investor's shares, when redeemed or sold, may be worth more or less than their original cost. ETFs are subject to market volatility and the risks of their underlying securities, which may include the risks associated with investing in smaller companies, international securities, commodities, fixed income, and more. An ETF may trade at a premium or discount to its net asset value (NAV).
Disclaimer: Moomoo Technologies Inc. is providing this content for information and educational use only.Read more


Comments (6)
to post a comment
43
12