

VIX is about to get interesting. Here’s the trade I’m watching.
This trade was inspired by the speakers at the recent Moo Summit. I went back and did my research. Here’s what I found and I have worked out a plan.
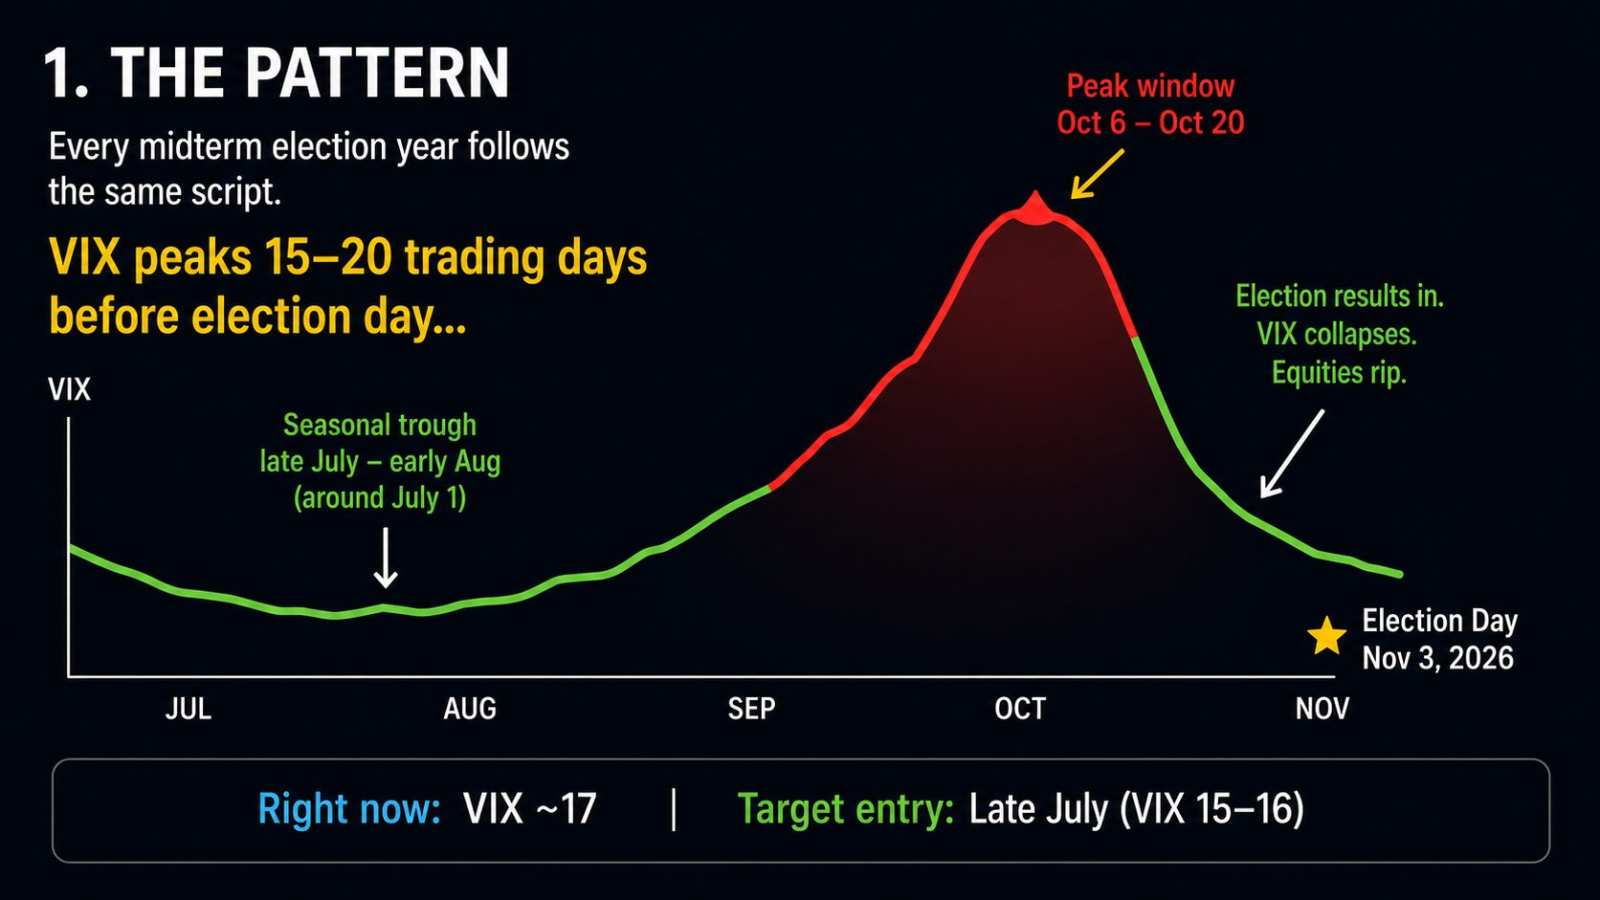
Every midterm election year follows the same script. Markets get nervous heading into November. Volatility spikes. Then the moment results are in, VIX collapses, and equities rip into year-end.
We’re in a midterm year right now. Election day is November 3, 2026.
The Pattern

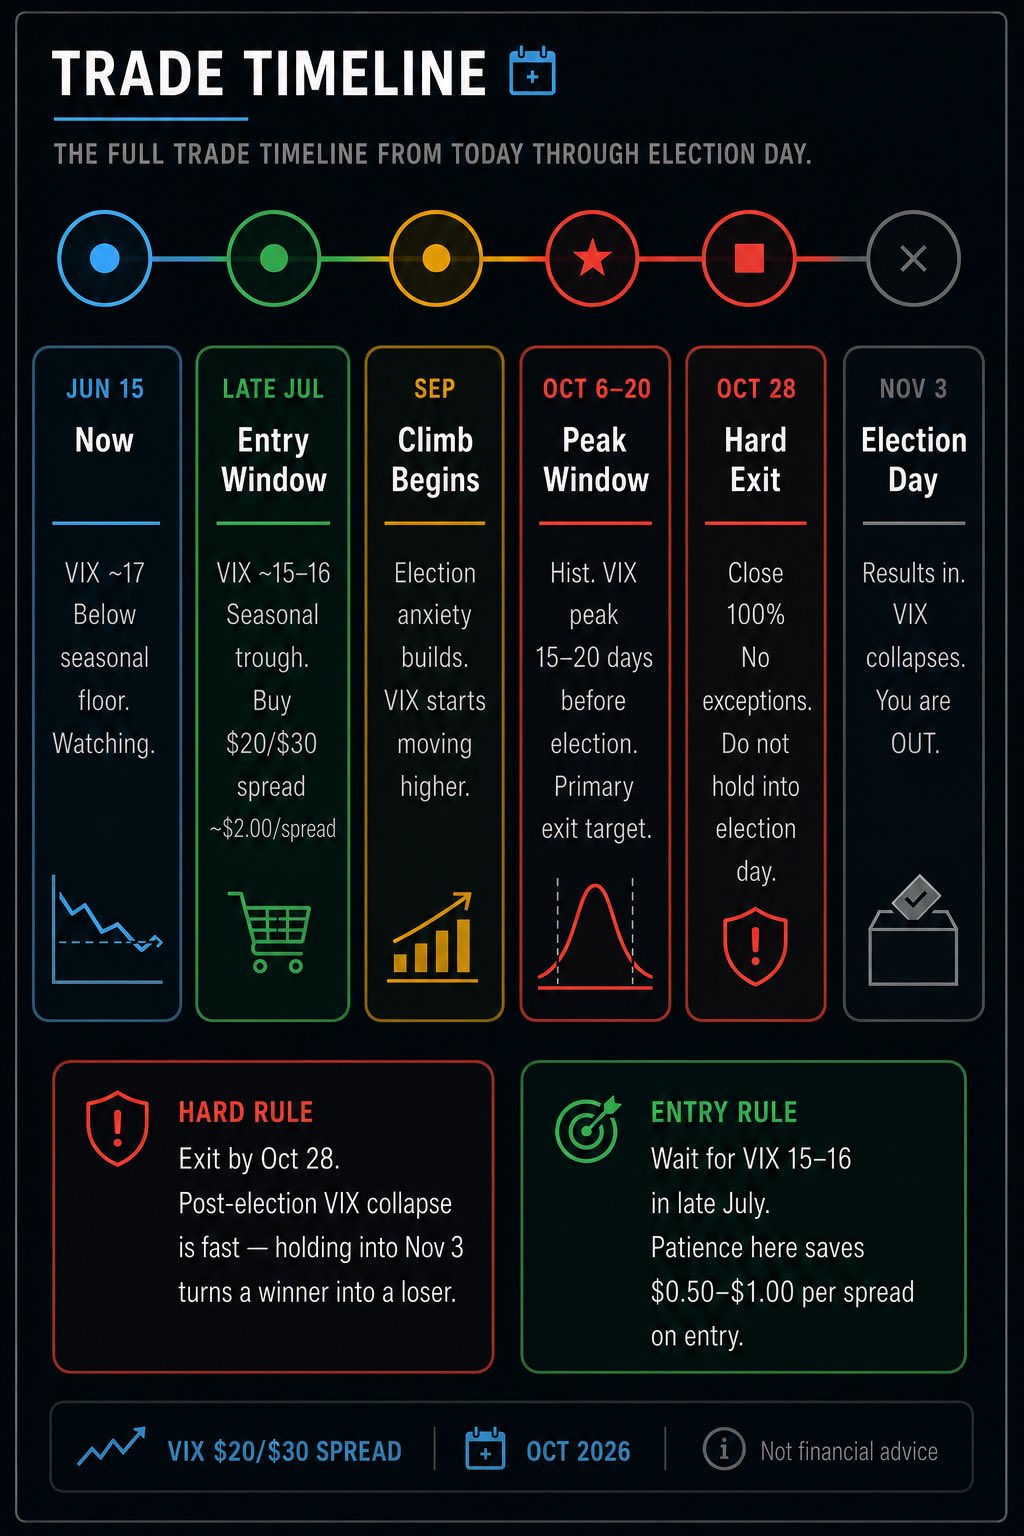
Historically, VIX peaks roughly 15–20 trading days before election day. That’s the October 6–20 window. It’s not random. It’s uncertainty being priced in. Once the uncertainty resolves, volatility sellers flood back and VIX drops fast.
The seasonal trough, the cheapest entry point is typically late July to early August. VIX bottoms around July 1 every year before climbing into the election.
Right now VIX is sitting just below 17. Not at its floor yet.
The Trade

A VIX bull call spread, October 2026 expiry. Buy the $20 call, sell the $30 call.
The strikes aren’t arbitrary. I went back through every midterm election year and looked at where VIX actually peaked in October. Strip out the genuine macro crises (1998 LTCM, 2002 bear market) and the unusually calm years (2006), and the remaining four clean midterm years cluster tightly between 28–34. The average: ~30.5. The $20/$30 spread is designed to max out exactly at the historical median.

In 4 of the last 4 relevant midterm years, VIX hit or came very close to the upper strike. That’s the historical case for this spread over a wider $25/$35 structure.
Why not a naked call? My thesis has a defined ceiling. Paying full premium for unlimited upside I don’t expect to use is poor capital allocation. The spread cuts entry cost significantly, delivers a far better ROI if the trade plays out where history says it should, and caps my maximum loss at premium paid.
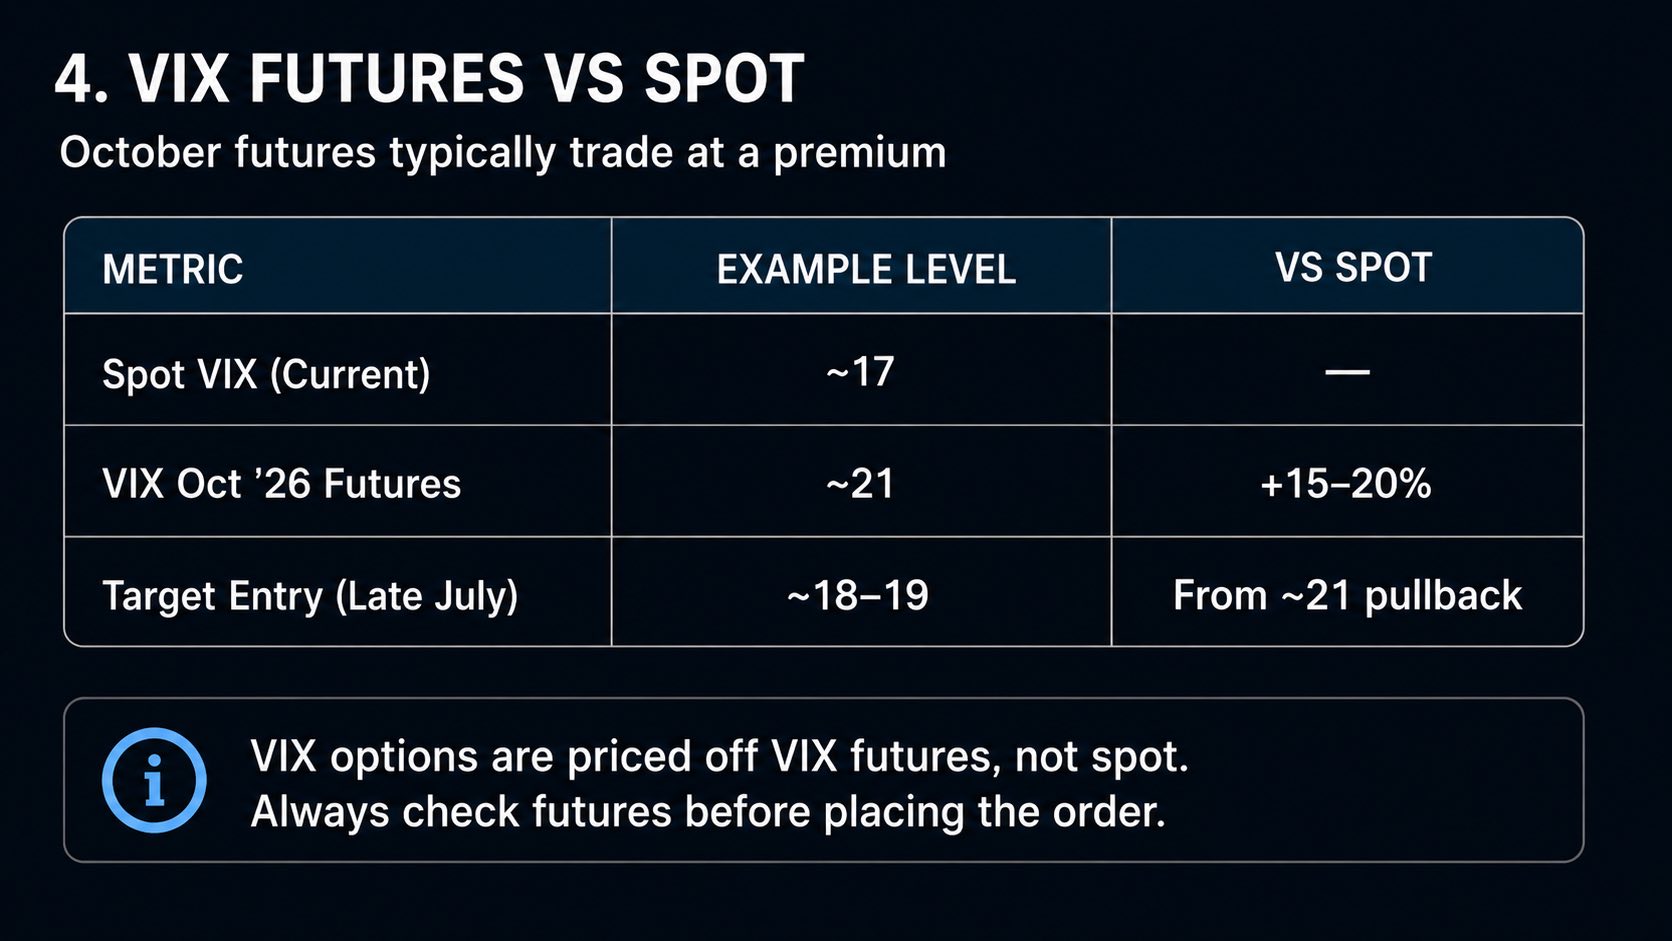
One thing most people miss: VIX options are priced off VIX futures, not spot VIX. October futures already carry a meaningful election premium. They trade roughly 15–20% above spot due to contango and election uncertainty. Always check the futures price before placing the order. The entry is more expensive than spot VIX alone suggests.
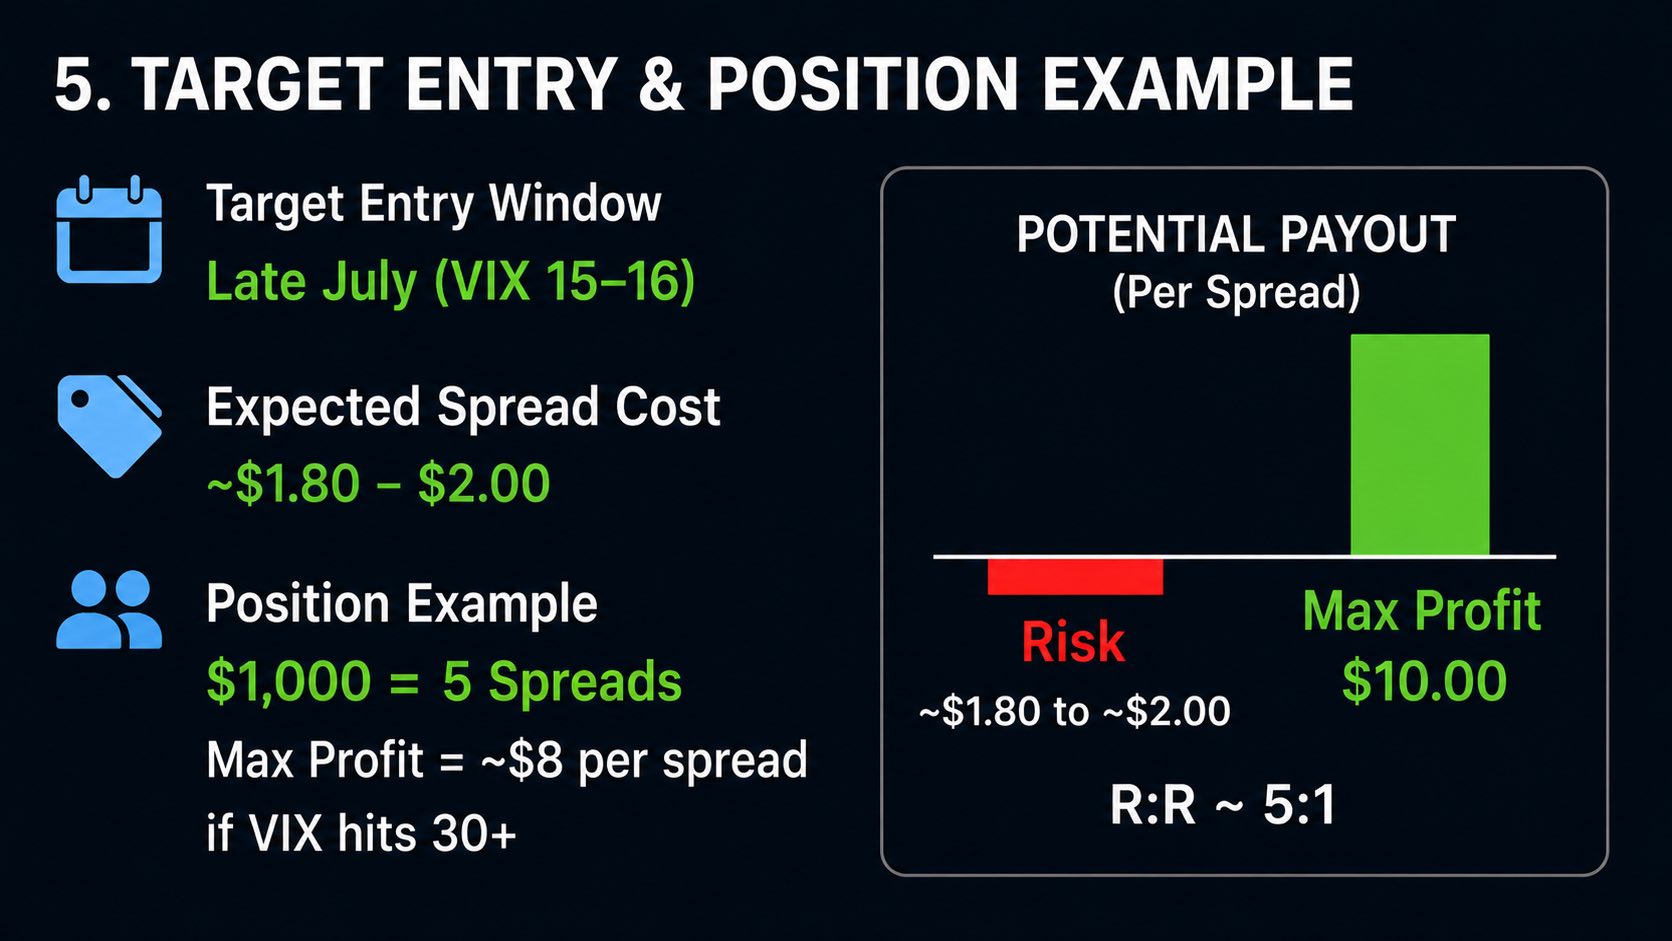
Target entry: late July when VIX seasonally dips to 15–16, pulling October futures from ~21 down to ~18–19. At that point the spread costs roughly $1.80–$2.00. A $1,000 position gets you 5 spreads with a max profit of ~$8 each if VIX hits 30 or above.
The Exit
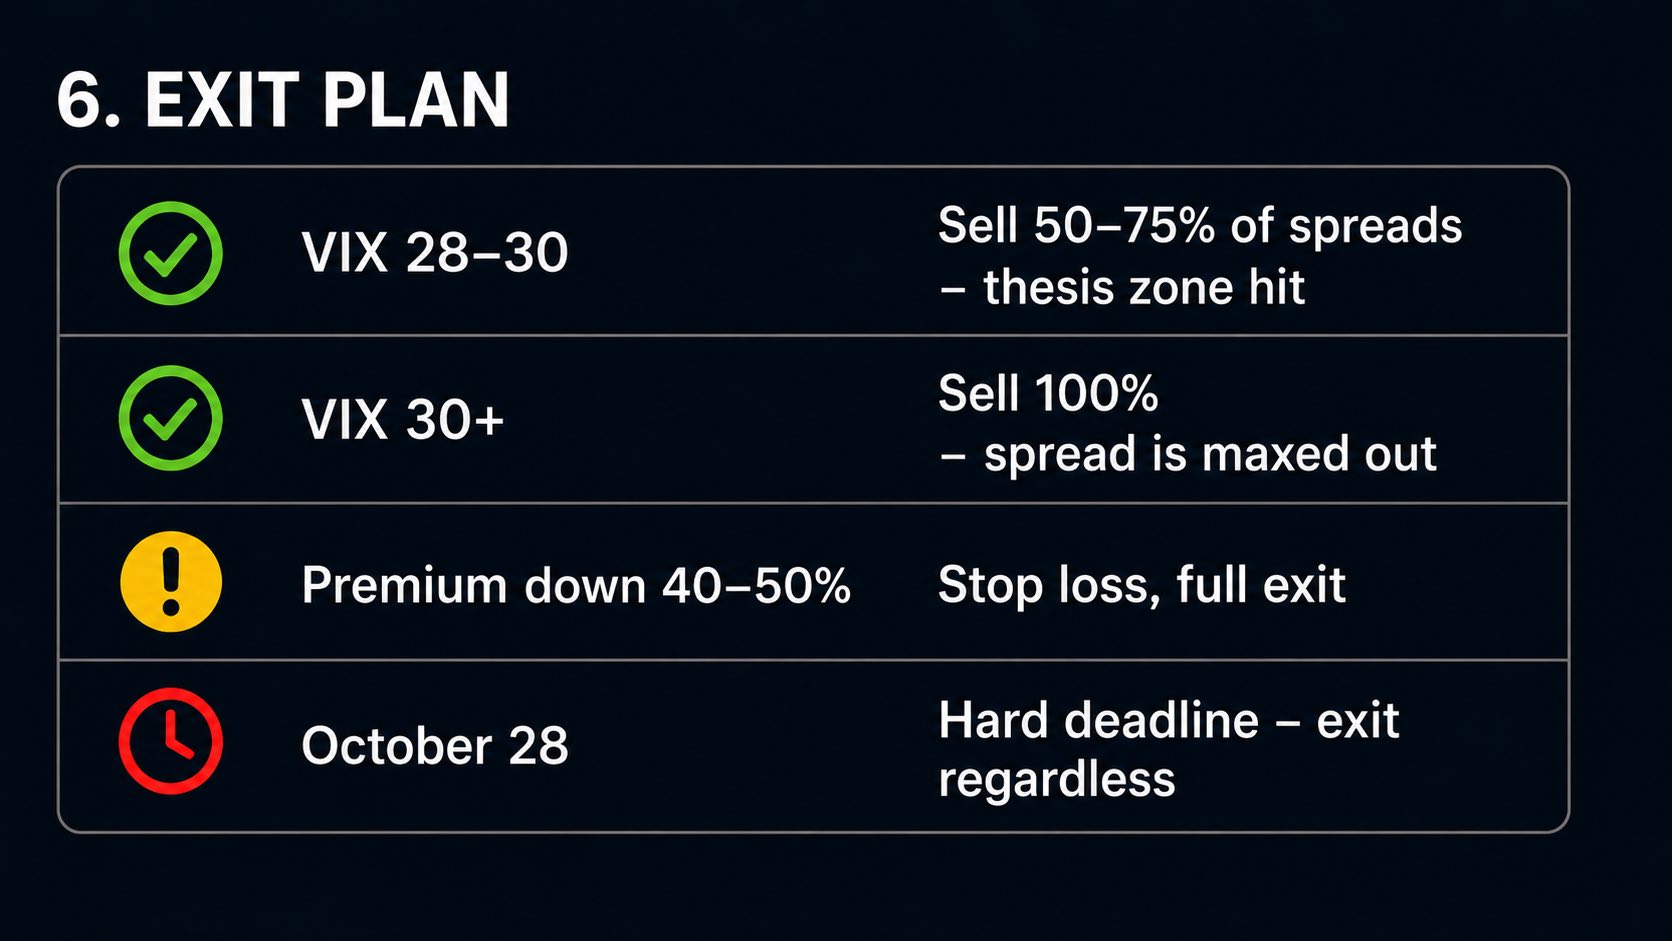
• VIX 28–30: sell 50–75% of spreads. Thesis zone hit, lock in gains
• VIX 30+: sell 100%. Spread is maxed out, no reason to hold
• Premium drops 40–50% from entry: stop loss, full exit
• Hard deadline October 28: close everything regardless
Do not hold through election day. The post-election VIX collapse is fast. That’s how a winning trade becomes a loser.
The Honest Risks
VIX already hit 35 in March this year. That could have been the year’s dislocation event. Meaning October’s spike may be smaller than historical averages. That’s the biggest question mark on this trade.
Calm midterm years also exist. 2006 barely moved. If the bull market stays strong into Q3, the seasonal pattern may not trigger at all.
This is a small, defined-risk position for me. ~$1,000 in premium, maximum loss capped at entry cost. Learning trade, not conviction size.
Decision Point: Late July.
If VIX is back at 15–16 and October futures are reasonably priced, I’ll pull the trigger. If it’s already elevated at 20+, I’ll reduce size or pass entirely.
Saving this post now so you can hold me to it.
Not financial advice. Just sharing my trade ideas for educational purposes. Do your own research. ✌🏼
Disclaimer: Community is offered by Moomoo Technologies Inc. and is for educational purposes only.Read more


Comments (5)
to post a comment
93
18