Stocks Rally. Can Friday's Jobs Report Stir the Market?

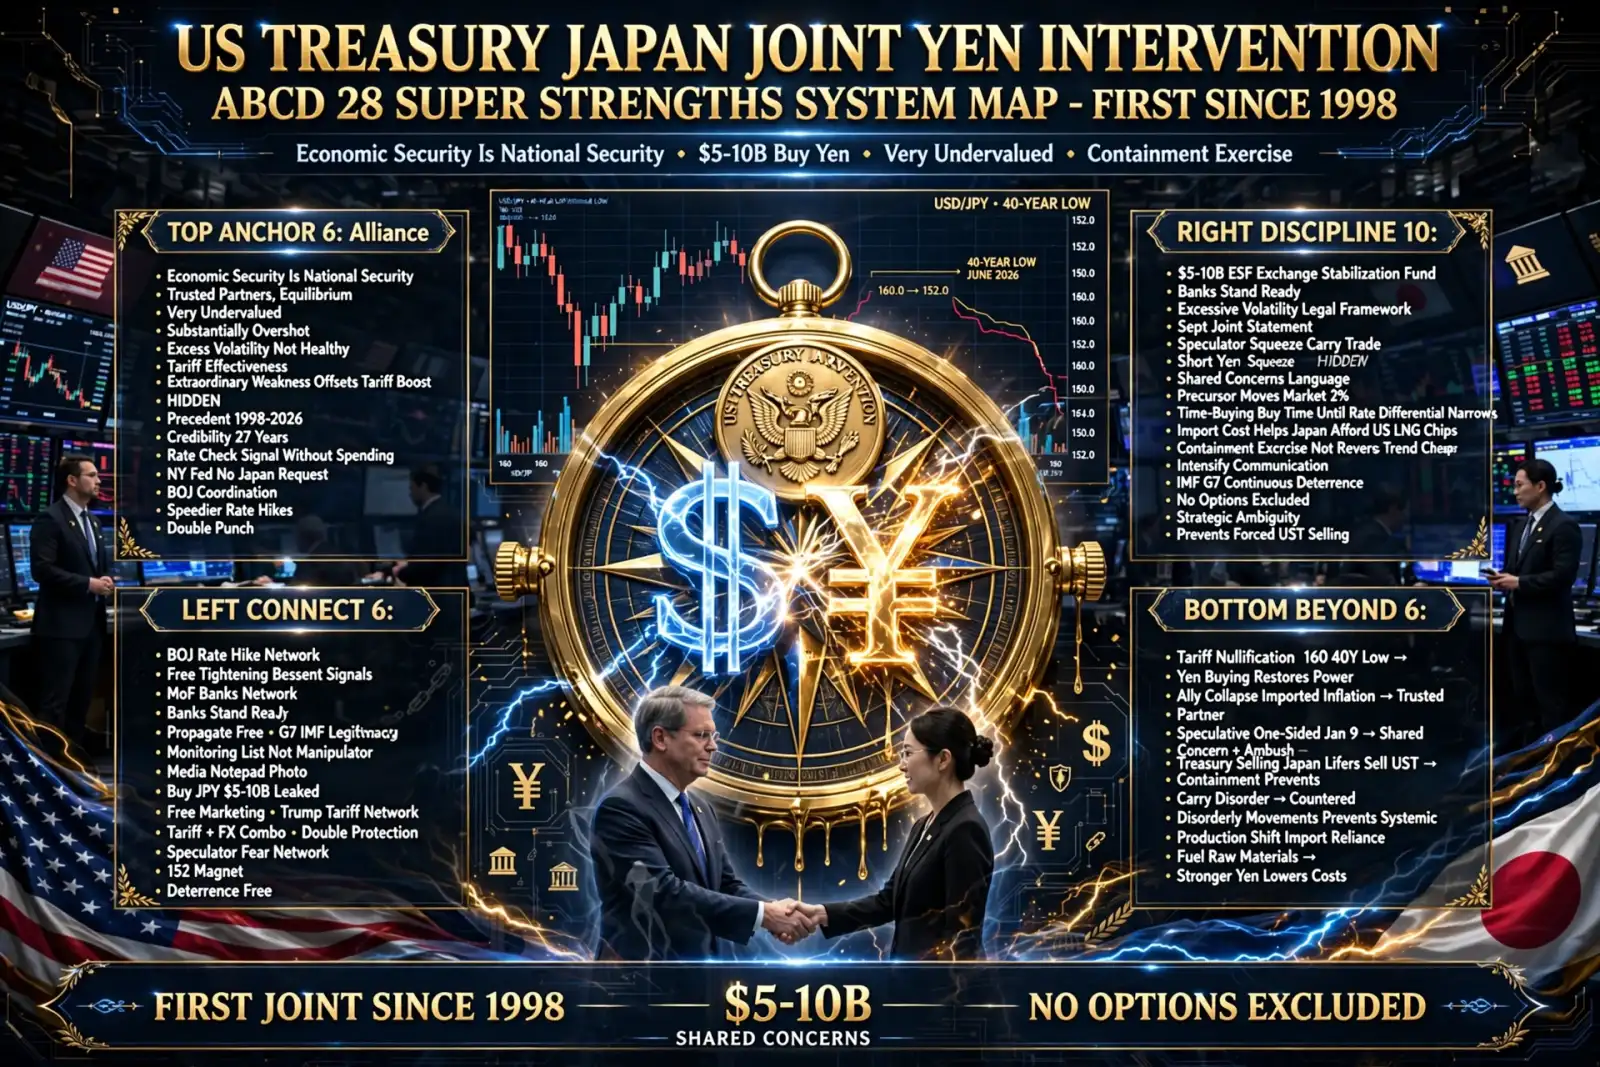
US Treasury Joint Yen Intervention — Jan 2026 — First Since 1998. what next

US Treasury Joint Yen Intervention — Jan 2026 — First Since 1998.
Most see it as Japan buying yen. Wrong.
This time US Treasury bought yen itself — first joint US-Japan yen-buying since 1998.
Context: Yen hit near 40-year low vs dollar, one-sided depreciation Jan 9. Treasury Secretary Scott Bessent said yen "seems very undervalued to me", "substantially overshot equilibrium price", "excess volatility isn't healthy." Notepad photo: "To Do: Buy Japanese Yen $5-10 bil." Treasury informed banks to stand ready. NY Fed did rate checks on behalf of Treasury without Japan request — prelude to intervention. Then joint action — Japan MoF + US Treasury — "countered excessive volatility and disorderly movements."
Trump: US was helping Japan. Bessent: effort may have included billions in support from Washington, "delivers for America's trusted partners. Economic security is national security. And US-Japan alliance is built on both."
Why US does it? Analysts: helps strategic ally + addresses extraordinary weakness that offsets boost from Trump tariffs.
This is Treasury as Market Maker + Alliance Manager.
A - ANCHOR: The Soul That Never Drifts — 6 Strengths
1. Alliance Anchor: Economic Security Is National Security
Bessent: "Delivers for America's trusted partners. Economic security is national security." First joint intervention in 27 years signals US-Japan alliance is not just military but financial. In Asia with China risk, yen collapse = Japan weak = US weak.
2. Equilibrium Anchor: Very Undervalued — Correcting Overshoot
Bessent: yen "very undervalued", "substantially overshot equilibrium price." Treasury anchor is not fixing price, but countering disorderly move. Mandate: intervention should be limited to addressing excessive volatility or disorderly market moves, not to secure competitive edge — Sept joint statement. US defends market function, not manipulation.
3. Tariff Effectiveness Anchor — HIDDEN #1
Analysts: intervention would help US address concerns over extraordinary weakness in yen that offsets boost from Trump's tariffs. If yen falls 20%, 10% tariff is nullified. US buying yen restores tariff leverage for free.
4. Precedent Anchor: 1998 — 2026 — Credibility
Last US-Japan joint yen-buying 1998 during Asian crisis. Repeating it now = credibility weapon. Market knows US will act when one-sided depreciation hits Jan 9 type move.
5. Rate Check Anchor — Signal Without Spending
US led January yen rate checks, eyed joint intervention — New York Fed acted on behalf of Treasury, made without request by Japan MoF. Rate check costs zero, but sends speculators into frenzy, driving yen back toward 152 as traders bet on first joint intervention in decades. Tacit approval as weapon.
6. BOJ Coordination Anchor
Katayama: "Going forward, as official responsible for currency policy, I would like to respond in close coordination with monetary policy." Bessent called for speedier BOJ rate hikes to arrest yen falls. Joint FX + monetary policy = double punch.
D - DISCIPLINE: Why It Is Unkillable — 10 Strengths
7. Coordinated Intervention Discipline — $5-10B Noted
Reuters photo: "Buy Japanese Yen $5-10 bil." Treasury informed number of banks that it might intervene and should stand ready for future action. US has ESF Exchange Stabilization Fund — can deploy instantly without Congress.
8. Excessive Volatility Discipline — Legal Framework
MoF statement: Friday's yen-buying intervention with US Treasury Dept "countered excessive volatility and disorderly movements in Japanese yen in recent months." Fits G7, IMF rules — justified to counter disorderly moves. While Japan is on Treasury's monitoring list, doesn't meet all criteria to be labelled manipulator. Sept joint statement gives room to act.
9. Speculator Squeeze Discipline — HIDDEN #2
Japan shifting to ambush intervention tactics against yen speculators. Prospect of further US-Japan interventions, BOJ rate rises could keep yen supported, could discourage speculators from betting on weaker yen — MUFG. When US joins, short yen carry trade — borrow yen at 0.5%, buy dollar at 5% — faces central bank with infinite dollars. Squeeze = forced covering.
10. Shared Concerns Language Discipline
Emergency meeting Jan 12 — Bessent + Katayama — rare joint statement expressing "shared concerns" over yen's "one-sided depreciation" — traditionally precursor to market intervention. Language itself moves market 2% without spending.
11. Time-Buying Discipline
Goldman Sachs: intervention primarily as way for Japan to buy time until pressures ease — interest-rate differential narrowing, stronger domestic growth. US intervention buys 3-6 months for BOJ to hike.
12. Import Cost Discipline — Helps Japan, Helps US Supply Chain
Yen weakness problematic, Japanese firms shifted production overseas and economy heavily reliant on imports for goods ranging from fuel and raw materials to machinery parts. Weak yen = imported inflation for Japan = Japan cannot buy US LNG, chips. Stronger yen = Japan can afford US exports.
13. Containment Exercise Discipline
Barrons: Massive Yen Support by US is Just a Containment Exercise. Not trying to reverse trend, but contain disorderly overshoot. Cheaper, more credible than defending fixed level.
14. Bilateral Intensification Discipline
Japan and US agreed to intensify communication on exchange rates after IMF/G7 meetings. Katayama and Bessent last met in January, when verbal warnings propped yen as markets braced for chance of intervention. Continuous communication = continuous deterrence.
15. No Options Excluded Discipline
Katayama: joint statement last September "was extremely significant and included language on intervention. It does not specify whether such intervention would be coordinated or not, so we consider that no options are excluded." Strategic ambiguity = speculators cannot price risk.
16. Market Function Discipline
Treasury Yields, Dollar Fall as Talks — threat of further joint interventions could keep yen supported. US Treasury action stabilizes Treasury market itself — disorderly yen fall forces Japan lifers to sell US Treasuries to hedge.
B - BEYOND: Pain Translation — 6 Strengths
17. Tariff Nullification Pain → Yen Buying Restores Tariff Power
Pain: Yen falls to 160, 40-year low, US tariffs ineffective. Translation: US buys yen, yen strengthens, Japanese goods price up in US, tariff + FX = double protection for US manufacturing.
18. Ally Collapse Pain → Trusted Partner Delivery
Pain: Japan faces imported inflation, political instability, Takaichi strong policies at risk. Translation: Trump says US helping Japan, Bessent delivers billions — alliance built on both economic + national security.
19. Speculative One-Sided Pain → Shared Concern + Ambush
Pain: One-sided depreciation seen Jan 9 — momentum funds pile short yen. Translation: US rate checks without Japan request + banks told stand ready + $5-10B buy — ambush tactics — one-sided becomes two-sided risk.
20. Treasury Selling Pain → Containment Prevents Forced Selling
Pain: Yen too weak → Japan insurers sell US Treasuries to cover FX losses → US yields spike. Translation: Containing yen disorder prevents forced UST selling — helps US Treasury market.
21. Carry Trade Disorder Pain → Disorderly Movements Countered
Pain: Disorderly yen movements cause global risk-off, carry unwind 2024-style. Translation: Coordinated foreign-exchange actions countered disorderly yen movements — prevents systemic shock.
22. Japan Production Shift Pain → Import Reliance Managed
Pain: Far more often MoF sold yen to prevent rise hurting export economy, but now yen weakness problematic because firms shifted overseas, reliant on imports fuel, raw materials, machinery parts. Translation: Stronger yen lowers import costs, supports Japan consumption, which buys US goods.
C - CONNECT: Making World Work For It Free — 6 Strengths
23. BOJ Rate Hike Network — Free Tightening
Bessent signaled need for further BOJ rate hikes while staying mum on latest intervention — BOJ hiking helps yen for free, US doesn't spend.
24. Japanese MoF + Banks Network — Banks Stand Ready
Treasury informed number of banks to stand ready — private banks propagate intervention, amplify signal for free.
25. G7 + IMF Network — Legitimacy Free
Framework: any intervention should be limited to addressing excessive volatility or disorderly moves — US gets G7 cover, not accused of manipulation.
26. Media + Notepad Photo Network — $0 Marketing
Reuters photo of Bessent notepad "Buy Japanese Yen $5-10 bil" — leaked photo does more work than $10B — market front-runs Treasury for free.
27. Trump Tariff Network — Tariff + FX Combo
Aside from helping ally, intervention helps US address concerns over extraordinary weakness that offsets boost from Trump tariffs — tariffs and FX work together, no extra cost.
28. Speculator Fear Network — 152 Magnet
Verbal warnings after Bessent-Katayama talks propped yen as markets braced for chance of intervention — fear of joint action keeps yen supported, discourages betting on weaker yen — MUFG — deterrence is free.
System Conclusion
Japan alone buying yen = expensive, limited reserves.
US Treasury buying yen = strategic, cheap, alliance multiplier.
A creates belief — Economic security is national security — very undervalued — shared concerns.
D makes belief industrial — $5-10B ESF, rate checks without request, banks stand ready, no options excluded, excessive volatility legal justification, ambush tactics, time-buying until BOJ hikes — hidden disciplines.
B makes belief purchasable — Turns tariff nullification, ally collapse, speculative one-sided, Treasury selling, carry unwind into containment exercise.
C makes purchase into empire — BOJ hikes for free, banks propagate for free, notepad photo markets for free, G7 legitimacy for free, speculator fear keeps yen at 152 for free.
Explicit superpower wins this week's yen bounce.
Hidden superpower — ESF + joint statement + rate checks + notepad photo + BOJ coordination — wins next 6 months of FX deterrence war.
Storms open the path. Currents hold the fort.
Japan defends price. US defends alliance.

Post-Intervention USD/JPY Target Range: 148–155
Falsification Threshold: If USD/JPY breaches 160 again within 3 months without renewed U.S. action, the "U.S. Treasury as market maker" thesis is invalidated.
However, this threshold is not unthinkable. Several scenarios could conspire to break the current equilibrium, and their likelihoods are high enough to warrant active vigilance.
The most immediate danger is that the intervention’s success sows the seeds of its own demise. If speculators come to believe that 152 has become an ironclad ceiling backed by infinite Treasury firepower, they will rebuild carry trades with a vengeance, confident that the risk is capped — only to test that ceiling aggressively. This carry-trade revival carries a medium-to-high probability (35–40%), and it is the scenario where the Treasury’s credibility is directly challenged by market forces. Should this happen, even a second round of U.S. intervention would likely see diminishing returns, as traders learn to “fade the Treasury.”
Nearly as threatening is the possibility that the Bank of Japan fails to deliver the rate hikes that the intervention bought time for. If Governor Katayama steps back under domestic pressure and delivers only a token increase — or none at all — the interest rate differential that drives the yen’s weakness will remain wide, and the three-month window purchased by Bessent’s billions will close without result. This is a medium-probability risk (30–35%) and one that dovetails dangerously with the carry trade scenario: a timid BOJ gives speculators the green light to reload short yen positions.
On the political front, the entire framework rests on the continuity of Treasury Secretary Bessent’s conviction that a strong dollar is not always a strong America. A sudden policy reversal from President Trump — who may find the narrative of a dominant dollar more aligned with “America First” — would pull the rug from under the intervention logic overnight. This is a lower-probability event (15–20%), but its impact would be immediate and absolute: the joint framework would shatter, and the yen would resume its one-sided decline with no safety net.
There are also two "external shock" paths that could overwhelm the Treasury’s ability to manage the pair. The first is a stress event in the U.S. Treasury market itself. If inflation proves sticky or the fiscal deficit widens unexpectedly, rising yields could push the dollar higher regardless of yen-specific fundamentals, forcing the Treasury into a painful choice between stabilising the bond market and defending the yen. This scenario carries a moderate probability (25–30%). The second is the entry of China into a competitive devaluation cycle to offset U.S. tariffs. A regional wave of Asian currency weakness would drag the yen down with it, and no unilateral U.S. intervention could easily counter that tide. This is a lower-probability scenario (20–25%), but one with systemic implications that extend far beyond USD/JPY.
A more subtle but equally corrosive risk is one of scale. If the actual U.S. intervention amounts to only $5 billion — half the lower bound suggested by Bessent’s own notepad — the market will quickly conclude that the Treasury’s commitment is more rhetorical than real. The “market maker” narrative would lose its anchor, and speculative pressure would resume. This risk sits at a moderate level (25–30%).
Finally, a direct falsification event could arise if the next episode of yen weakness is met by Japan acting alone. Should political considerations keep Washington on the sidelines, the joint front would be exposed as a one-time gesture rather than a structural pillar of the alliance. That alone would be sufficient to invalidate the core thesis, and it carries a moderate-to-low probability (20–25%).
Taken together, any single risk has a probability mostly in the 20–35% range — manageable, but not dismissible. The real danger lies in compounding. If the BOJ under-delivers on rates while carry trades simultaneously rebuild, the combined probability of a return to 160 within three months rises materially. In that sense, the falsification threshold is not a single trigger but a web of interconnected vulnerabilities. Over the next quarter, four signals will serve as the pulse of this thesis: the BOJ’s actual rate decision, Secretary Bessent’s continued willingness to label the yen as “very undervalued,” the U.S.-Japan 10-year yield spread, and the net speculative short positioning in yen futures. Any sustained deterioration in these indicators would signal that the Treasury’s hidden superpower — the fusion of alliance discipline and market-making authority — is approaching its limits.
The U.S. Treasury’s Yen Intervention: A Market Maker’s Manifesto
Most observers saw the January 2026 yen surge and concluded that Japan was once again defending its currency alone. They were wrong. For the first time since the 1998 Asian financial crisis, the United States Treasury did not merely give Tokyo its blessing — it bought yen itself. The intervention, which pushed the dollar from around 160 yen back toward the 152–155 range, was not a routine currency operation. It was a declaration that the Treasury now sees itself as a market maker and an alliance manager, using its balance sheet to defend not a price level, but an entire architecture of economic security.
The facts are striking in their rarity. Treasury Secretary Scott Bessent’s own notepad, captured by a Reuters photographer, revealed a to-do item: “Buy Japanese Yen $5-10 bil.” The New York Fed, acting on behalf of the Treasury, conducted rate checks without any request from Japan — a classic prelude to intervention. The legal machinery was the Exchange Stabilization Fund, a Depression-era tool that allows the Treasury to deploy billions instantly without Congressional approval. Bessent’s public rationale was equally direct: the yen “seems very undervalued,” had “substantially overshot its equilibrium price,” and “excess volatility isn’t healthy.” A rare joint statement with Japan’s Finance Ministry followed, expressing “shared concerns” over the yen’s “one-sided depreciation” — language that has historically served as the final warning before action.
Why would an America First administration spend its own ammunition to prop up a foreign currency? The answer lies in three interlocking imperatives that transform this intervention from an act of charity into a coldly calculated act of self-interest.
The first is alliance economics. When Bessent declared that “economic security is national security” and that the U.S. “delivers for America’s trusted partners,” he was redrawing the boundaries of the U.S.-Japan alliance. In a region where China’s economic and military weight continues to grow, a collapsing yen is not just Tokyo’s problem. A Japan weakened by imported inflation and capital flight is a diminished strategic partner. By intervening jointly, Washington signaled that the alliance is now explicitly financial — a commitment that extends from the South China Sea to the currency market.
The second imperative is tariff effectiveness. The Trump administration’s tariff wall depends on making foreign goods more expensive for American consumers. But if the yen falls by 20%, a 10% tariff on Japanese imports is entirely neutralized — the currency does the work of undercutting the policy. By buying yen and strengthening it, the Treasury restored the bite of its own tariffs without spending a cent on new trade enforcement. Analysts noted that the intervention directly addresses concerns that extraordinary yen weakness was offsetting the boost from Trump’s levies. It is a perfect circle: tariffs protect American manufacturing, and currency intervention protects the tariffs.
The third imperative is the defense of the U.S. Treasury market itself. When the yen falls too far and too fast, Japanese life insurers and pension funds — among the largest foreign holders of American government debt — are forced to sell Treasuries to hedge their currency exposure. That selling pressure drives up U.S. yields at precisely the moment Washington wants them stable. By capping the disorderly depreciation of the yen, the Treasury was also capping a potential disorderly sell-off in its own bond market. It was, in effect, a two-front defense executed with a single instrument.
This triple logic — ally, tariff, bond market — elevates the Treasury from a passive regulator to an active market maker. But the true depth of the strategy only becomes visible when examined through the PRISMA framework.
The Anchor of the entire operation is the conviction that economic security is national security and that markets function best when excessive volatility is countered. Bessent anchored the intervention not in a specific exchange rate but in the concept of equilibrium: the yen was “very undervalued” and had overshot. This gave the Treasury the flexibility to act without committing to defend a particular line in the sand — a far more sustainable posture. The 1998 precedent provided a credibility anchor, reminding markets that the U.S. has done this before and will do it again. Even the rate checks, carried out without a Japanese request, served as an anchor — a cost-free signal that the Treasury was watching and willing.
The Discipline behind the operation is what makes it unkillable. The ESF provides an independent war chest, freeing the Treasury from Congressional gridlock. The legal justification — countering “excessive volatility and disorderly movements” — fits neatly within G7 and IMF frameworks, providing cover against accusations of manipulation. The Treasury informed private banks to stand ready, turning the financial system itself into an amplifier of its intent. The language of the joint statement — “shared concerns” — was a precision tool, moving markets 2% without a single dollar spent. Ambush tactics, strategic ambiguity about future options, and the buying of time for the Bank of Japan to raise rates all point to a meticulously disciplined operation. It was not designed to reverse the yen’s long-term trend; it was a containment exercise, cheaper and more credible than defending a fixed level. And crucially, it bought three to six months for the Bank of Japan to narrow the interest rate differential that is the fundamental driver of yen weakness.
The Beyond dimension reveals how pain was translated into leverage. The pain of tariff nullification — a 160 yen exchange rate rendering a 10% tariff meaningless — was converted directly into a rationale for buying yen. The pain of a strategic ally under economic siege became a narrative of “delivering for trusted partners.” The one-sided speculative assault of January 9 was met with an ambush that turned a one-way bet into a two-sided risk. The pain of potential forced Treasury selling by Japanese institutions was preemptively neutralized. The disorderly carry trade unwinds that had traumatized markets in 2024 were headed off. And Japan’s newfound vulnerability to import costs — a consequence of decades of offshoring production — was recognized and addressed, because a Japan that cannot afford imported fuel and raw materials cannot afford to buy American liquefied natural gas or semiconductors either.
Finally, the Connect dimension shows how the Treasury made the world do its work for free. The Bank of Japan’s rate hikes, urged on by Bessent, strengthened the yen without a single dollar of U.S. spending. The private banks informed of the intervention propagated the signal through the market at zero cost. The leaked notepad photo did more to shape expectations than the billions it referenced. The G7 and IMF frameworks provided instant legitimacy. Trump’s tariff architecture, initially threatened by the weak yen, was instead reinforced by the intervention, creating a tariff-currency composite shield. And the fear of further joint action — stoked by deliberate ambiguity — kept speculative short positions cautious, maintaining the yen’s support around 152 without continuous expenditure.
The system conclusion is stark. Japan alone buying yen is expensive and depletes finite reserves. The U.S. Treasury buying yen is strategic, cheap, and carries an alliance multiplier. The explicit superpower — the $5-10 billion deployed and the coordinated statements — won the initial bounce from 160 to 152. But the hidden superpower — the ESF’s independence, the unrequested rate checks, the leaked notepad, the legal architecture of shared G7 concern, the time bought for monetary policy adjustment — is what will win the next six months of the foreign exchange deterrence war. Japan may defend a price, but the United States is now defending the alliance itself.
The post-intervention target range for the dollar-yen pair lies between 148 and 155. The thesis that the U.S. Treasury has become a true market maker will be falsified if the dollar breaches 160 again within three months without renewed American action. That risk, while not the base case, is far from unthinkable. A timid Bank of Japan that fails to deliver rate hikes, a resurgence of carry trades emboldened by the perceived 152 ceiling, or a political reversal by a president who decides a strong dollar better fits the America First narrative — any of these could unravel the framework. For now, however, the Treasury has demonstrated that it possesses a new tool, and that it is willing to use it not to manipulate markets, but to shape them in the service of a broader strategic design.
$USD/JPY (USDJPY.FX)$ $JPY/USD (JPYUSD.FX)$ $iShares MSCI Japan ETF (EWJ.US)$ $iShares MSCI Japan Value ETF (EWJV.US)$ $iShares Currency Hedged MSCI Japan ETF (HEWJ.US)$ $WisdomTree Japan Hedged Equity ETF (DXJ.US)$ $iShares Currency Hedged MSCI Japan ETF (HEWJ.US)$ $Franklin FTSE Japan ETF (FLJP.US)$ $Toyota Motor (TM.US)$ $Honda Motor (HMC.US)$ $Sony Group (6758.JP)$ $Mitsubishi UFJ Financial Group (MUFG.US)$ $Sumitomo Mitsui Financial (SMFG.US)$ $Sumitomo Mitsui Financial (SMFG.US)$ $SoftBank Group (ADR) (SFTBY.US)$ $Nintendo (ADR) (NTDOY.US)$ $iShares 20+ Year Treasury Bond ETF (TLT.US)$ $Direxion Daily 20+ Year Treasury Bull 3X Shares ETF (TMF.US)$ $iShares 7-10 Year Treasury Bond ETF (IEF.US)$ $Apple (AAPL.US)$ $Tesla (TSLA.US)$ $Walmart (WMT.US)$ $Costco (COST.US)$ $Novo-Nordisk A/S (NVO.US)$ $SPDR S&P 500 ETF (SPY.US)$ $Invesco QQQ Trust (QQQ.US)$
Disclaimer: Community is offered by Moomoo Technologies Inc. and is for educational purposes only.Read more

Comment (1)
to post a comment
2
4