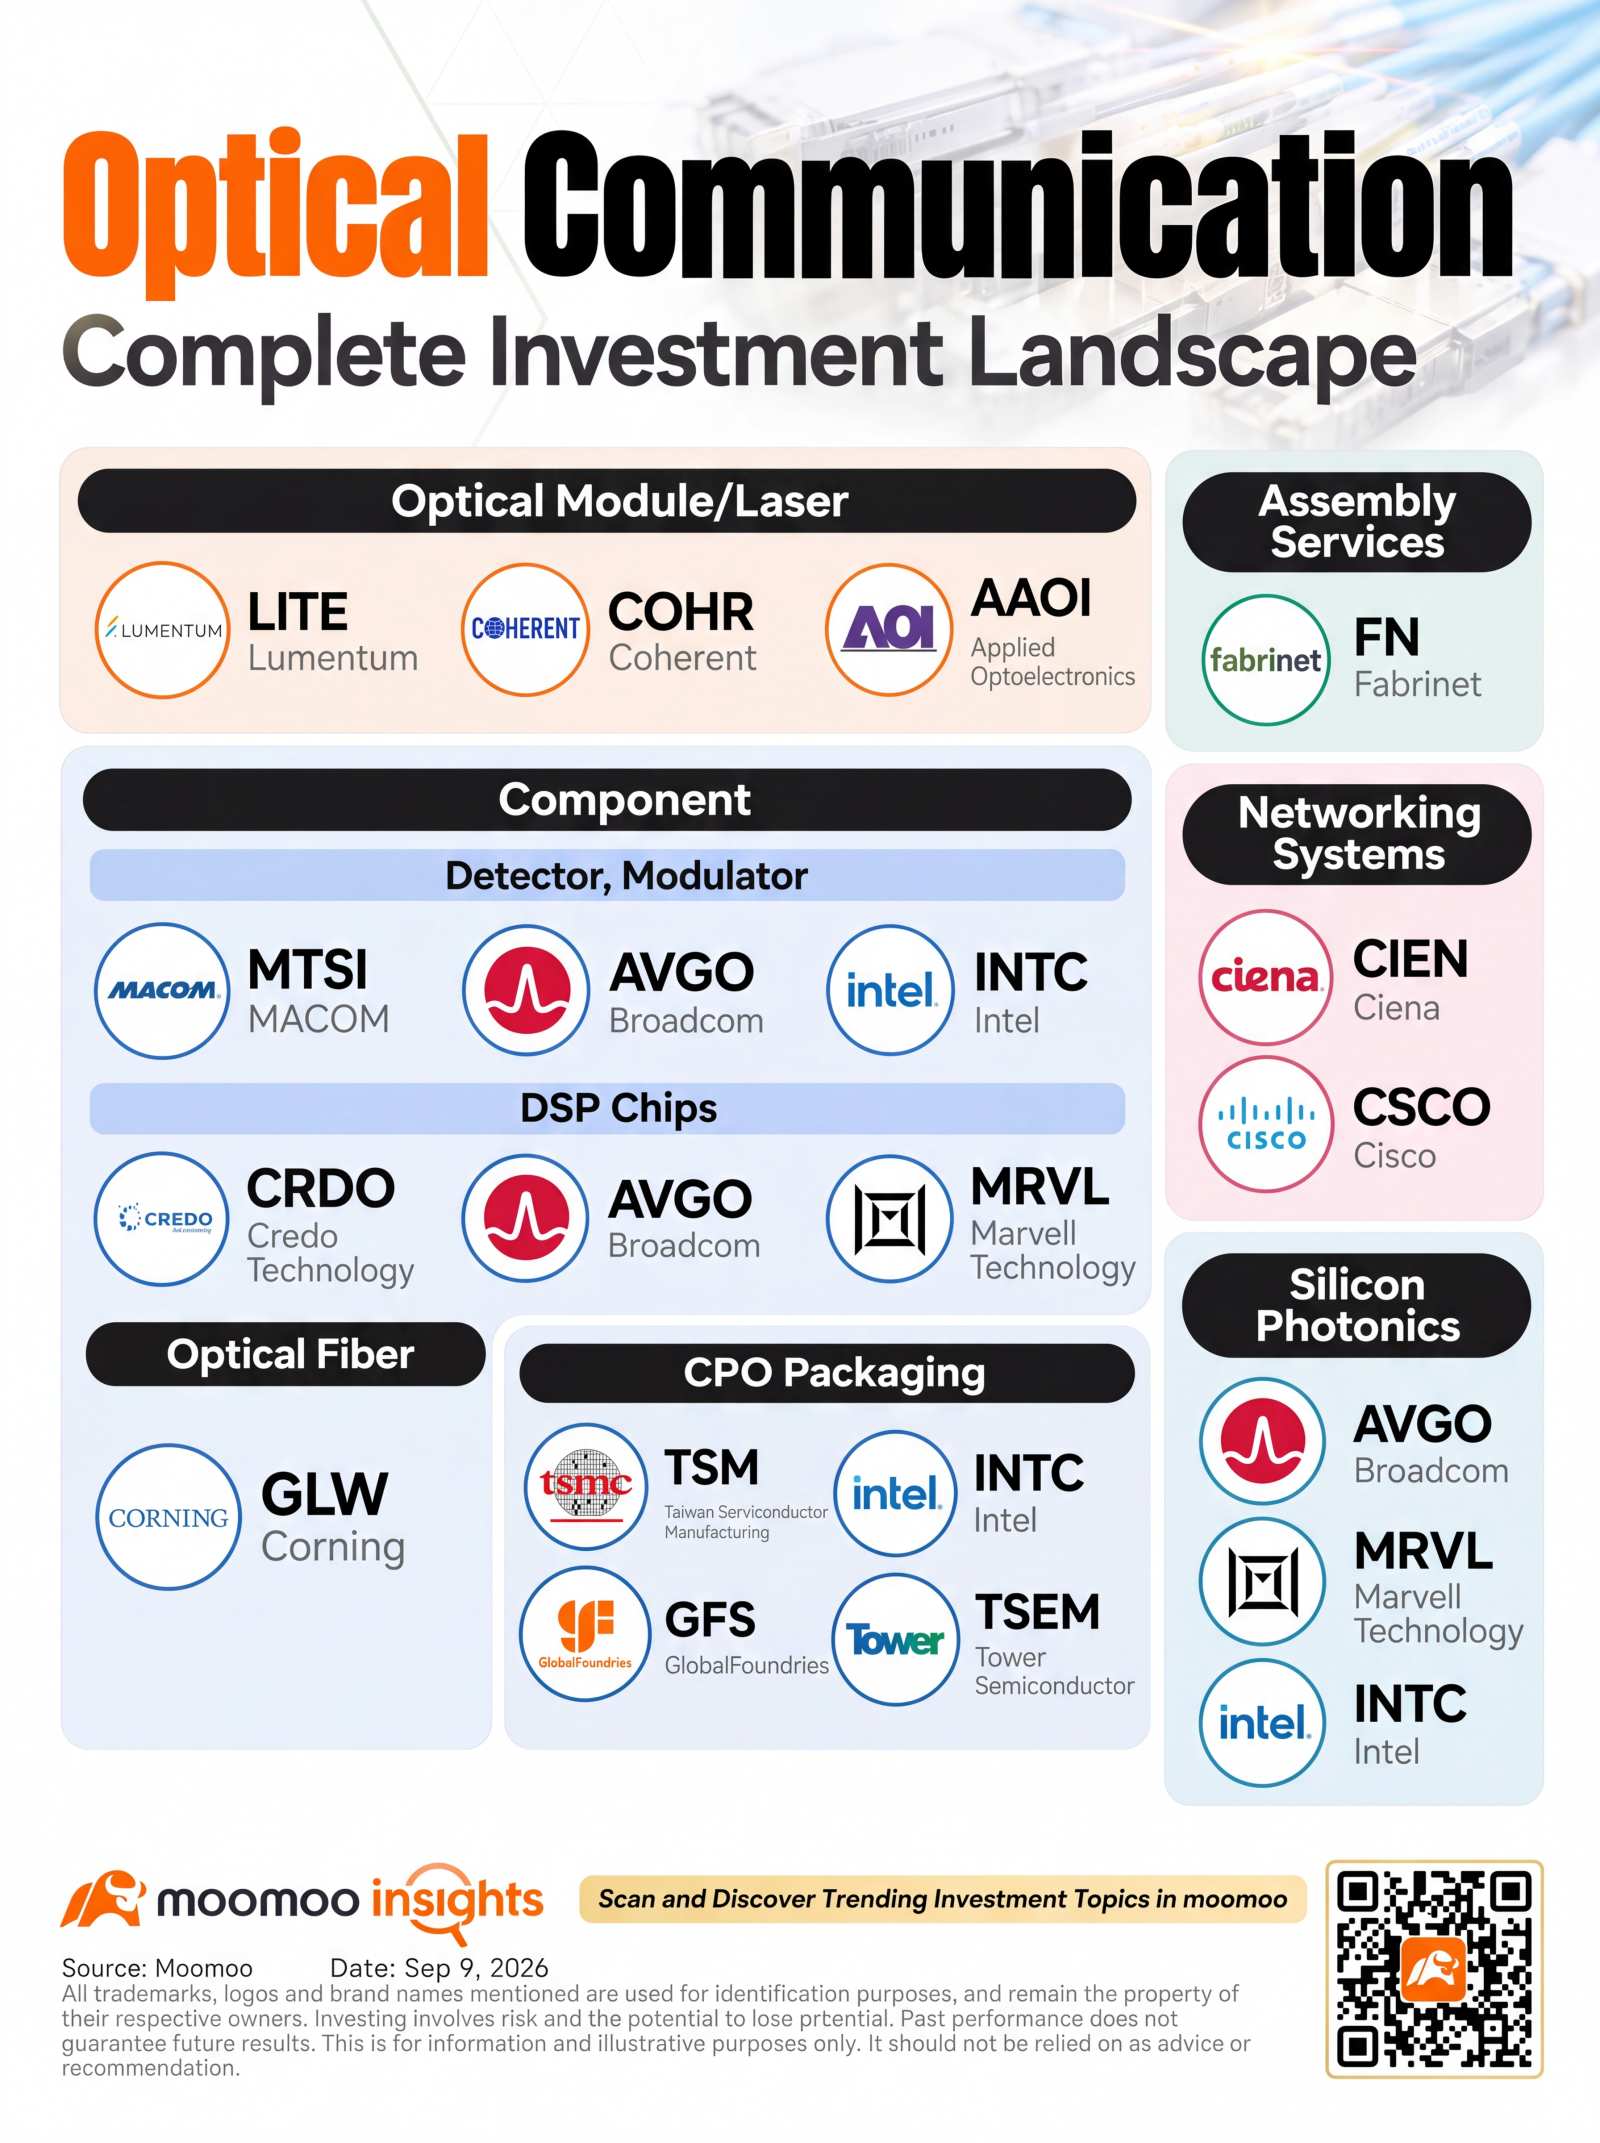

The Entire Optical Communications Sector Was Mispriced. Its Stocks Are Rebounding for a Reason
After months of underappreciation, US-listed optical communication equities have staged a meaningful rebound, driven by three material shifts in market narratives that are reshaping how investors size the sector’s total addressable market, margin profile and long-term AI linkage.
Three Key Narrative Shifts in This Rally
Narrative Shift 1: Repositioning
The biggest change is how the optical communications sector is being viewed: it’s moving from being just a supplier of pluggable optical modules to becoming a critical bottleneck asset for internal optical interconnects within AI clusters (with OCS, or Optical Circuit Switching, emerging as a major new storyline). Previously, the main thesis for US optical stocks was simply the generational upgrade from 800G to 1.6T transceivers. Now, the unifying theme is OCS, which handles dynamic optical routing inside massive GPU superclusters.
$Lumentum (LITE.US)$ (LITE) is leading the charge here. Their OCS shipments doubled quarter-over-quarter in FY26Q4, and management is guiding for over $400M in OCS revenue in the second half of 2026. By early FY27, they’re expected to become a core external OCS supplier for top-tier cloud providers, setting the benchmark for commercial shipments and driving a sector-wide revaluation. This effectively opens up a massive new TAM for the sector, independent of traditional optical module speed upgrades. Growth is no longer just related to Nvidia GPU shipments, which is the biggest driver behind the current valuation recovery.

Narrative Shift 2: The Margin Story Flips
The jump in gross margins isn't a one-off; it’s a structural shift. Leading companies are showing serious earnings resilience, with LITE’s gross margins breaking past 47.43%. The market used to think companies needed $2B in quarterly revenue to hit those margins, but now, top players are getting there with just $1B.
Earlier, investors assumed high margins were just a temporary windfall from supply-demand mismatches that would eventually fade. But it turns out the high margins are structural, driven by vertical integration across the supply chain (like in-house InP lasers), a rising mix of high-value CW laser chips, and the ramp-up of premium OCS systems. This logic is bringing a lot of fundamental money back into the sector.

Narrative Shift 3: Nvidia Supply Chain Ties Get Real
There used to be a lot of skepticism about when CPO (Co-Packaged Optics) would actually go commercial; it was treated as a distant concept and left out of core valuation models. But with $NVIDIA (NVDA.US)$ ’s Spectrum-X CPO switches going into full mass production in August 14, 2026, the tech roadmap and timeline are officially locked in.
On top of that, Nvidia’s massive equity investment and long-term supply deals with Lumentum have cemented the supply chain for the external CW laser chips needed for CPO. We’re looking at scaled deployments in 2027–2028, which will trigger a second wave of demand for laser chips. This removes the uncertainty around tech commercialization, anchors the sector's mid-to-long-term growth curve, and resets the valuation floor with a new premium for future growth.
Decoding Institutional Positioning
The latest available SEC 13F filings show that most institutions added to their optical communications positions last quarter.

For the quarter ended June 30, 2026, hedge fund activity in the optical sector was heavily concentrated in $POET Technologies (POET.US)$ . Citadel Advisors was the biggest buyer, aggressively adding about 9.74M shares (a massive 201.5% increase). Point72 followed suit, adding roughly 1.12M shares (+188%), while quant firm Renaissance took a brand-new position of about 3.47M shares. Two Sigma also bumped up its stake by nearly 149% (+92K shares). This synchronized, heavy buying across multiple firms points to a strong institutional consensus on POET. Millennium was the only notable exception, trimming a relatively small position of about 70K shares.
In contrast, $Coherent (COHR.US)$ saw a serious tug-of-war between bulls and bears. D.E. Shaw went all in, adding 1.67M shares (+1,364.4%), and Two Sigma jumped in with a 700%+ increase (+49K shares). But on the flip side, Millennium chopped its position by 74% (-740K shares), Point72 slashed theirs by 84% (-570K shares), Citadel Advisors trimmed 14% (-360K shares), and Bridgewater practically exited, cutting over 90% (-150K shares). When different institutions are making massive, diametrically opposed bets on the same stock, it shows a deep divergence in sentiment heading into the end of the quarter.
$Lumentum (LITE.US)$ also saw some portfolio shuffling. D.E. Shaw added about 770K shares (+57%), and Citadel Advisors made a modest addition of 110K shares. Meanwhile, Two Sigma, Point72, and Millennium took some profits, trimming roughly 120K, 54K, and 29K shares, respectively.
Disclaimer: Moomoo Technologies Inc. is providing this content for information and educational use only.Read more


Comments (7)
to post a comment
48
45