Micron Reclaims $1,000 as Whale Drops $22M on VIX Calls

Tech Rotation Charts: Hardware Leads as Software Stocks Cool
Last week, significant divergence emerged within the Mag7: the AI computing chain ( $NVIDIA (NVDA.US)$ ) and memory chips ( $Micron Technology (MU.US)$ , $SanDisk (SNDK.US)$ ) led gains, while cloud services ( $Microsoft (MSFT.US)$ , $Amazon (AMZN.US)$ , $Alphabet-A (GOOGL.US)$ ) came under pressure. The market's central concern is wait-and-see sentiment ahead of $Apple (AAPL.US)$ 's new product launch, and geopolitical risks suppressing risk appetite.
Asset Rotation Analysis
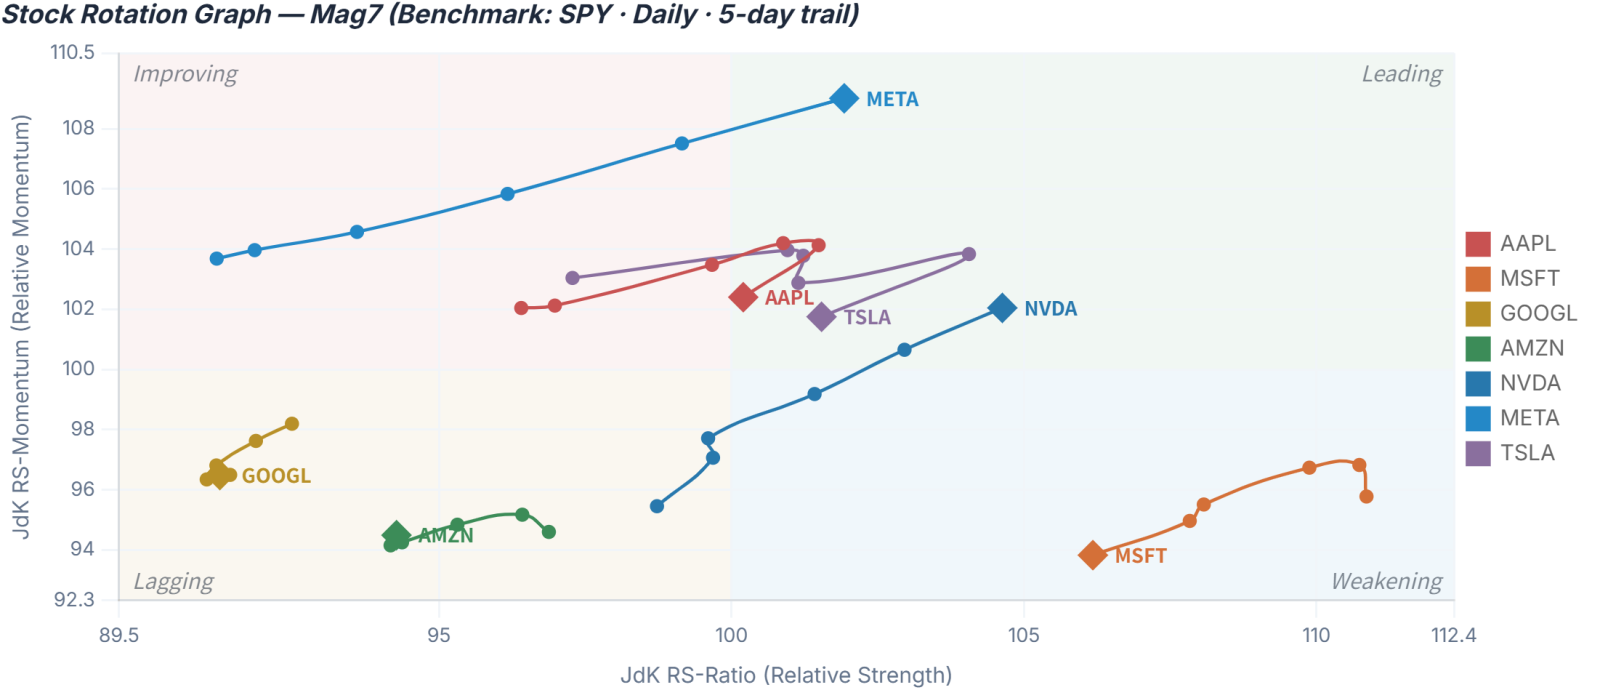
Mag7: Overall positioned in the leading zone, but with intense internal divergence. NVDA, META, TSLA, and AAPL all sit in the leading quadrant. META and NVDA showed clear upward expansion in their 5-day trajectories, with relative strength and momentum strengthening in tandem—consistent with their respective gains of 6.7% and 5.89% last week. MSFT, however, has slipped into the weakening quadrant, with relative momentum falling below the benchmark and its 5-day trajectory continuously trending downward, corresponding to last week's 2.69% decline. Both GOOGL and AMZN remain in the lagging quadrant with no signs of trajectory improvement, lagging in both relative strength and momentum, with last week's declines of 2.35% and 2.97% respectively.
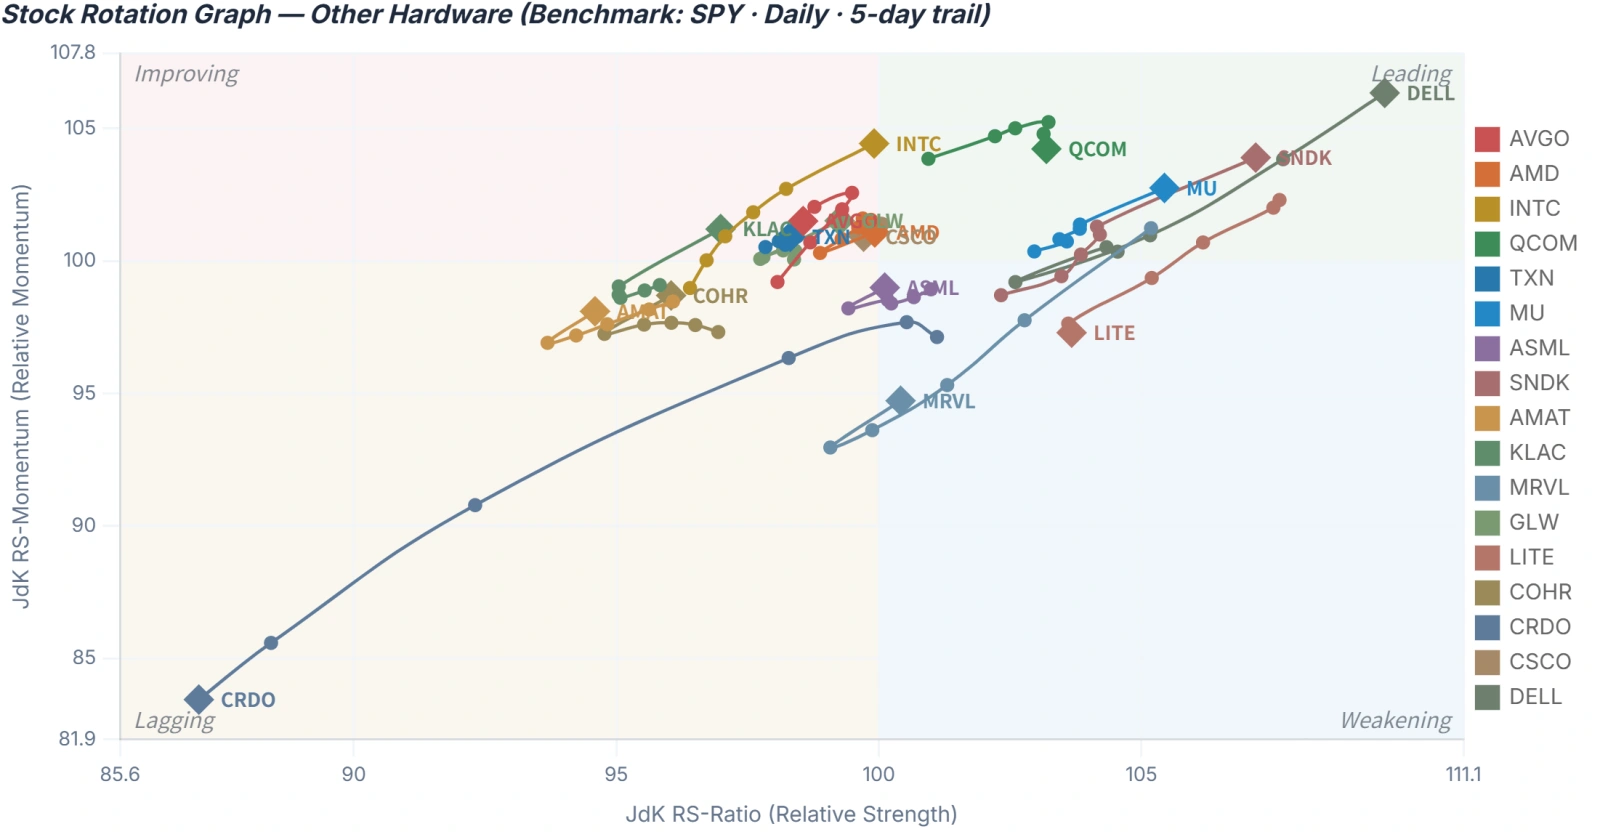
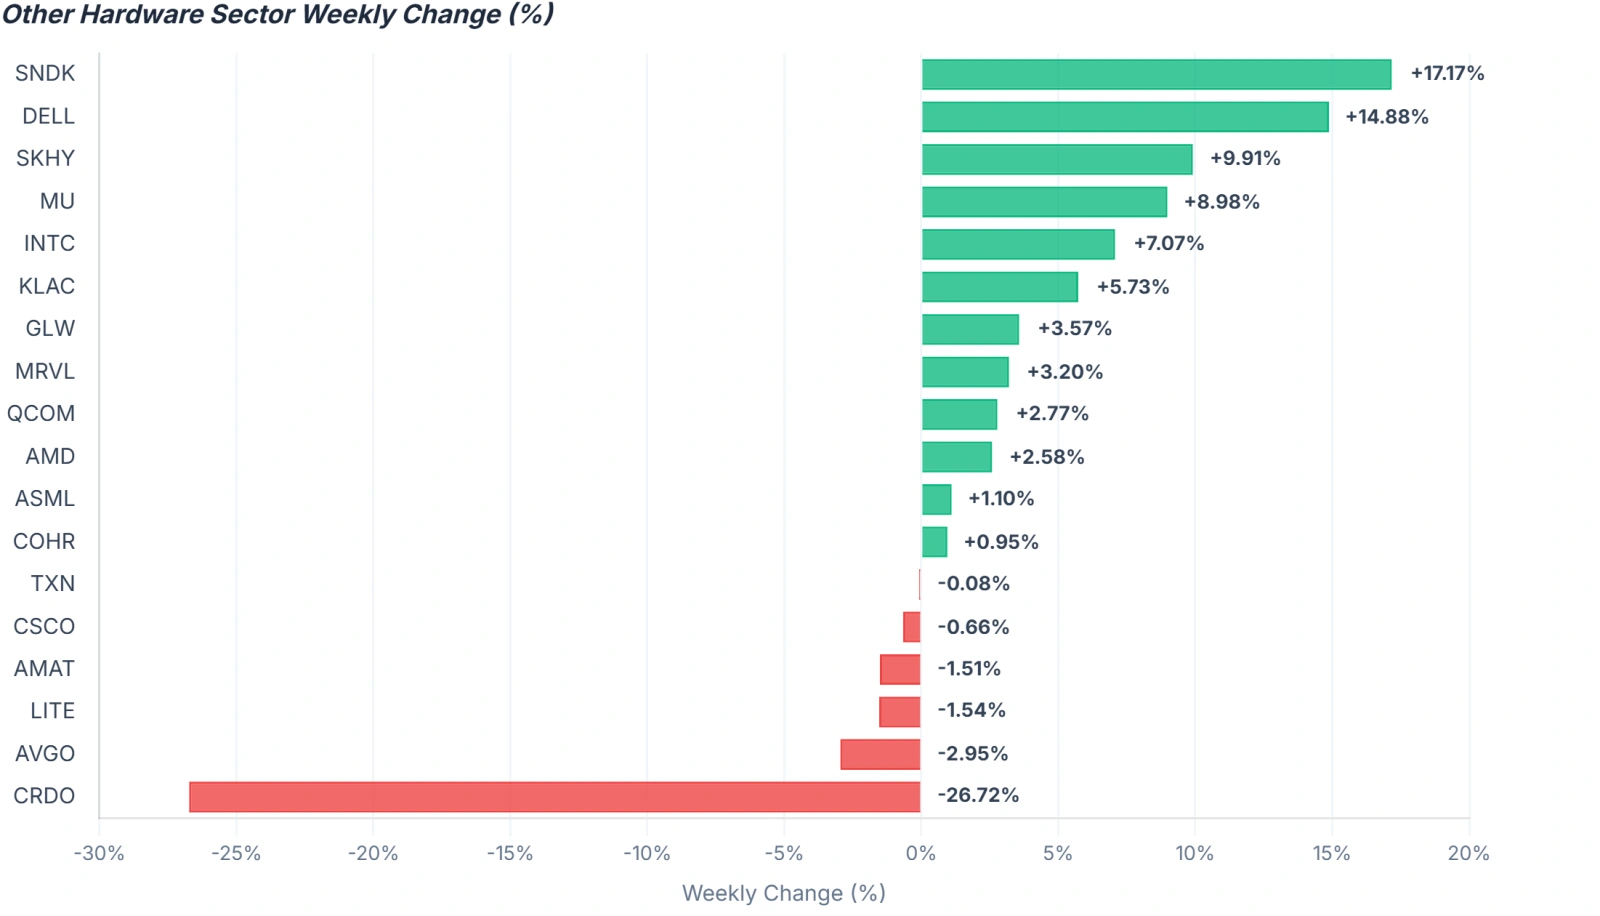
Other Hardware Sectors: Overall performance was robust, with most names in the leading or improving quadrants. The memory chip chain was particularly prominent— $SanDisk (SNDK.US)$ , $Micron Technology (MU.US)$ , and $Dell Technologies (DELL.US)$ all sit in the leading quadrant with upward trajectories, surging 17.17%, 8.98%, and 14.88% respectively last week. $Intel (INTC.US)$ , $KLA Corp (KLAC.US)$ , $Corning (GLW.US)$ , $Broadcom (AVGO.US)$ , and $Advanced Micro Devices (AMD.US)$ are in the improving quadrant, with INTC rising 7.07% and KLAC gaining 5.73% last week. $ASML Holding (ASML.US)$ and $Marvell Technology (MRVL.US)$ are in the weakening quadrant, with MRVL's 5-day trajectory deteriorating sharply (both relative strength and momentum declining), despite the stock still rising 3.2% last week—momentum has clearly faded. $Credo Technology (CRDO.US)$ is deeply lagging, plunging 26.72% last week with a continuously deteriorating trajectory. Overall, AI infrastructure (memory, networking, foundry) remains the absolute main theme in the hardware sector.
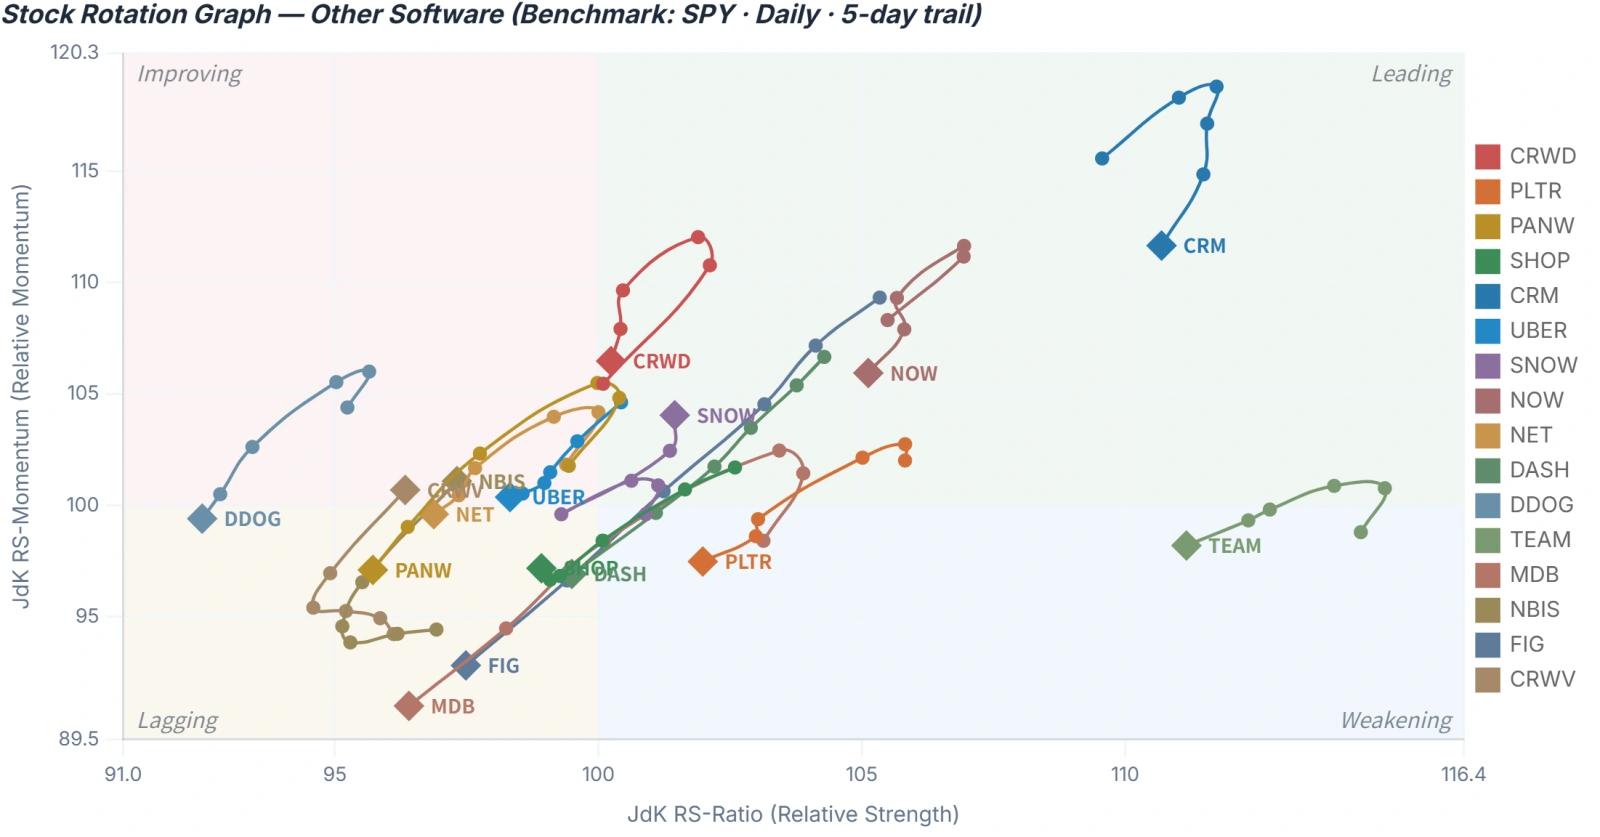
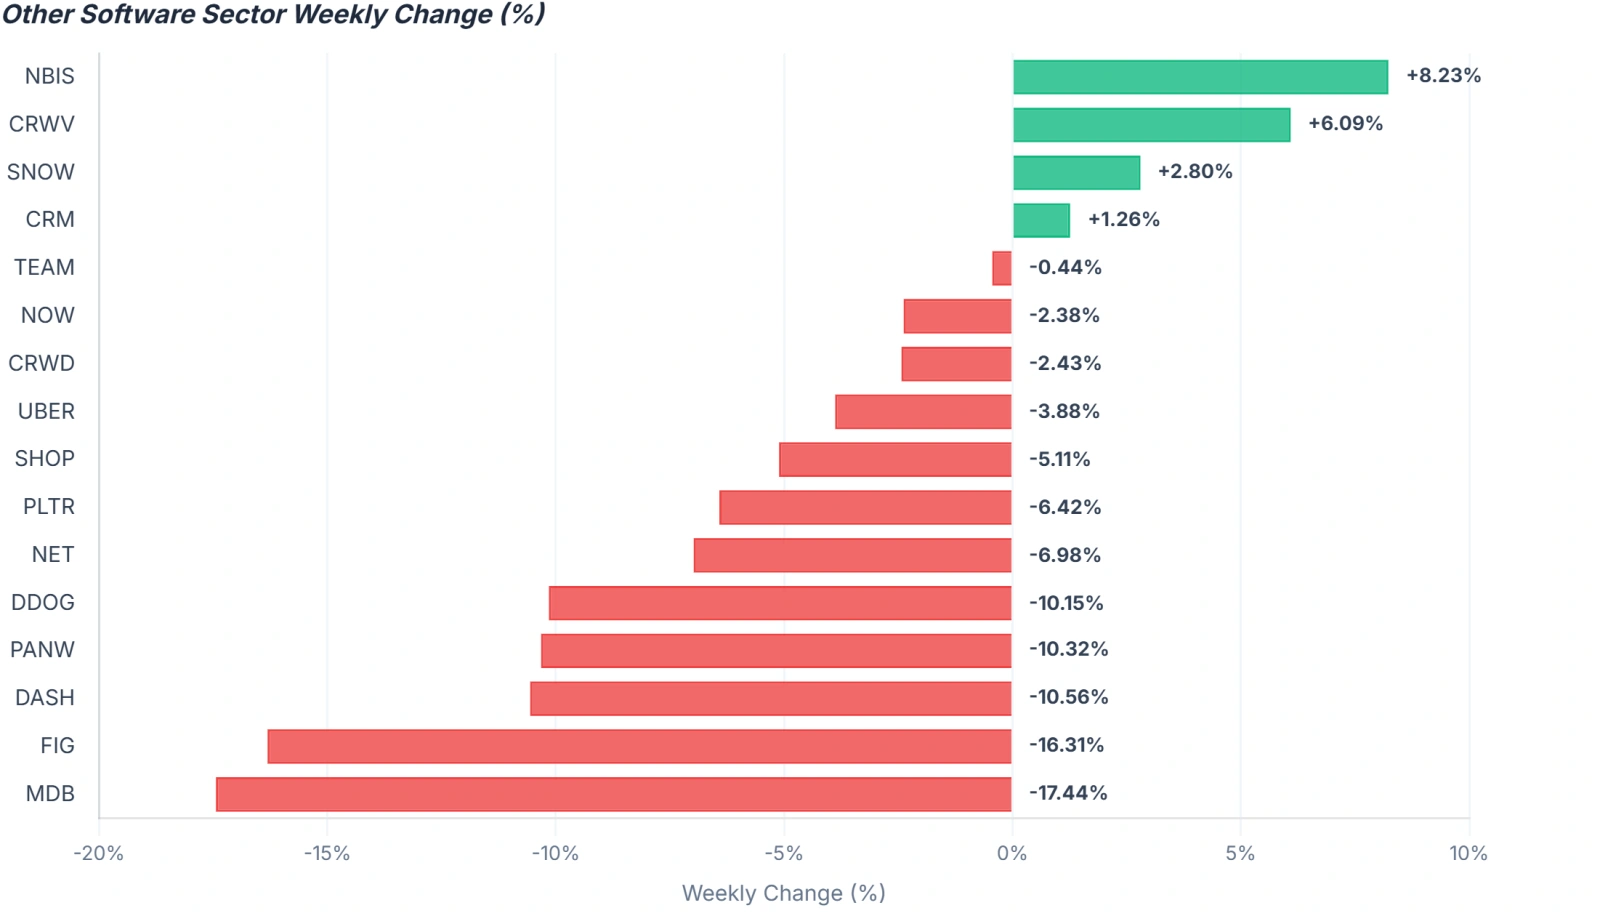
Other Software Sectors: Divergence is extremely pronounced. $Salesforce (CRM.US)$ , $ServiceNow (NOW.US)$ , $Snowflake (SNOW.US)$ , and $CrowdStrike (CRWD.US)$ are in the leading quadrant, but CRM and NOW's momentum trajectories have shown signs of flattening or pulling back. $Palantir (PLTR.US)$ and $Atlassian (TEAM.US)$ are in the weakening quadrant, with PLTR falling 6.42% last week. Notably, a large number of names including DASH, DDOG, MDB, FIG, and PANW are in the lagging quadrant with substantial losses last week (FIG down 16.31%, MDB down 17.44%, PANW down 10.32%, DASH down 10.56%), indicating that the software sector is undergoing intense defrothing. $Uber Technologies (UBER.US)$ , $NEBIUS (NBIS.US)$ , and $CoreWeave (CRWV.US)$ are in the improving quadrant, with NBIS rising 8.23% and CRWV gaining 6.09% last week, showing capital seeking new AI narrative names within the software sector.
Quantitative Factor Rankings
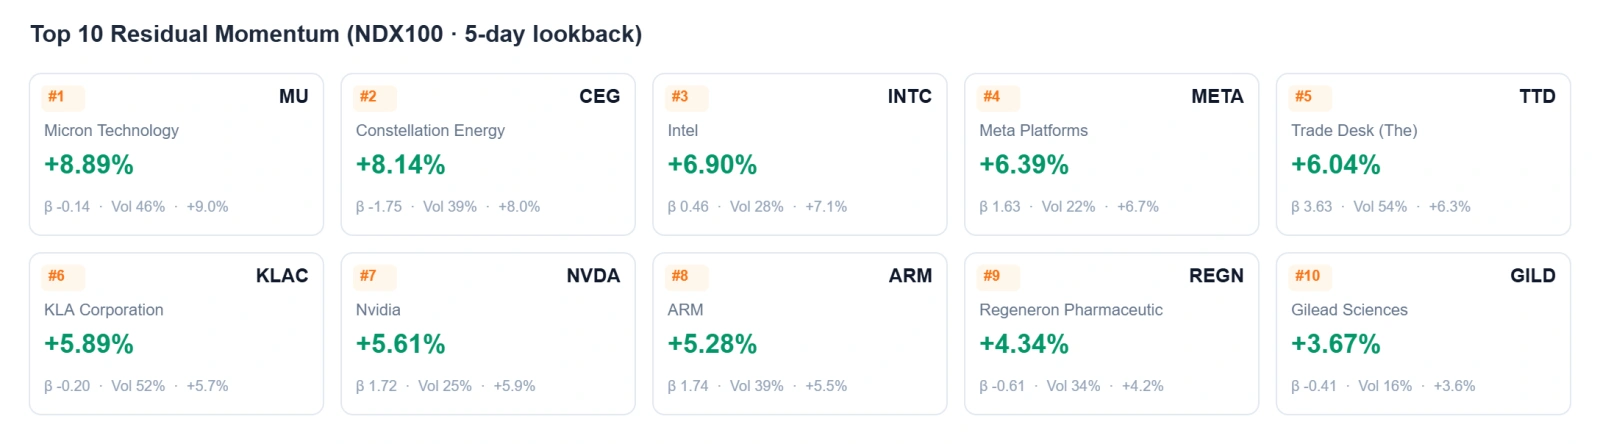
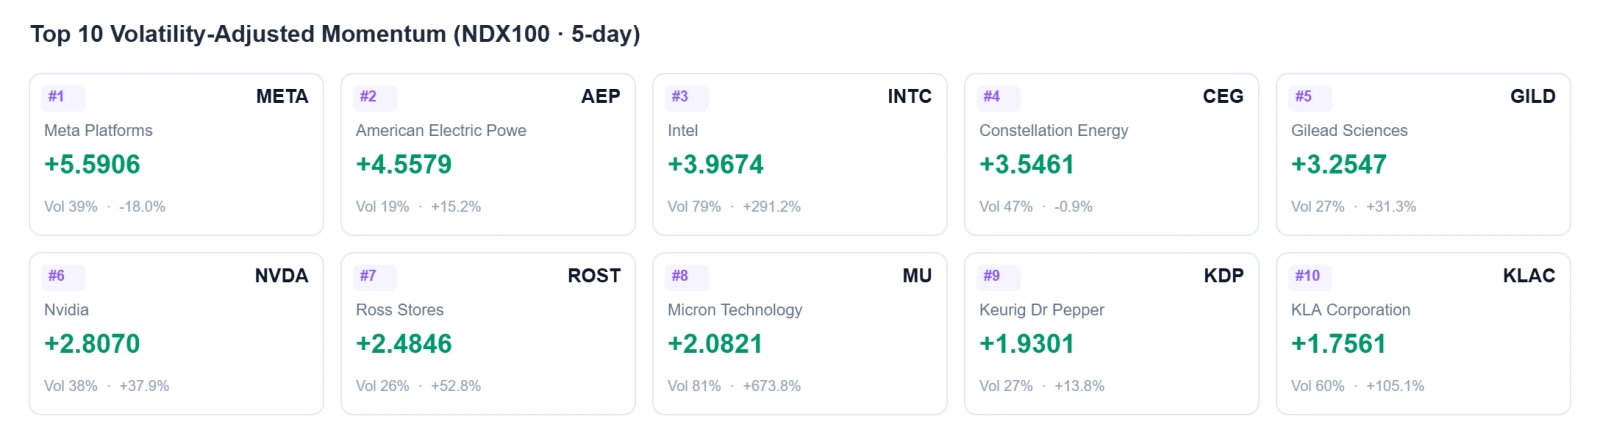
Dual Signal Names: META, NVDA, MU, INTC, KLAC, CEG, and GILD simultaneously appear in the top 10 of both the residual momentum and volatility-adjusted momentum strategies, constituting a strong resonance signal. Among these, META, NVDA, MU, INTC, and KLAC all belong to AI infrastructure or platform companies, highly consistent with their leading or improving quadrant positions in the RRG analysis.
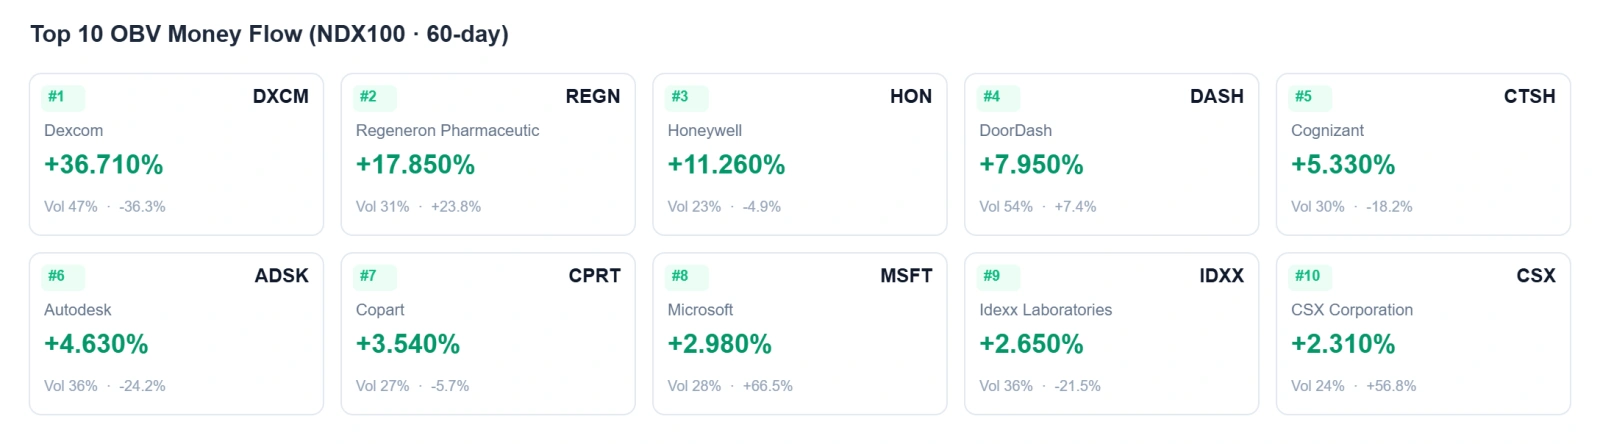
CEG (Constellation Energy), as an AI power supplier, appearing in both strategies reflects market pricing of AI electricity demand. REGN appears in both the residual momentum and OBV strategies but is a pharmaceutical name independent of the AI main theme.
Weekend Events
AAPL
- [2026-09-06] Apple announced another price increase for Apple TV and Apple One bundle plans, with Apple TV monthly fees rising from $12.99 to $14.99, indicating the services business continues to drive growth through price increases.
- [2026-09-06] Apple will hold a new product launch event on September 9 at Apple Park. This will be the first iPhone launch under new CEO John Ternus, drawing significant market attention.
MSFT
- [2026-09-07] Microsoft experienced a large-scale outage of Outlook and Exchange Online, with OpenAI's ChatGPT also experiencing issues the same day, raising market concerns about cloud service stability.
- [2026-09-05] The Seattle Times and Newsday filed lawsuits against OpenAI and Microsoft, alleging unauthorized use of news content to train AI models, with copyright litigation risks continuing to accumulate.
- [2026-09-05] CEO Satya Nadella sold 86,525 Microsoft shares on September 1 through a trading plan, cashing out approximately $43.39 million, sparking discussion about insider signals.
- [2026-09-04] Microsoft announced it will restructure its financial reporting structure starting fiscal year 2027, separately disclosing AI and cloud business segments to improve AI business transparency.
GOOGL
- [2026-09-06] Google released the Gemini 3.8 Flash model and launched the Fairwind project, accelerating its pace in the AI race.
AMZN
- [2026-09-06] Amazon's Zoox expanded its autonomous robotaxi service to Las Vegas airport, further deepening its presence in autonomous mobility and AI policy.
NVDA
- [2026-09-06] CEO Jensen Huang stated that OpenAI's GPT-6 Astra model marks the arrival of AGI, with the model trained on Nvidia chips.
META
- [2026-09-07] Meta agreed to pay up to $18 billion to settle youth safety-related litigation, setting a historic record, with the market watching the cascading pressure this creates on TikTok and YouTube.
TSLA
- [2026-09-06] Goldman Sachs believes Cybercab will give Tesla a cost advantage in the autonomous robotaxi space, though scalability remains to be proven.
- [2026-09-06] Cybercab faces its first federal regulatory test following its Austin launch, with the market monitoring compliance progress.
- [2026-09-05] Musk stated the Cybercab uses a gold finish to symbolize the "golden age of mobility," integrating Starlink connectivity.
Key Takeaways
1. AI Computing Chain Fundamentals Continue to Validate: NVDA provided its first multi-year revenue guidance and announced a $12.9 billion investment on Hugging Face, combined with surging memory chip stocks like MU and SNDK, continuously reinforcing expectations for AI infrastructure demand.
2. Intense Divergence Within the Mag7: AI computing and platform companies (NVDA) led gains, while cloud services and consumer electronics (MSFT, AMZN, GOOGL) weakened, with clear rotation of capital among the mega-caps.
3. Memory Chips and AI Hardware Emerge as the Strongest Theme: SNDK rose 17% for the week, DELL gained 15%, and MU advanced 9%, with the memory upcycle resonating with AI server demand, driving the entire hardware sector higher.
4. Software Sector Undergoing Intense Defrothing: MDB fell 17%, FIG dropped 16%, DASH declined 11%, and PANW lost 10%, with high-valuation software stocks being sold off as capital concentrates toward names with clear AI narratives.
5. Geopolitical and Regulatory Risks Intensify: The Iran conflict escalation suppressed risk appetite, Meta's record $18 billion settlement, and renewed copyright lawsuits against Microsoft and OpenAI mean policy and legal costs for big tech companies continue to rise.
*Disclaimer: The rankings above are based on technical factors calculated from historical data and are provided for research reference only, not constituting investment advice. Factor effectiveness is subject to market environment influences, and past performance does not guarantee future returns.*
Disclaimer: Moomoo Technologies Inc. is providing this content for information and educational use only.Read more


Comments (5)
to post a comment
55
39