“Genesis Mission” key milestone: Will AI reshape national scientific research?


Parp’s NVIDIA short report: Why NVIDIA Will Suffer a Similar Fate to Cisco.
So to get straight to the point, I believe NVIDIA’s current valuation is unsustainable. I am betting NVIDIA’s current valuation will likely fall drastically over the coming years. In a worst case scenario, it could end up being worth as little as $40 - $50 within the next 1 - 2 years. Below I will be going over every reason why that is.
It sounds insane right? Shorting what is currently the most valuable company in the world. Which on the surface appears to be an unstoppable growth machine that will lead us into the future of AI. However when you look under the hood of this company you will see both how fragile it’s current valuation truly is, and see how its collapse looks almost inevitable.
For some context, I have been short NVIDIA before Burry returned to X and I have been calling out this bubble in tech since January in older posts. Yes I will be referencing some of his thoughts here and some of my own. So do not worry, I will not just be copying Burry, but to a large extent this post is inspired by him. When Burry returned I was excited to see that Burry and I have shared a few similar thoughts on this company and this AI bubble. He has also shown me things I was not even aware of.
Now, I know this community all too well, especially the NVIDIA bulls here. Most of you are not interested in analyzing a company further than its chart, and some overly hyped up headlines. So to grab your attention we will start first by taking a look at the chart. This will also explain to some extent where I got my $40 - $50 price target from.
•The technicals:
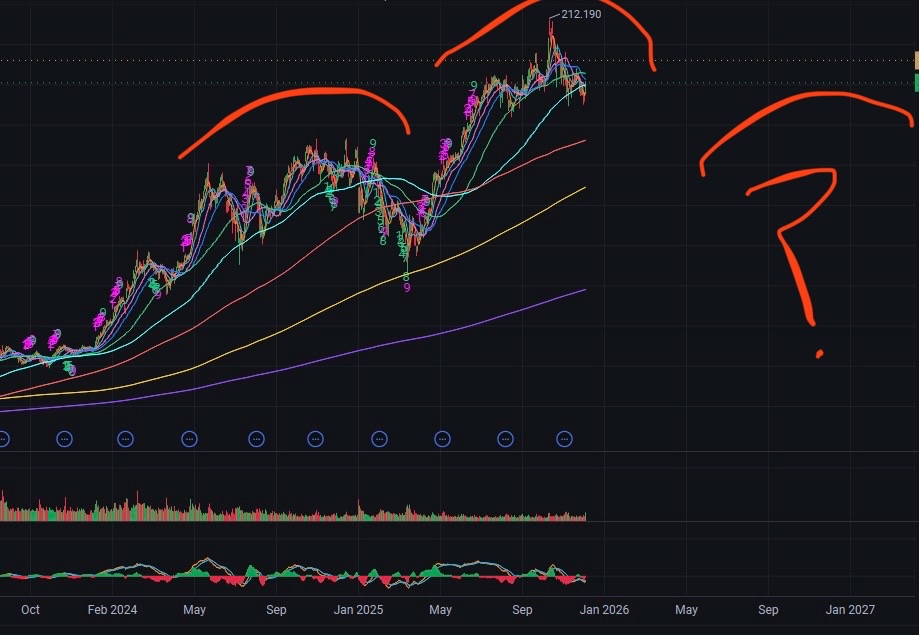
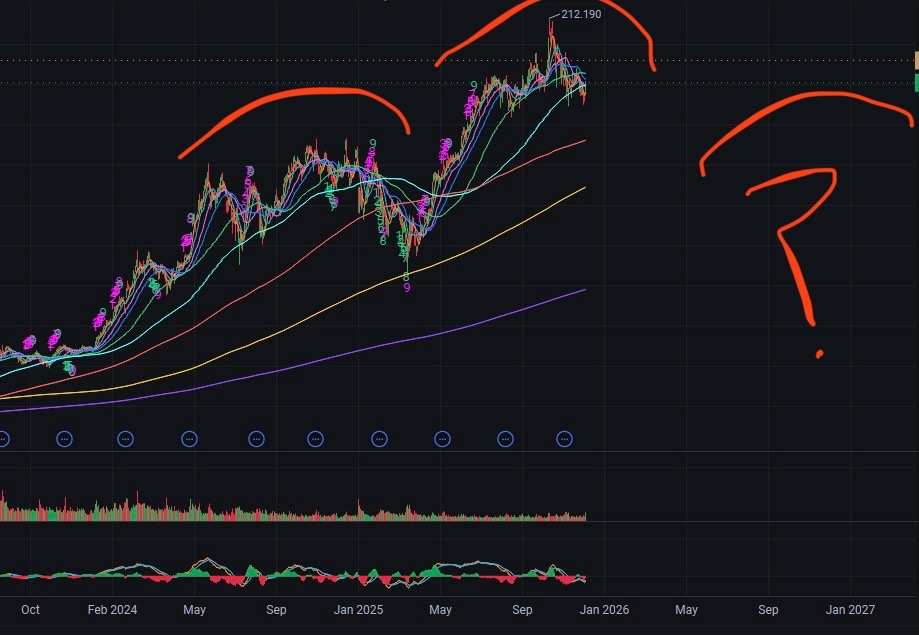
As you can see here if you zoom out on the chart there is what appears to be a head and shoulders pattern forming, spanning all the way back to early 2024 where the beginning of it starts around the $40 - $50 range. If the seconds half of this head and shoulders is mostly symmetrical to the first, that is likely the price we will head back to. This would also line up with my 1 - 2 year time frame.
•A brief Anecdote
Also speaking of retail and their general disinterest in doing real analysis. I’d like to share one little Anecdote of mine concerning the types of people investing in NVIDIA currently.
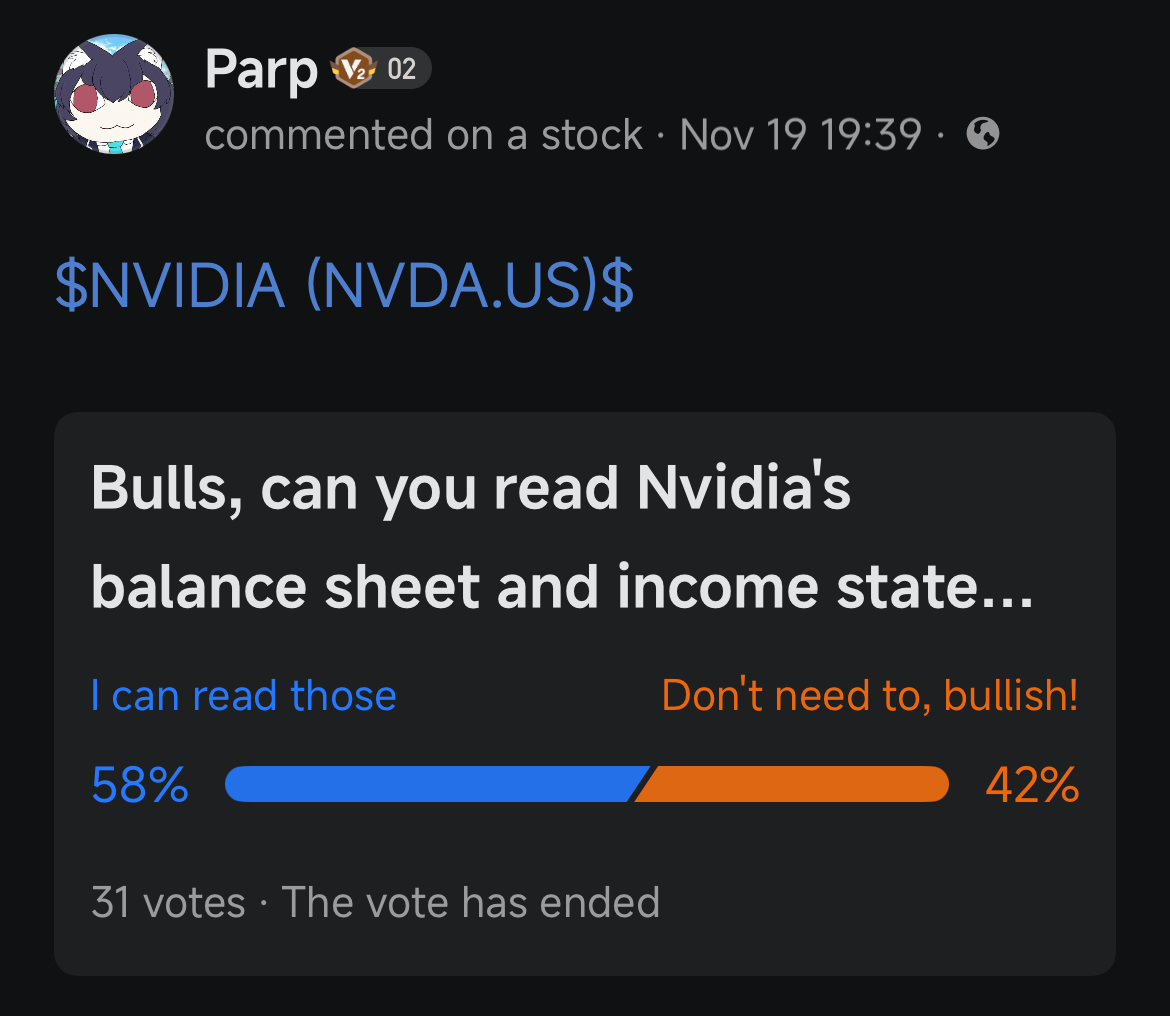
While yes, 31 people isn’t a lot, I believe this is still worth noting. Disturbingly nearly half of participants are not interested in doing fundamental analysis for NVIDIA, nor do they find it to be important. I don’t believe I need to explain why that is a major red flag.
Before we delve into the more important parts of the thesis, I want to go over one last little thing.
•The insiders and institutions.
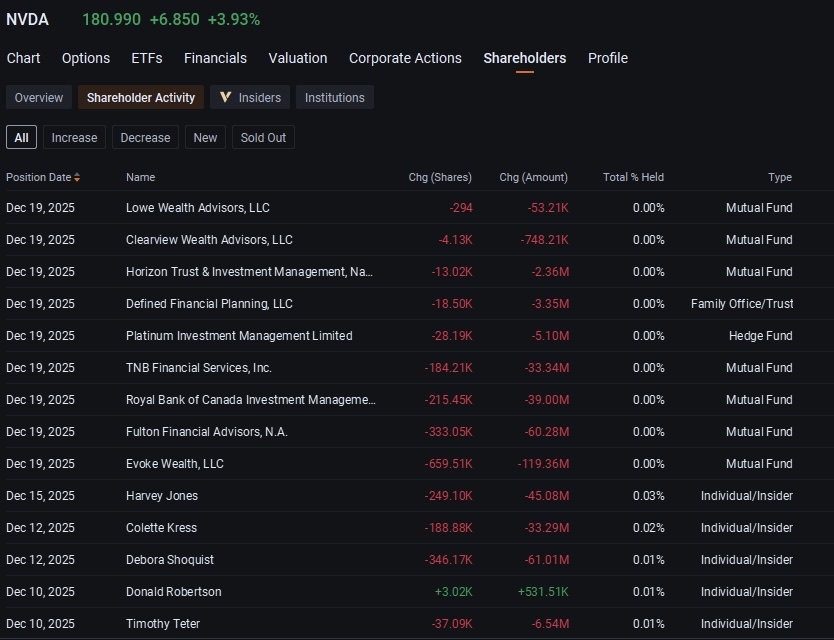
Recently the overwhelming majority of both Institutional investors and insiders have been selling off NVIDIA shares. While on its own it’s not something to be overly concerned about. It does not scream confidence, and is certainly worth paying attention to. Especially when you see large institutions like SoftBank, and people like Peter Thiel, and Ray Dalio closing or drastically shrinking their positions in NVIDIA.
Now we will move on to the real meat and potatoes of my thesis.
•Circular financing
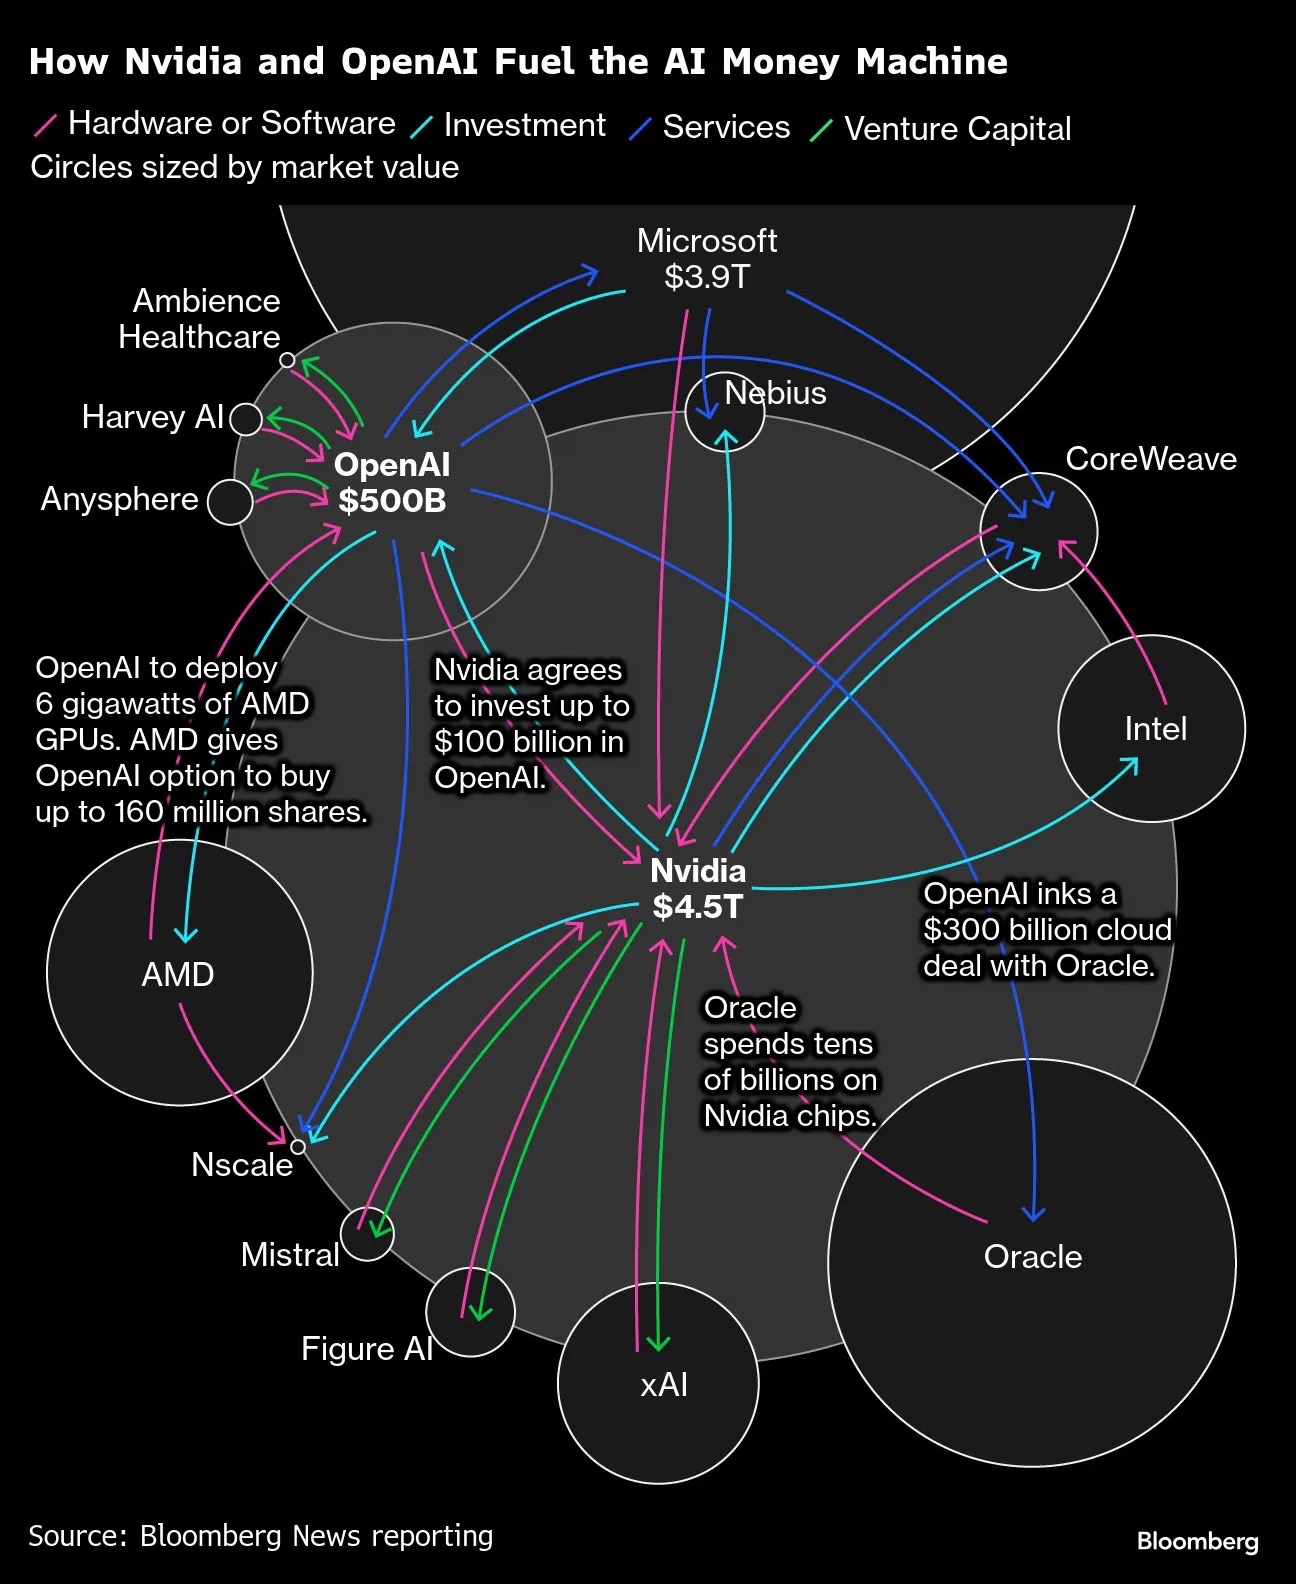
It’s no secret that NVIDIA is engaging in circular financing to artificially inflate their revenue along with their partners. NVIDIA is investing into their customers and in return their customers use that money to then purchase NVIDIA’s hardware. For example, NVIDIA invested in OpenAI, OpenAI purchased NVIDIA’s hardware with that money. It even goes even a step further. Oracle comes and purchases NVIDIA’s hardware and then right after, OpenAI signs a $300 billion deal with Oracle using the money NVIDIA invested into OpenAI. The danger with circular financing is that if one of these companies fails, it could easily trigger a domino effect since all of these companies are now so closely tied together. On this massive scale it poses a legitimate systemic risk.
•Customers turned competitors
NVIDIA’s largest customers have been by far the main driver of their explosive revenue growth and demand. Spending insane amounts of money on chips to get ahead in the AI space. A space that’s future is still not entirely certain. Aware there could be overspending going on, and a desire to reduce CapEx, many of NVIDIA’s largest customers have decided to start designing and even selling some of their own in house chips. They are essentially becoming a competitor to NVIDIA by doing this. Recently this trend has been picking up a lot of steam. For example, recently Google began rolling out its most powerful TPUs. Meta is already in talks to purchase these TPUs, and that’s not to mention Meta is designing their own chips too. Amazon is another example of a big tech company designing its own AI chips to reduce reliance on NVIDIA. Apple announced it would use Amazon’s Trainium2 chips for its own AI development. If this trend continues, which is basically inevitable, this will eat away at NVIDIA’s revenue growth massively over time. Keep in mind NVIDIA has unrealistically high expectations to maintain their current demand going into the future. This could spell disaster for NVIDIA’s current high valuations.
•Depreciation time bomb.
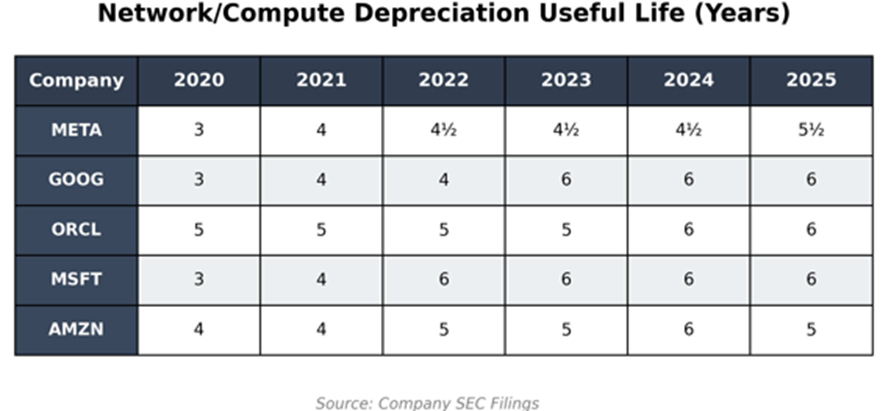
NVIDIA’s customers are extending the life expectancy of their chips to artificially boost earnings. They are increasing life expectancy based on the massive increase in capital expenditure through purchasing NVIDIA’s chips rather than basing it on the true economic value these chips have generated thus far. While this is permitted under accounting standards, it doesn’t bypass economic reality. This cannot go on for much longer and once these chips start to depreciate we will start to see some of the consequences of the overspending in AI chips. As a result the market is going to be a lot harder on these companies in wanting to see proof these investments in AI chips are paying off and providing returns for shareholders. A stark contrast to how the market has been blindly rewarding massive CapEx on AI infrastructure with a highly speculative future. This will also cause NVIDIA’s customers to be a lot more cautious and conservative with their investments into AI infrastructure going into the future which obviously would deal a huge blow to the demand of NVIDIA’s chips.
•Power Hungry chips and the race with China.
Electricity and water bills are skyrocketing across the US thanks to AI data centers utilizing NVIDIA’s chips. As of now an alarming portion of that energy is being used to generate slop content that benefits the world in no way shape or form.
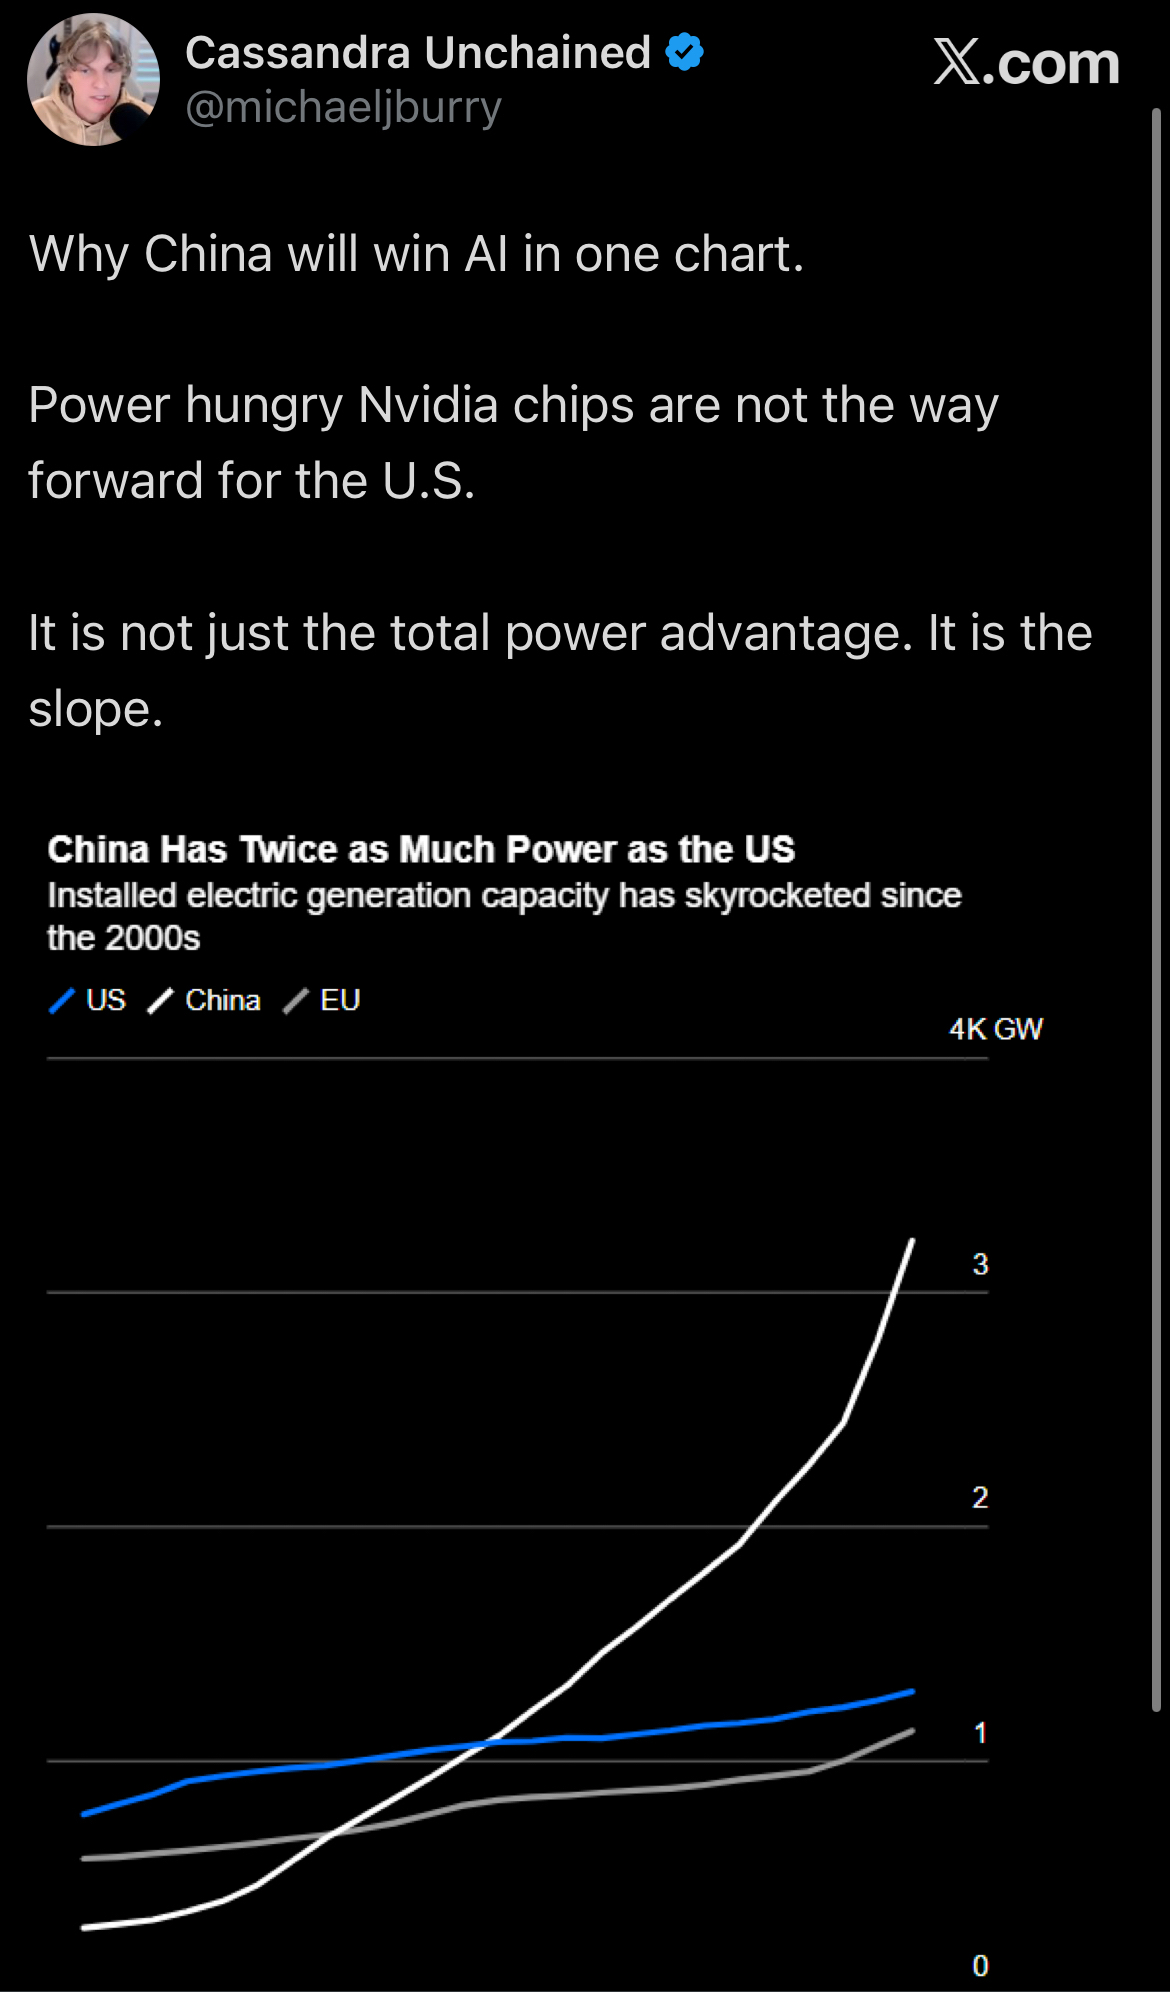
Tech Companies need to be more cognizant of the amount of energy they use and focus more on energy efficiency or we are only going to continue to fall behind in the AI race. Even NVIDIA’s CEO, Jensen Huang, believes China is ahead in AI. If we continue to take our energy supply for granted like we are now, it will lead to serious consequences for the economy and only hinder the future development speed of AI. This obviously is not in America’s best interest and should not be allowed to continue.
•NVIDIA is Cisco 2.0?
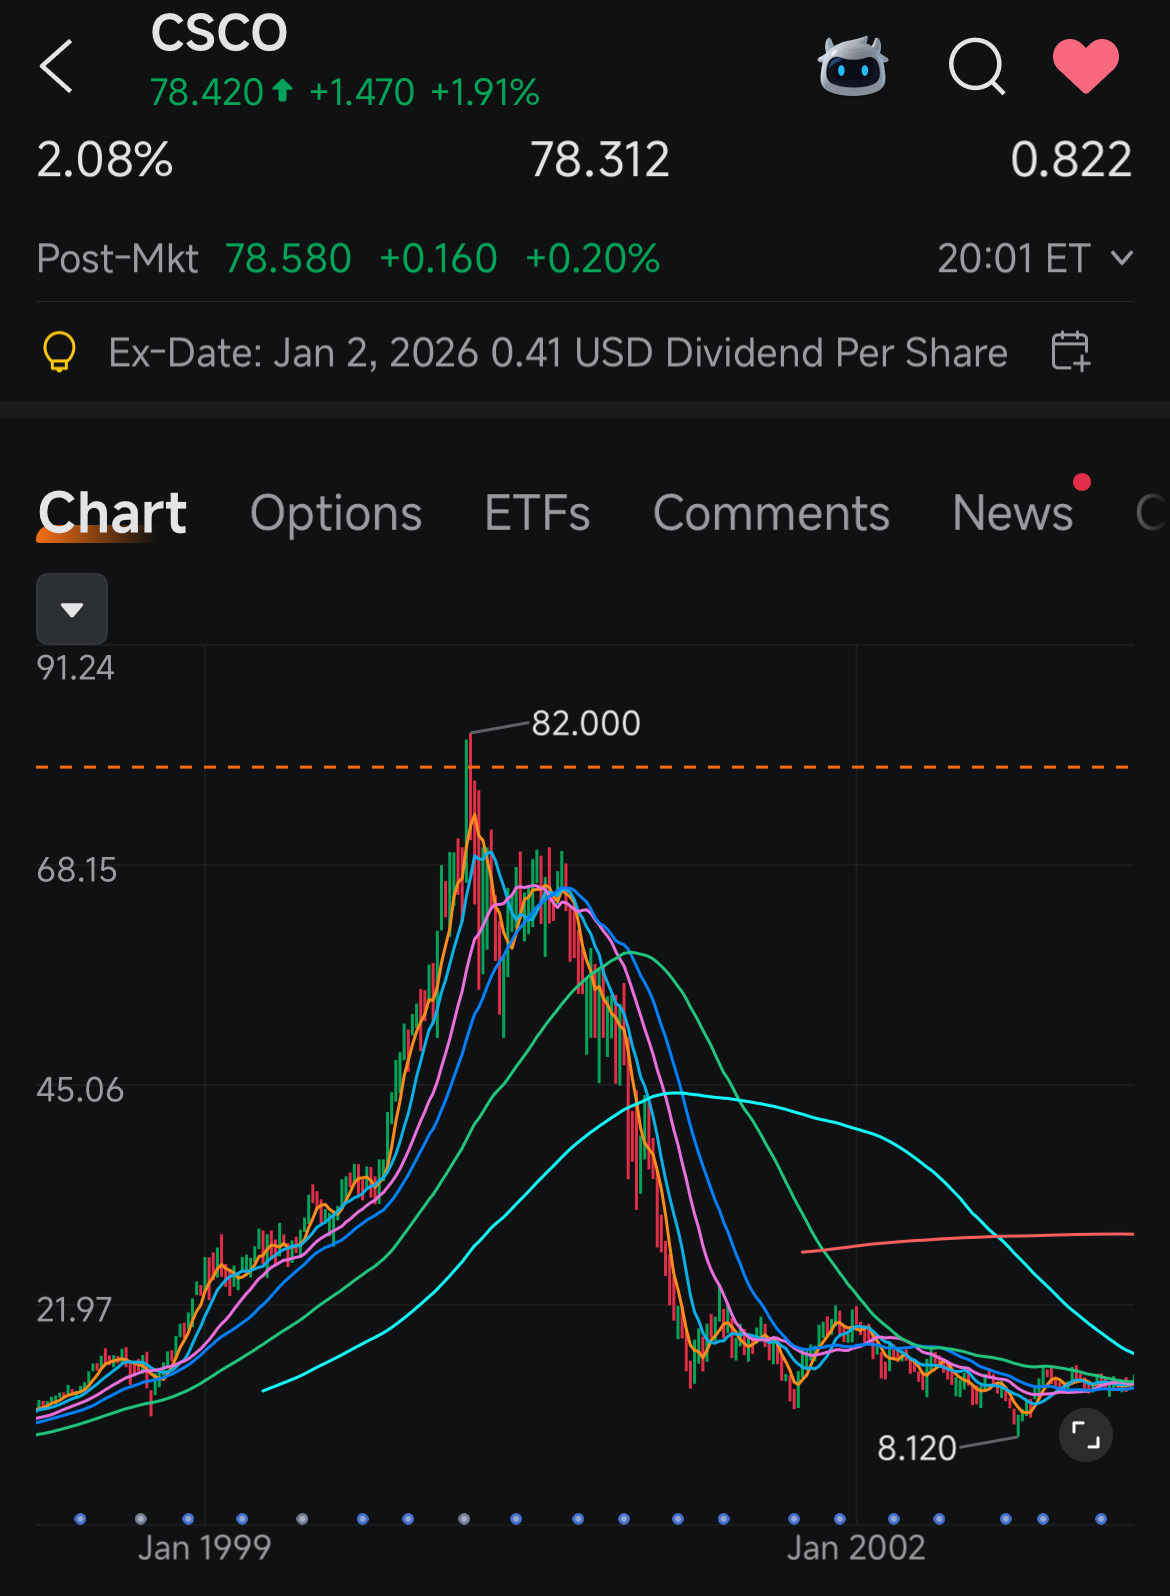
In many ways NVIDIA today echoes Cisco during the dot-com bubble in 2000. They are both the “picks and shovels” providers of their times. Once the infrastructure was mostly built for the internet, demand for Cisco’s hardware fell sharply. Uncertainty surrounding ROI (return on investment) was another big factor in the sharp decline in demand for Cisco’s hardware after the massive fiber optic build-out in 2000 which at the time lacked the profitability to sustain or justify more demand. Both Companies became the world’s most valuable during their times. Like Cisco, Nvidia has a very high concentration of customers and this concentration could worsen as NVIDIA plans to pivot away from its PC gaming customers. As I have stated before, these very same big tech customers are now trying to diversify away from NVIDIA and even compete.
Credit to Michael Burry for publicly providing some of the data shown above. https://x.com/michaeljburry?s=21 $NVIDIA (NVDA.US)$ $Invesco QQQ Trust (QQQ.US)$ $Vanguard S&P 500 ETF (VOO.US)$ $Oracle (ORCL.US)$ $Cisco (CSCO.US)$ $KraneShares CSI China Internet ETF (KWEB.US)$ $Alibaba (BABA.US)$ $Tesla (TSLA.US)$ $Meta Platforms (META.US)$ $Amazon (AMZN.US)$ $Broadcom (AVGO.US)$ $Apple (AAPL.US)$
Like Burry, I am a strong believer that history commonly foreshadows and rhymes with the future. One quote from Warren Buffett comes to mind when I think of the people who pass off all of this information as nothing more than simply “FUD” and don’t take it seriously. “What we learn from history is that people don't learn from history” - Warren Buffet.
•My final thoughts.
With everything I have stated, I don’t believe NVIDIA is a good investment from a risk to reward perspective. There are far too many things that both can and are going wrong currently. Between the accounting shenanigans, the overspending from big tech, the high concentration of customers that are now turning into competitors all while participating in circular financing to artificially boost revenue. The unrealistic expectations that not only need to be met but beaten, the massive energy consumption that puts us at a disadvantage, and of course the uncertainty ahead. All of these things scream sell to me. It’s very difficult for me to imagine a future where Nvidia can grow much further when all of this is taken into account. Perhaps I have missed something important and I am just wrong about everything. I still have yet to see a convincing argument to disprove my thesis. Perhaps you can somehow change my mind here. Anyway, I thank you for taking the time to read this.
Credit to Michael Burry for publicly providing some of the data shown above. https://x.com/michaeljburry?s=21 $NVIDIA (NVDA.US)$ $Invesco QQQ Trust (QQQ.US)$ $Vanguard S&P 500 ETF (VOO.US)$ $Oracle (ORCL.US)$ $Cisco (CSCO.US)$ $KraneShares CSI China Internet ETF (KWEB.US)$ $Alibaba (BABA.US)$ $Tesla (TSLA.US)$ $Meta Platforms (META.US)$ $Amazon (AMZN.US)$ $Broadcom (AVGO.US)$ $Apple (AAPL.US)$
Disclaimer: Community is offered by Moomoo Technologies Inc. and is for educational purposes only.Read more


Comments (43)
to post a comment
29
1