Nvidia's 70% Growth Outlook May Be Too Conservative. How High Can It Go?

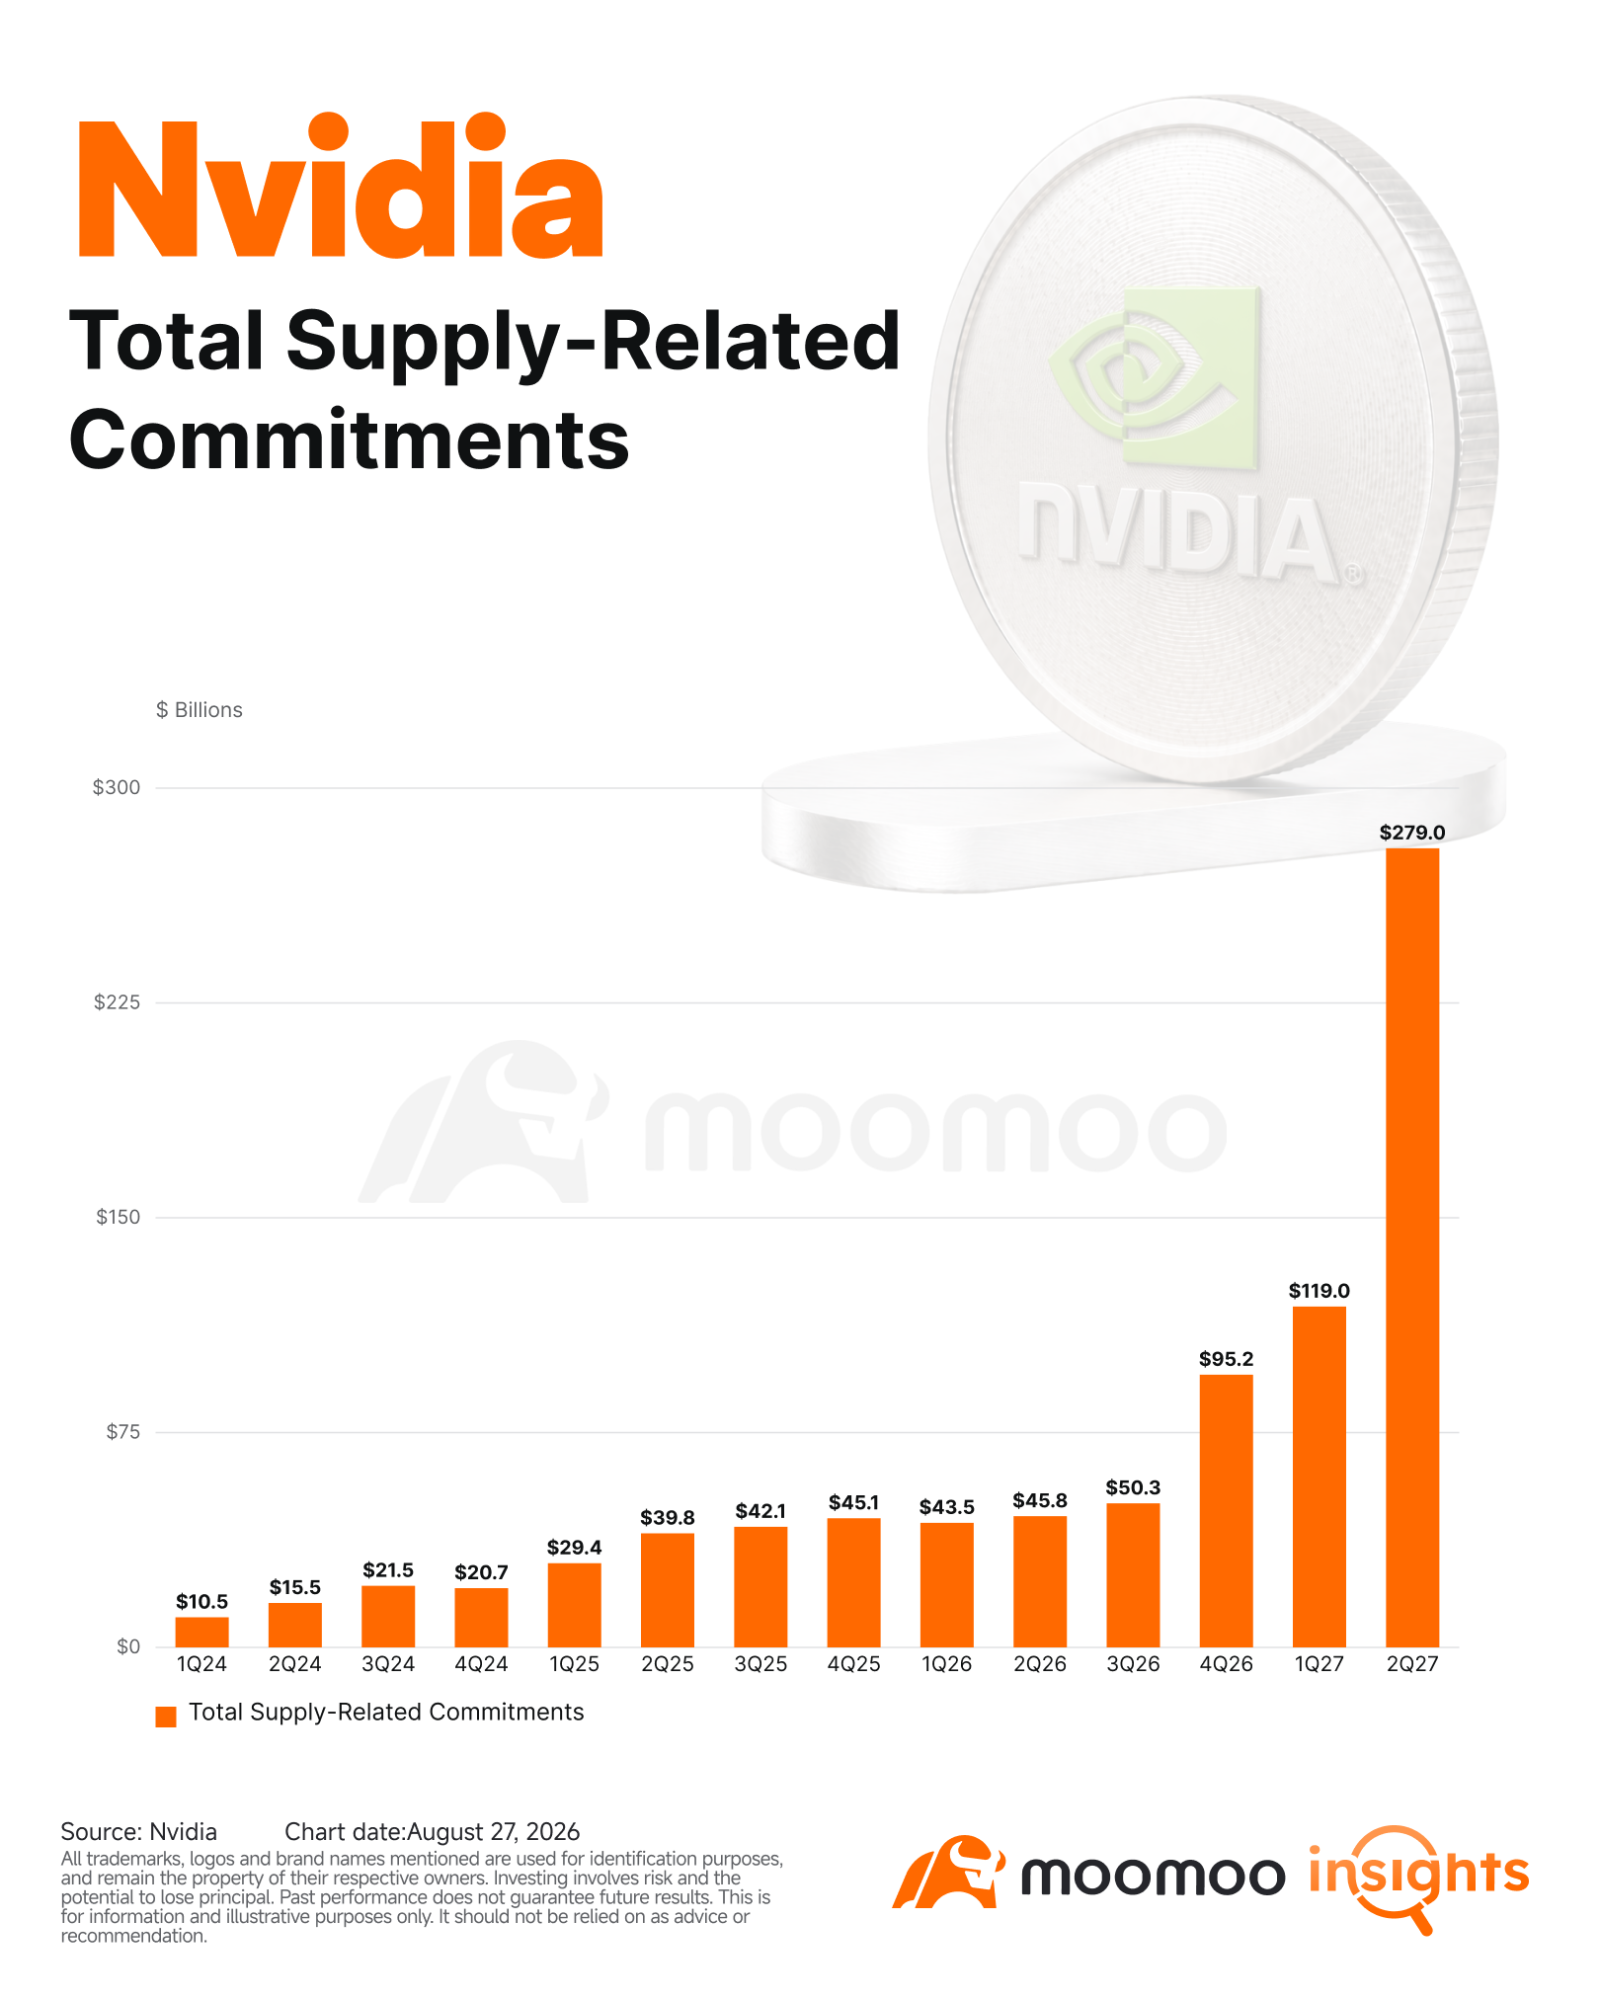
Nvidia's $279B Supply Commitments: Which AI Suppliers Are the Biggest Winners?
The biggest takeaway from $NVIDIA (NVDA.US)$ 's latest earnings is not just the quarterly beat. Management now expects ~70% revenue growth in CY27, and even that remains supply-constrained. Unconstrained demand could support more than 100% growth, while Rubin is expected to reach roughly 20% of revenue next quarter.
That shifts the key question for AI investors:
Who can remove Nvidia’s supply bottlenecks?
HBM: The Clearest Winner
Nvidia’s direct supply and capacity commitments have risen to roughly $279B, while broader commitments total about $366B. A large portion of the supply commitments is tied to memory.

Citi further noted that memory represents the majority of these commitments, especially HBM, with Nvidia already securing substantial supply visibility for the next several years.
More importantly, rising HBM prices are already affecting Nvidia’s margins. Gross margin is expected to bottom around 71%–72% before settling near 72%–73% in CY27.
That is strong evidence of supplier pricing power, not weak demand.
For now, HBM remains the most direct and highest-conviction AI supply-chain beneficiary.
Key names include:
Networking and Optics: More Content per AI System
Networking is another clear growth area.
Citi said Nvidia’s Data Center Networking revenue grew about 138% YoY, supported by NVLink, InfiniBand, Spectrum-X and the early rollout of Spectrum-6 for Rubin. As AI infrastructure moves toward rack-scale architecture, interconnect content per system continues to rise.
Morgan Stanley also highlighted that the biggest supply constraints over the past year have increasingly shifted toward:
Memory, storage, optics and CPUs.
Goldman Sachs viewed Nvidia’s outlook as constructive for digital semiconductor names including Broadcom and Marvell.
Key listed exposures include:
Advanced Packaging: A Hard Requirement for Rubin
Citi noted that Nvidia’s supply commitments also cover:
Wafers, CoWoS and substrates.
A faster Rubin ramp requires advanced packaging capacity to expand alongside GPU shipments.
Compared with HBM, pricing upside may be less obvious, but demand visibility remains very high. The clearest exposure is therefore the TSMC/CoWoS ecosystem.
Nvidia is also increasingly framing the opportunity around the entire AI Factory, not just GPUs. Management estimates that a 1GW Vera Rubin-based AI factory could represent roughly $40B of compute, networking, CPU and other infrastructure content.
That also supports power and data-center infrastructure, although the value chain is more fragmented.
Key listed exposures include:

What to Watch Next
This earnings report confirmed strong AI demand, but NVIDIA is paying a clear price for growth.
Gross margins are expected to fall to 74% in Q3 and bottom at 71-72% in Q4, driven by memory price hikes and Vera Rubin ramp costs. Management expects margins to recover to 72-73% after price increases in FQ1 2028.
Four key metrics to watch: whether Vera Rubin contributes ~20% of data center revenue in Q3; whether Q4 margins hold at 71-72%; whether post-price-hike margins recover to 72-73%; and whether the $279B in purchase commitments convert to revenue rather than inventory pressure.
The key takeaway:
When 70% growth is still supply-constrained, the most attractive beneficiaries are not every AI-related stock, but the bottlenecks Nvidia is willing to lock up hundreds of billions of dollars in advance—and still worries may not be enough.
Disclaimer: Moomoo Technologies Inc. is providing this content for information and educational use only.Read more


Comments
to post a comment
51
54