
AI Chips Aren't Done: A Semiconductor Reset, Not a Cycle Peak

Global semiconductor stocks have seen sharp volatility in recent days.
Samsung Electronics released very strong preliminary results, with second-quarter operating profit jumping roughly 19-fold year over year to KRW 10.4 trillion. In theory, that should have been positive for memory chips and the broader AI hardware supply chain. Instead, the market reacted in the opposite direction. Korean memory leaders such as Samsung and SK hynix sold off sharply, sentiment across Japanese and Korean technology stocks deteriorated, and the pressure quickly spread to U.S. equities.
On July 7, the $PHLX Semiconductor Index (.SOX.US)$ fell 4.65%, with memory stocks, semiconductor equipment names, and parts of the AI hardware supply chain all coming under pressure.
The issue was not that $Samsung Electronics (005930.KR)$ 's results were weak. The issue was that expectations had become too high. Over the past several months, investors had already aggressively priced in strong AI demand, rising memory prices, tight HBM supply, and a rapid earnings recovery across AI chips, HBM, memory, optical communications, and advanced packaging. Once Samsung's strong results were confirmed, investors chose to "buy the rumor, sell the news."
Still, this looks more like a momentum washout within a bull market than the end of the AI supercycle.
1. Why Did Good News from Samsung Turn into Bad News? The Key Issue Is "Peak Rate of Change"
Samsung's profit surge confirms that the memory industry is indeed recovering. But what the market is really worried about is whether the industry has already entered the fastest phase of its earnings recovery.
Morgan Stanley's view is representative of this concern. The firm believes the global memory chip industry is approaching a "peak rate of change." This does not mean the memory cycle is over. Rather, it means the pace of improvement in memory pricing, inventory normalization, and earnings upgrades may begin to slow.
The key concerns are:
- DRAM price growth may start to decelerate on a year-over-year basis;
- Inventory improvement may begin to flatten;
- EPS upgrades for the memory sector have already been substantial, leaving less room for further upward revisions.
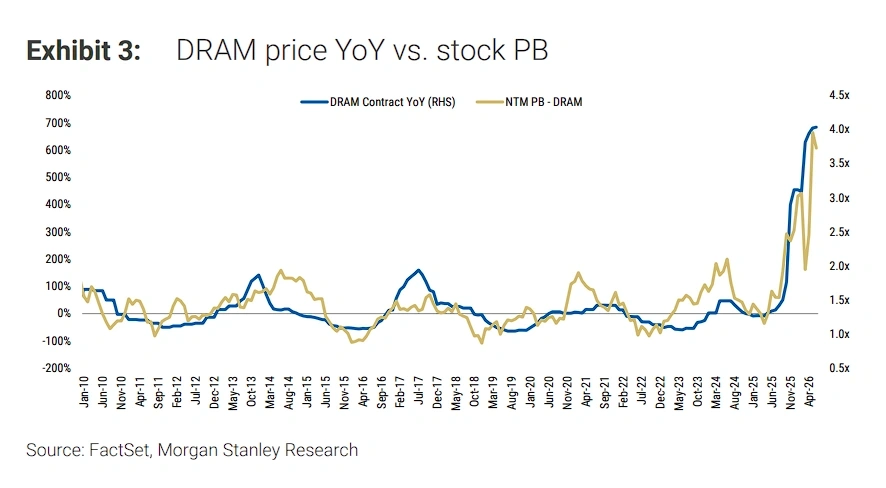
In other words, the market is not selling because investors believe the industry is falling into recession. It is selling because the best phase of the recovery may already be fully priced in.
That explains why Samsung's strong earnings triggered a selloff. For cyclical stocks, share prices often depend not only on whether earnings are rising, but on whether the pace of earnings growth can keep accelerating.
2. This Is Not a Collapse in AI Demand, but a Healthy Correction After Crowded Positioning
Although the SOX Index sold off sharply, it is still too early to conclude that the AI semiconductor cycle has ended.
The reason is simple: AI compute demand has not been disproven.
Bank of America's view is that global cloud and AI infrastructure capital expenditure could approach $1.5 trillion by 2027 and continue growing at a high rate. For hyperscalers, the priority remains securing compute capacity, not prematurely optimizing free cash flow.
More importantly, an AI data center is not just about GPUs. Building a large-scale AI data center also drives demand for:
– GPUs and AI servers;
– HBM and high-speed memory;
– Optical communications and networking equipment;
– Power infrastructure;
– Liquid cooling and thermal management;
– PCBs, ABF substrates, MLCCs, and advanced materials.
Therefore, even if memory stocks correct in the short term, the broader AI infrastructure buildout remains intact. The current pullback looks more like position clearing after a strong rally, rather than a sudden collapse in demand.
3. Goldman Sachs: The AI Bull Market Is Entering Its "Second Act"
Goldman Sachs' view is also important.
The firm believes the AI bull market has moved from its first stage into its second stage. The first stage was about buying GPUs and Nvidia. The second stage is about building "AI factories" — the full infrastructure stack around AI data centers.
Goldman Sachs is watching two key signals to determine whether the AI hardware cycle has peaked:
- Whether semiconductor and electronic component supply begins to significantly exceed demand;
- Whether the industry starts shifting from high-performance technologies toward lower-cost substitutes.
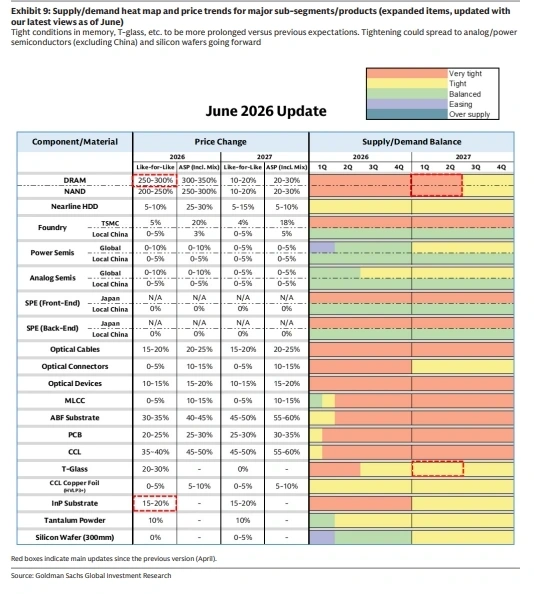
So far, neither signal has clearly appeared. Instead, shortages are spreading beyond GPUs and HBM into other parts of the supply chain, including optical communications, glass substrates, ABF substrates, copper-clad laminates, MLCCs, power management, liquid cooling, and advanced materials.
This means the AI trade is no longer just about Nvidia. It is spreading across the entire infrastructure value chain.
4. Nvidia's Resilience Shows the AI Trade Still Has a Core Anchor
Against the backdrop of a broad semiconductor selloff, $NVIDIA (NVDA.US)$ managed to close higher and hold near the $200 level, supported by its 200-day moving average. That is an important signal.
It suggests that investors are not abandoning the AI trade altogether. Instead, they are selling memory, equipment, and other high-beta names that had already rallied sharply, while continuing to hold the most important AI assets.
The options market also showed a bullish tilt. Nvidia call option volume was significantly higher than put option volume, and call premium accounted for a notably larger share of total premium. This suggests that some investors are still betting that Nvidia can hold key support levels and potentially break higher again.
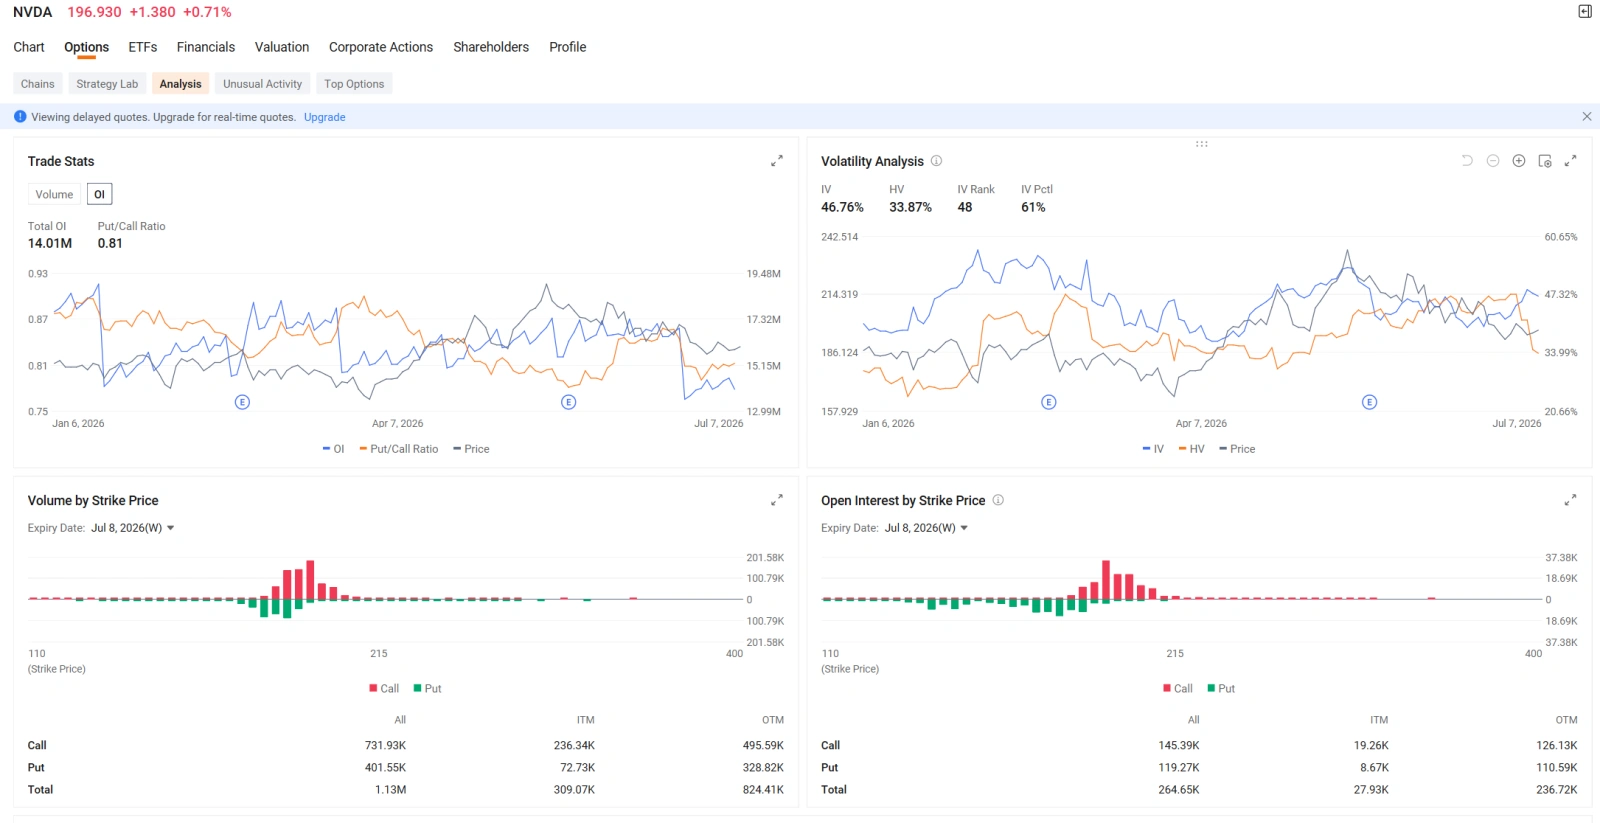
So the key message from the market is not "AI is over." It is this:
Investors are shifting from buying the entire semiconductor sector to buying the highest-conviction leaders.
5. SK hynix's July 10 ADR Listing: A Key Test for HBM Sentiment
Beyond Samsung's earnings, the next major event is $SK hynix (SKHY.US)$ 's ADR listing in the U.S. on July 10.
The significance of this event goes beyond the creation of another tradable security. It gives U.S. investors a more direct way to price one of the world's leading HBM companies.
SK hynix is one of the most important players in the global HBM supply chain and one of the most direct beneficiaries of AI memory demand. In the past, U.S. investors looking to trade the memory cycle mostly focused on Micron. With SK hynix's ADR listing, the market will be able to compare the three major memory producers more directly:
– SK hynix's leadership in HBM;
– Samsung's ability to catch up;
– Which company is more deeply tied to AI chip leaders such as Nvidia;
– Which company has stronger margin leverage.
As a result, SK hynix's ADR listing will become an important sentiment test for the HBM trade.
If the ADR performs well after listing, it would suggest that investors have not given up on AI memory, but are merely selling the more cyclical parts of the memory trade.
If it performs poorly, it would suggest that risk appetite toward the entire memory supply chain remains under pressure.
6. Rotation into Biotech: Investors Are Moving from Crowded Winners to Less Crowded Growth Areas
At the same time, capital has also begun rotating into healthcare and biotechnology.
The logic is straightforward. After a strong rally in semiconductors and AI hardware, positioning has become crowded. Some investors are now looking for areas with lower valuations, lower positioning, and more potential catalysts.
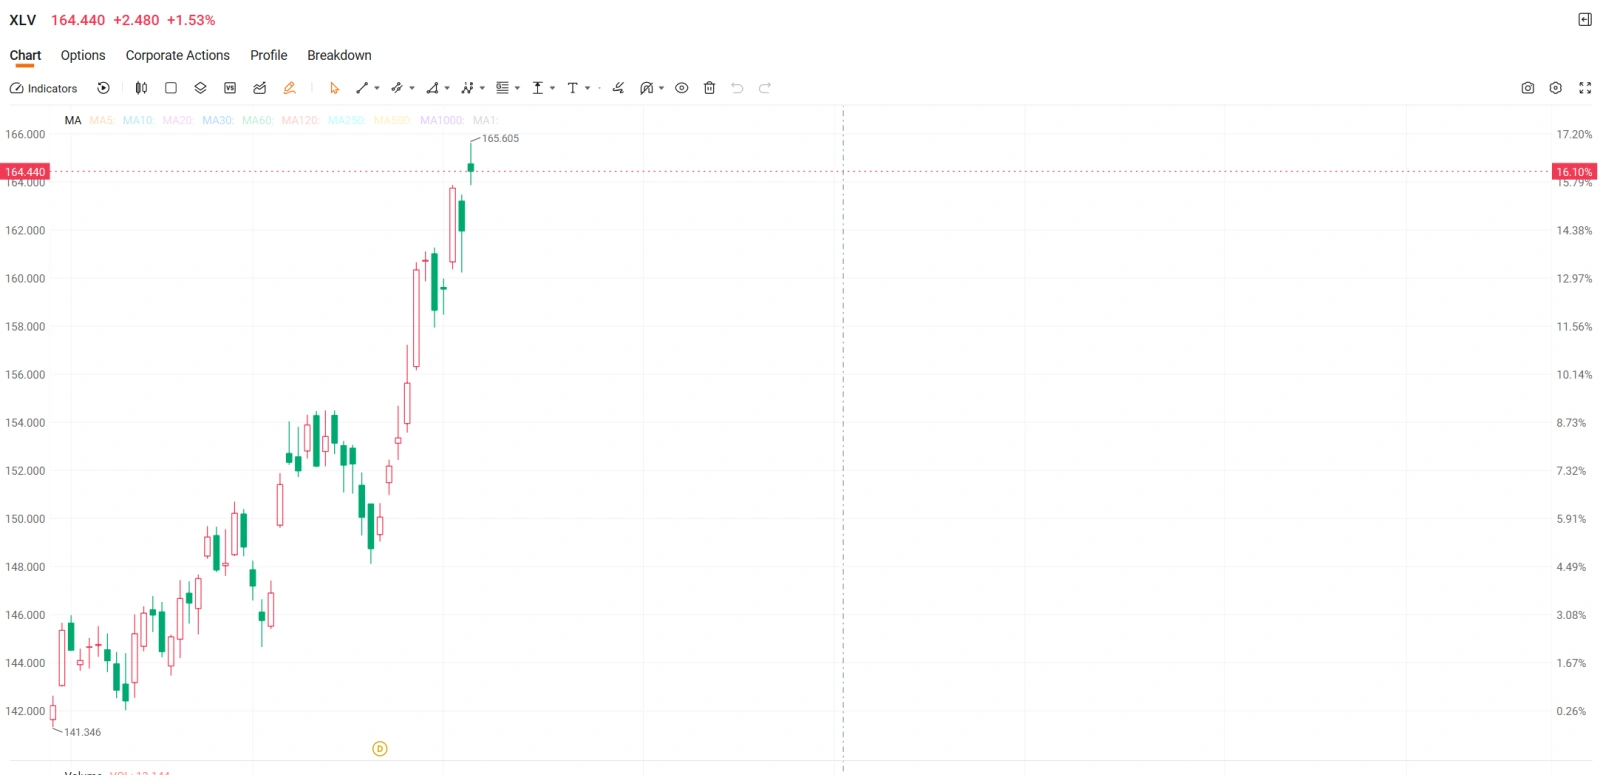
Biotech has recently benefited from several supportive factors, with $The Health Care Select Sector SPDR® Fund (XLV.US)$ , $iShares Biotechnology ETF (IBB.US)$ , and $SPDR S&P Biotech ETF (XBI.US)$ all reaching new highs:
– Rate-cut expectations are improving the financing environment;
– Large pharmaceutical companies have rising demand for acquisitions;
– GLP-1 weight-loss drugs remain one of the key themes in healthcare;
– FDA approvals, clinical trial data, and M&A deals can act as powerful catalysts;
– Biotech has lagged for several years, leaving more room for valuation recovery.
Therefore, strength in biotech does not mean the AI trade is over. It is more likely a rotation within a broader bull market.
On one side, AI hardware is going through a momentum reset. On the other, capital is rotating into less crowded growth sectors.
7. The Real Test Comes Next Week: TSMC and ASML Earnings
Samsung was the sentiment trigger. SK hynix's ADR listing will be a test of HBM sentiment. But the real drivers of the next move in semiconductors will be TSMC and ASML's earnings next week.
TSMC will help validate AI chip demand and the strength of advanced packaging. Key areas to watch include:
– Whether AI-related revenue continues to grow rapidly;
– Whether demand for 3nm and 5nm advanced nodes remains strong;
– Whether CoWoS advanced packaging capacity remains tight;
– Whether margin guidance remains stable;
– Whether capital expenditure remains high or is revised upward.
If TSMC continues to signal strong AI demand, the market may quickly reinterpret the current semiconductor pullback as a healthy rotation.
ASML will help validate the semiconductor equipment cycle and global fab capital spending. Key areas to watch include:
– New orders;
– EUV order strength;
– Whether memory customers are resuming capacity expansion;
– Whether logic chip customers remain willing to expand;
– Management's view on 2026 and 2027 capital expenditure.
If ASML's orders are strong, equipment stocks could recover. If orders disappoint, the equipment supply chain may remain under pressure.
Conclusion: The AI Trade Is Not Over, but It Has Become More Difficult
The current semiconductor correction should not be viewed simply as the end of the AI cycle.
A more reasonable interpretation is this:
After a major rally, the AI hardware supply chain is going through a normal momentum washout and valuation reset.
Samsung's earnings-triggered selloff shows that investors are worried about a peak rate of change in memory. The sharp decline in the SOX Index shows that crowded trades are being unwound. But Nvidia's resilience also shows that core AI assets are still attracting support.
There are now three key events to watch:
1. SK hynix's ADR listing on July 10
This will test whether HBM assets can receive a fresh round of pricing from U.S. investors.
2. TSMC earnings next week
This will validate AI chip demand and advanced packaging momentum.
3. ASML earnings next week
This will validate semiconductor equipment orders and the capital expenditure cycle.
If these signals are strong, the current pullback will likely be seen as a healthy rotation within a bull market.
If they are weak, the semiconductor sector may face a deeper valuation reset.
For investors, the key question is no longer simply whether AI is still working. The real question is:
Which companies have real orders, real earnings, and real cash flow?
The semiconductor trade has moved from a broad-based rally into a more selective phase. The AI theme remains intact, but the market is increasingly favoring companies with greater earnings visibility. At the same time, less crowded growth areas such as biotechnology may become an important source of rotation and portfolio diversification.
Disclaimer: Moomoo Technologies Inc. is providing this content for information and educational use only.Read more


Comments (8)
to post a comment
44
43