Broadcom sinks despite earnings beat: Is the AI story fading?

CoreWeave vs. Nebius: Both Promising, But Who's Better?
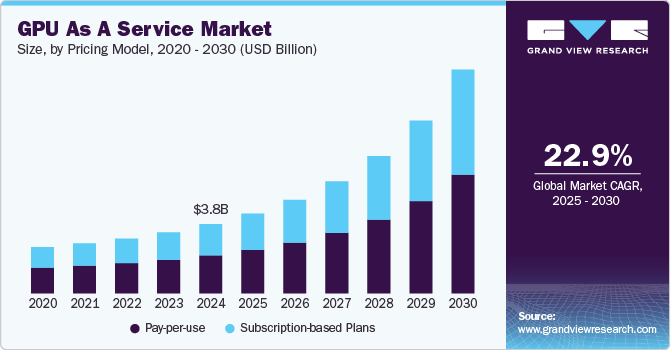
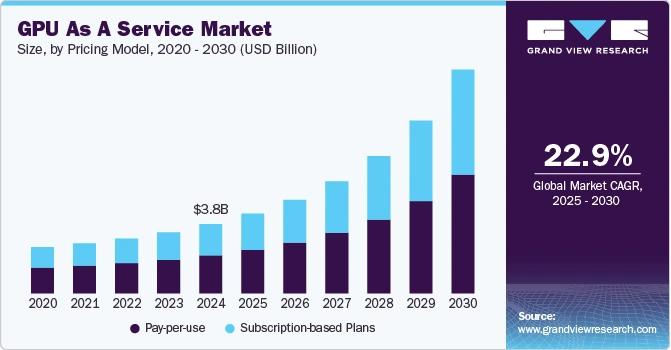
As AI computing demands continue to rise, companies and cloud providers often turn to GPU rentals when their own resources fall short or building in-house capacity becomes too costly. "AI Neocloud" emerged in response to this trend. This new cloud service provider specializes in AI-focused solutions, prioritizing GPU-centric data centers. According to Grand View Research, the GPU-as-a-Service market is projected to grow at a compound annual rate of 22.9% over the next five years.
The leading Neocloud providers currently include CoreWeave, Crusoe, Nebius, Lambda Labs, and Applied Digital, with CoreWeave being the largest. Nvidia has supported the rapid growth of several AI Neoclouds through direct investments and substantial GPU allocations.
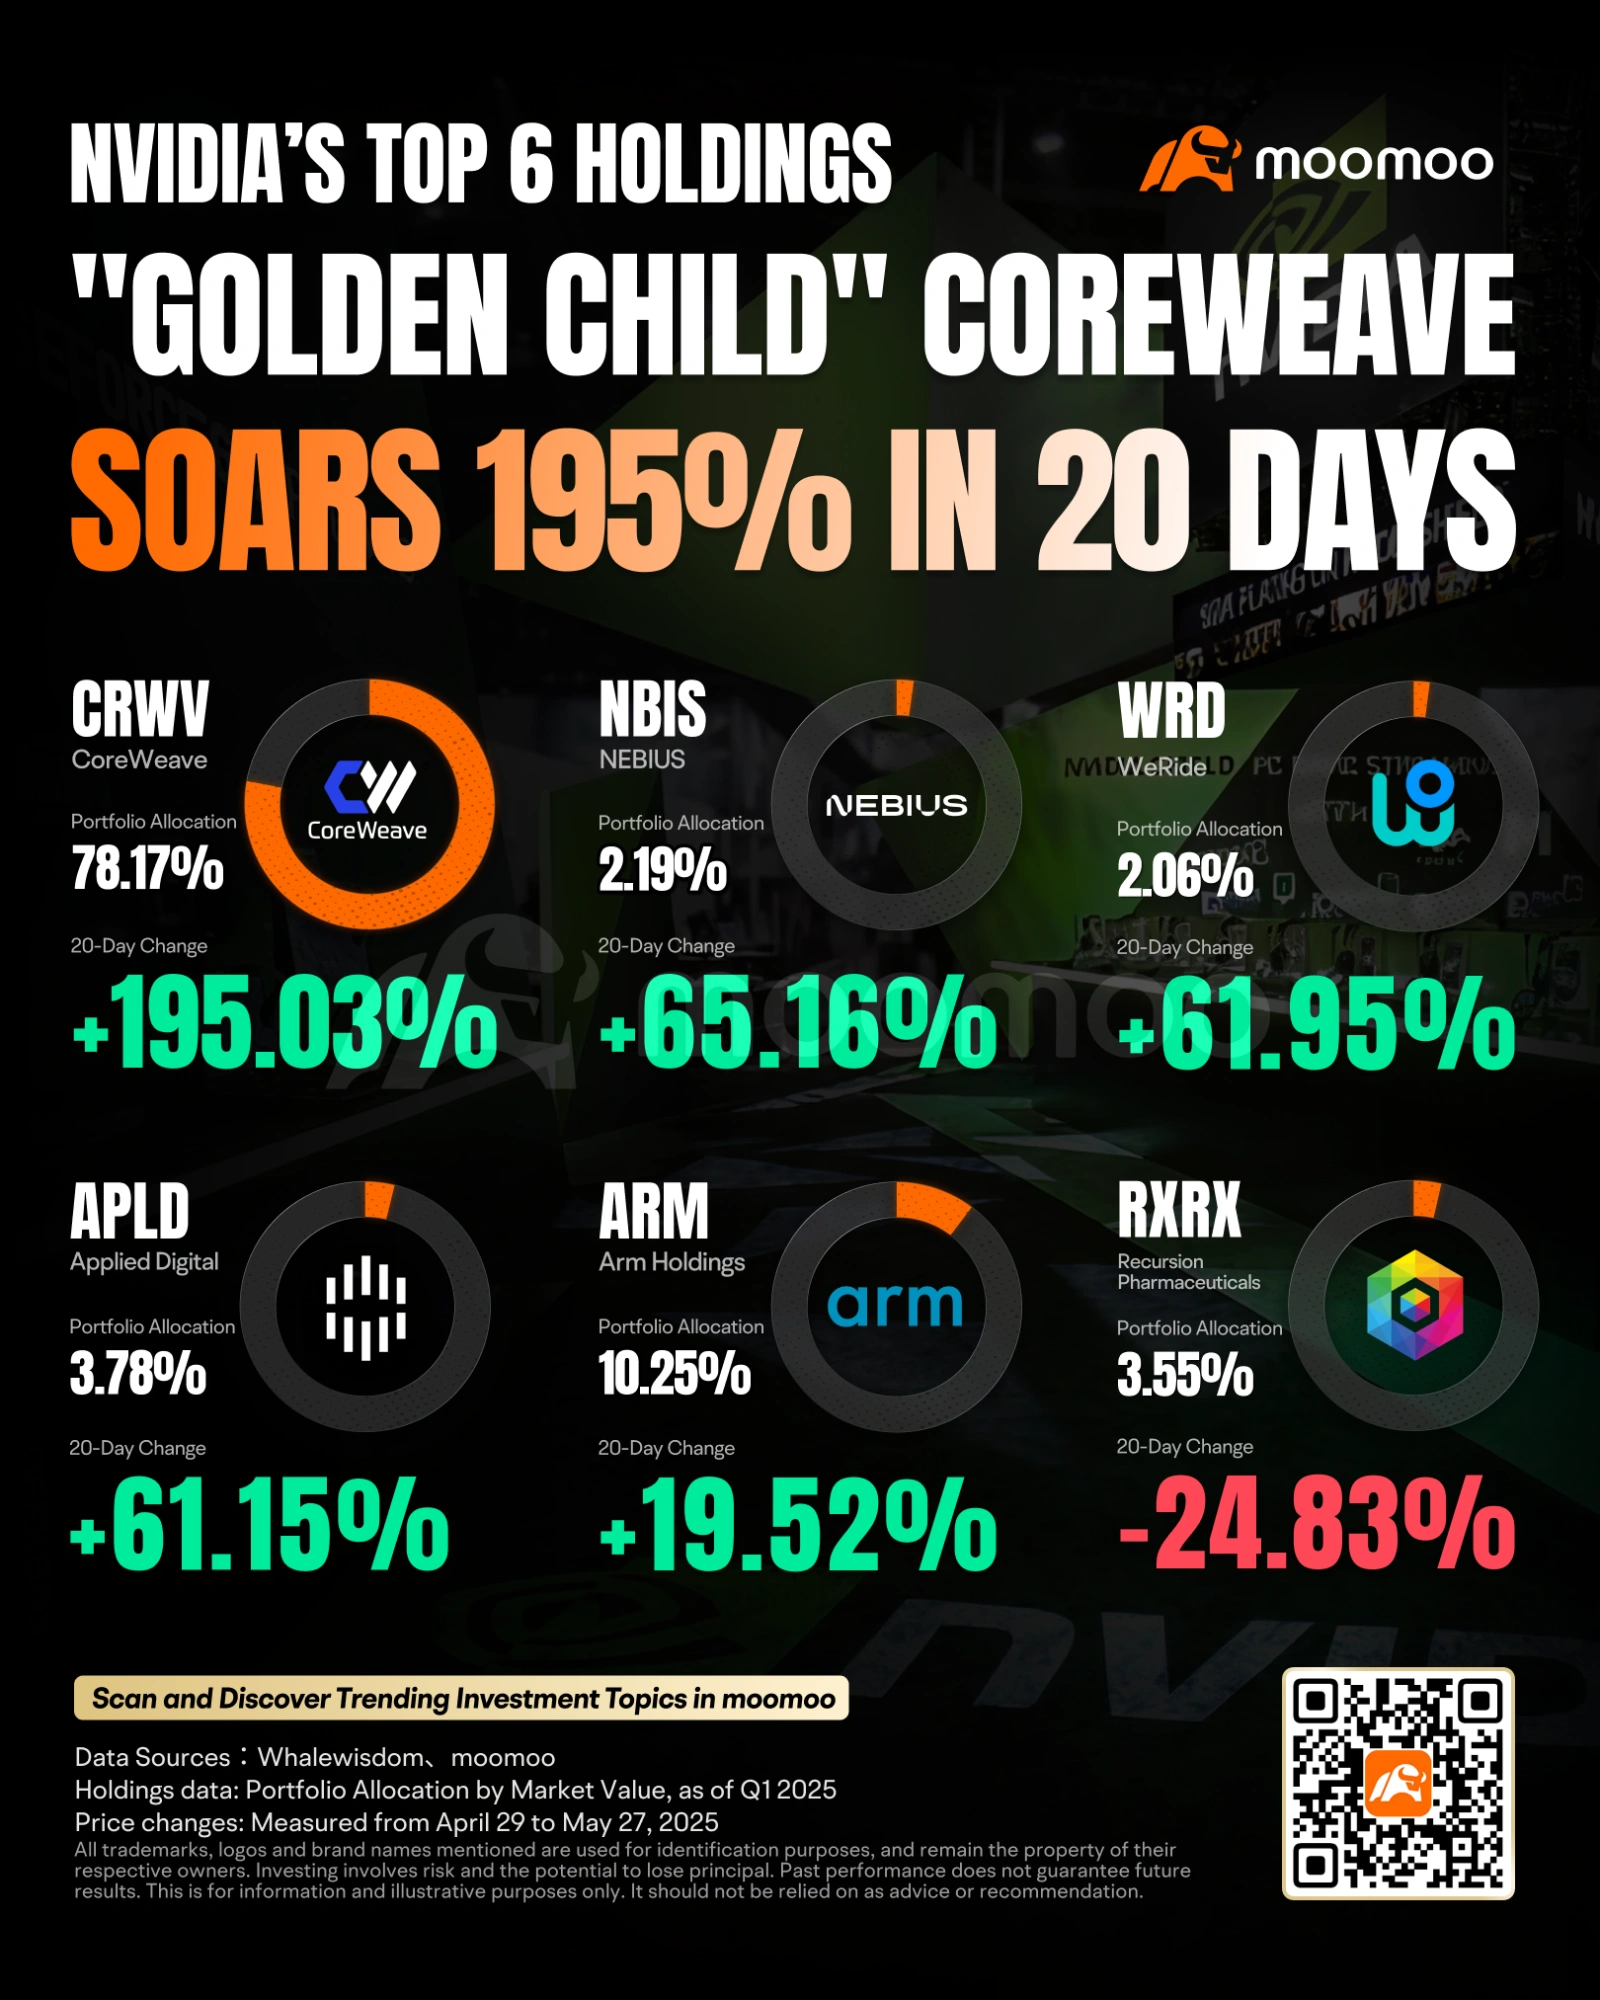
Since its IPO in late March, CoreWeave's stock has surged 217%, with a 195% increase in the last 20 trading days alone. This rally was driven by several catalysts, including raised revenue guidance, a new contract with OpenAI, successful issuance of $2 billion in bonds, and disclosure of Nvidia's stake in the company.
The Secret Sauce: Nvidia's "Unlimited" Support and GPU Access Ensure Competitive Edge
Based on the Q1 13F filing from mid-May, holdings include 24.18 million shares of CRWV, 7.7 million shares of APLD, and 1.19 million shares of NBIS. At recent closing prices, these positions are valued at approximately $900 million, $43 million, and $25 million, respectively.
Nvidia's investment in Coreweave occurred in two rounds:
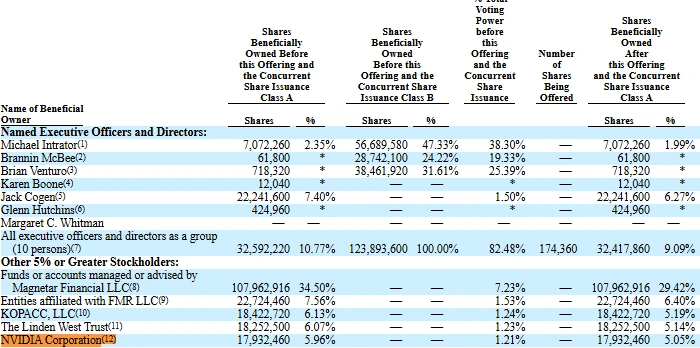
1. April 2023: $100 million for a 4% stake (17,932,460 shares before IPO)
2. Coreweave's IPO (expected 2025): $250 million as an anchor investor for 6.25 million shares
This brings Nvidia's total Coreweave holdings to 24.18 million shares, matching the 13F disclosure. No additional shares were acquired post-IPO.
Simultaneously, Nvidia is a customer of CoreWeave's services. In early 2023, Nvidia committed to paying CoreWeave $1.3 billion over four years to lease back its own chips, with the contract running until August 2027.
Nvidia's support for CoreWeave can be seen as a strategic move. As traditional cloud giants (AWS, Microsoft Azure, Google Cloud) accelerate development of their own AI chips to reduce dependence on Nvidia GPUs, Nvidia aims to build a "second cloud ecosystem" through CoreWeave. This ensures Nvidia's GPUs maintain a central role in AI infrastructure.
By prioritizing the supply of latest chips to CoreWeave (e.g., GB200 NVL72 available 5-8 months earlier than competitors), Nvidia leverages CoreWeave's market expansion to boost chip sales. A more diverse customer base also mitigates Nvidia's risks related to purchasing power and cycles.
Priority access to Nvidia's scarce GPU products is a key attraction for customers. However, the team's technical expertise is equally crucial.
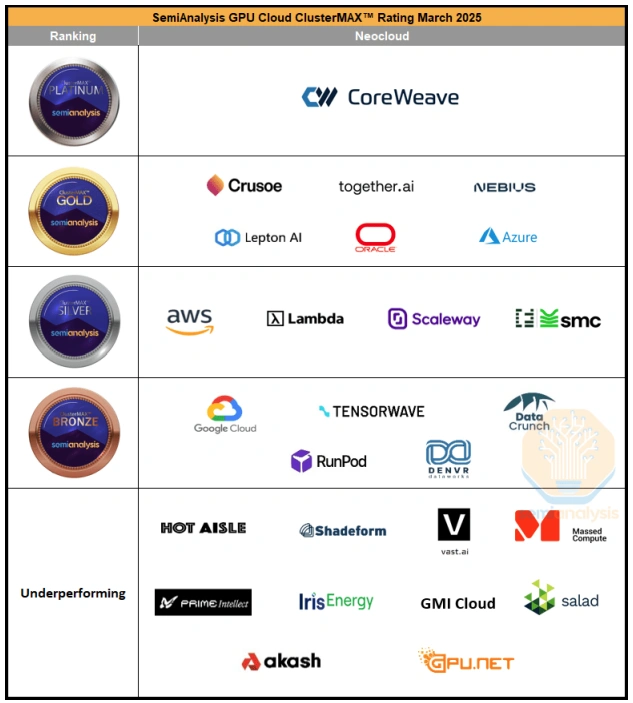
SemiAnalysis evaluated GPU cloud providers across multiple dimensions, including security, lifecycle management, technical expertise, reliability, scheduling systems, storage performance, network performance, health monitoring, pricing models, and technical partnerships. Providers were ranked into five tiers: Platinum, Gold, Silver, Bronze, and UnderPerform. CoreWeave exclusively occupies the top Platinum tier. Nebius shares the Gold tier with Oracle and Microsoft Azure, while Applied Digital is not listed in the rankings.
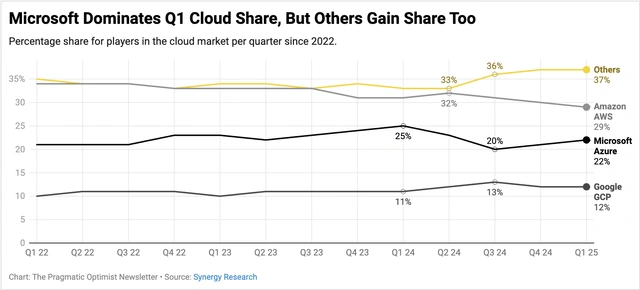
Superior service and competitive pricing ensure that neoclouds can survive and potentially gain increasing market share in the face of competition from traditional cloud giants. In the past two quarters, emerging cloud providers like CoreWeave, categorized as "Others," have shown growth rates surpassing the overall cloud market.
Compared to Nebius: Much Larger Scale, but Higher Client Concentration and Financial Pressure
In terms of scale, CoreWeave significantly outpaces Nebius, with approximately 10 times more GPUs. CoreWeave has contracted 1.6GW of power, about four times its current operational capacity. However, Nebius is also expanding rapidly. Their 2025 target is 35,000-60,000 GPUs, with a mid-term goal of 240,000 GPUs, requiring 240MW of power. This represents about 15% of CoreWeave's contracted power capacity.
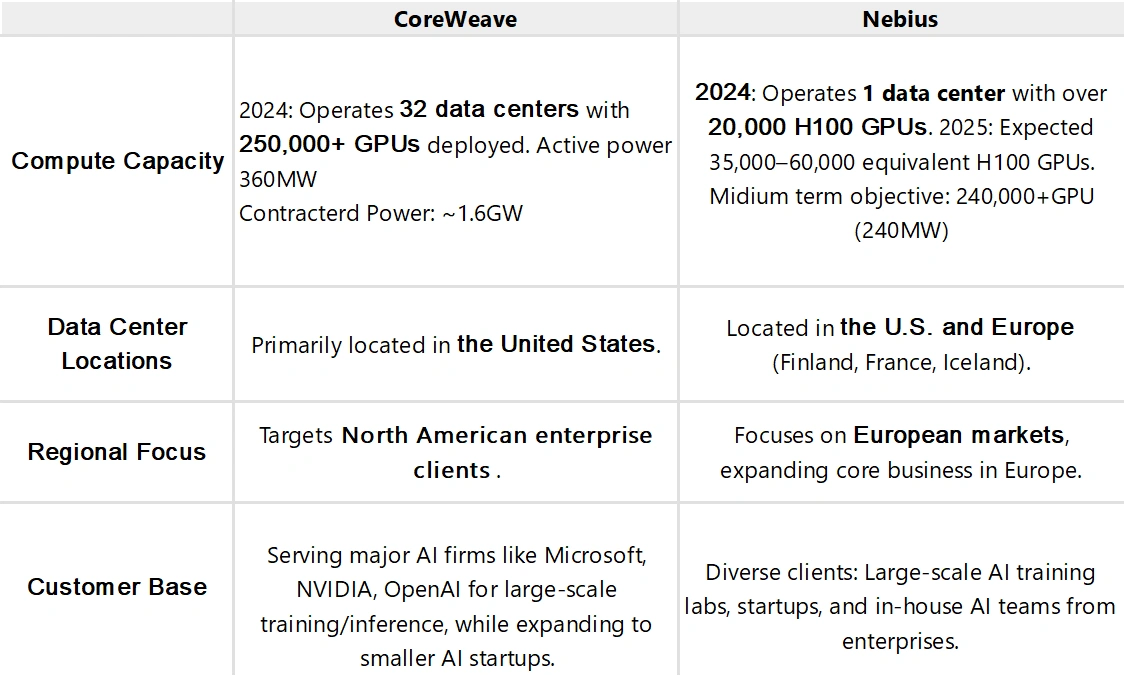
CoreWeave's large client deals boost GPU utilization, secure revenue, and provide a basis for infrastructure financing. However, this also poses a risk of high customer concentration. Delays in contract renegotiations, regulatory issues, or budget adjustments from a major client could significantly impact earnings, capital expenditure deployment, and financing prospects.
While OpenAI increased its contract with CoreWeave by $4 billion to a total of about $16 billion, this may only cover a few years of revenue. The future demand from OpenAI is uncertain, especially after their joint venture with Oracle (Project Stargate) becomes operational.
Remaining performance obligations (RPO) reflect unrecognized contract revenue. As of Q1 2025, this figure was $14.7 billion, down from $15.1 billion at the end of 2024. Although CoreWeave noted that Q1 figures exclude the new $11.9 billion OpenAI contract, questions remain about growth from other clients.
CoreWeave is working to mitigate this risk. The May acquisition of Weights & Biases (with 1,400 AI-using clients) signals a move towards the long-tail enterprise adoption sector.
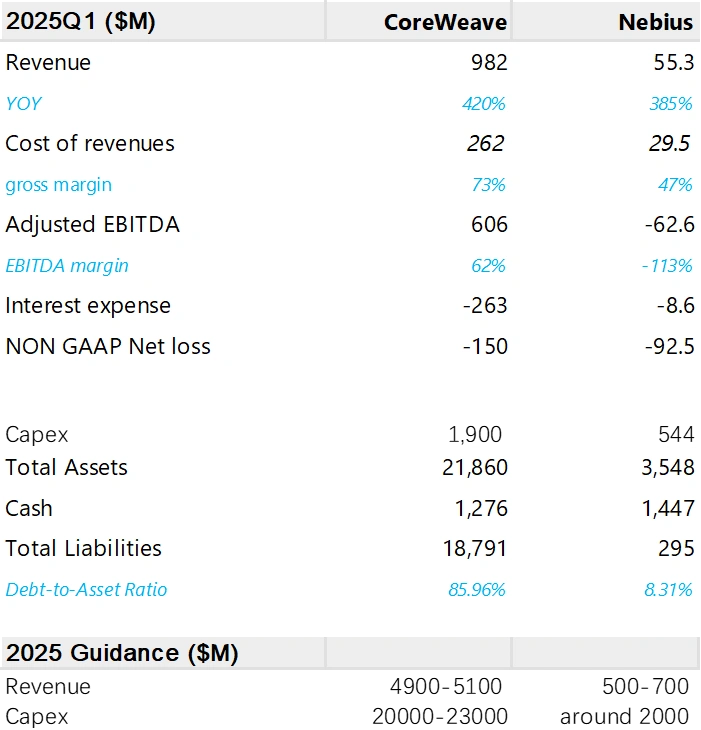
Despite CoreWeave's faster revenue growth and higher EBITDA margins, the company faces significant interest expenses, accounting for 27% of Q1 revenue. While its total debt of about $8.8 billion isn't excessive, the interest rates on its debt are notably high, with term loans starting at 9-10%.
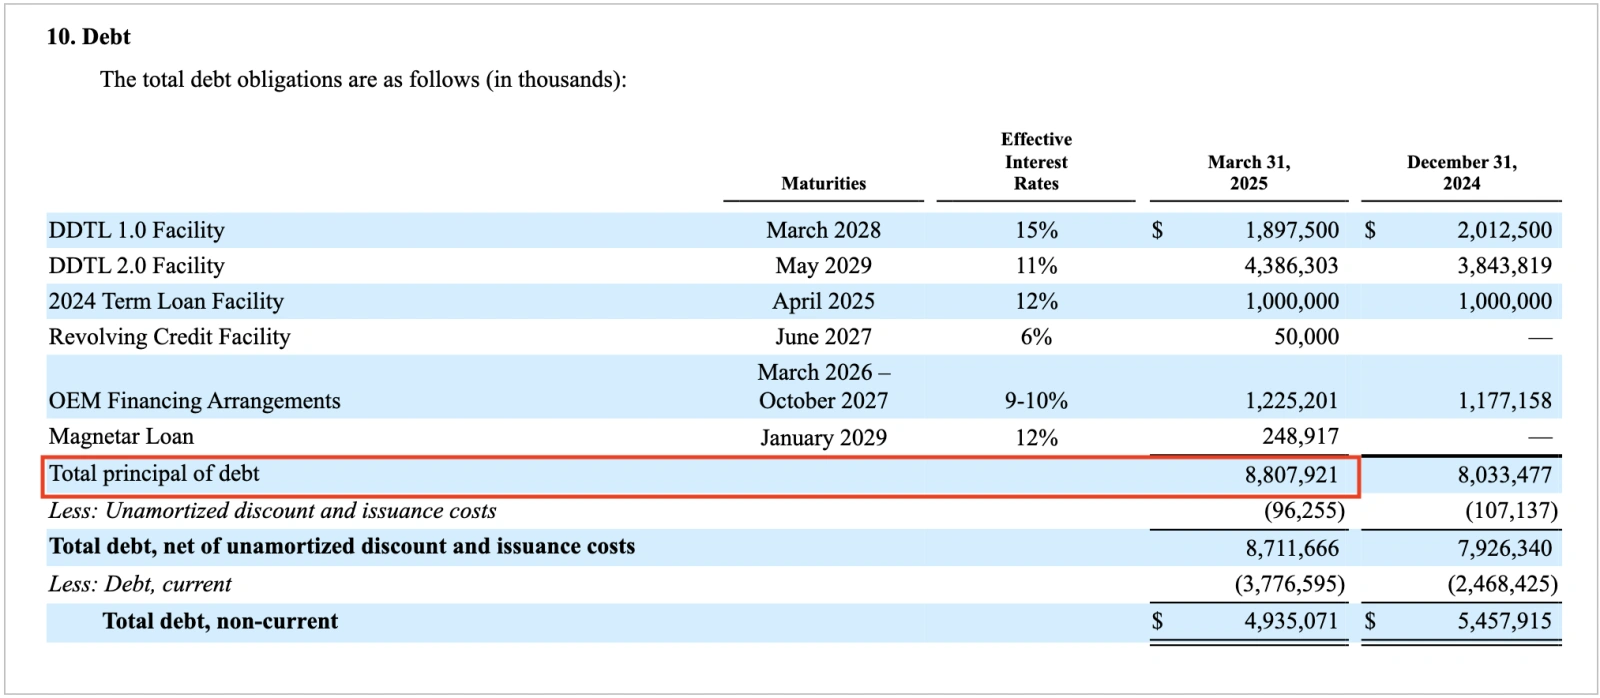
Given CoreWeave's massive capital expenditure plan of $20-23 billion for 2025, coupled with its limited cash reserves and high interest expenses, the company may face a funding gap of $15-20 billion. This could necessitate substantial new debt and potential shareholder dilution.
As for Nebius, its smaller client base results in more revenue from on-demand services, leading to lower overall profit margins. The lack of large customers may slow its growth. However, as it builds reputation and customer loyalty, its revenue stream could become more predictable.
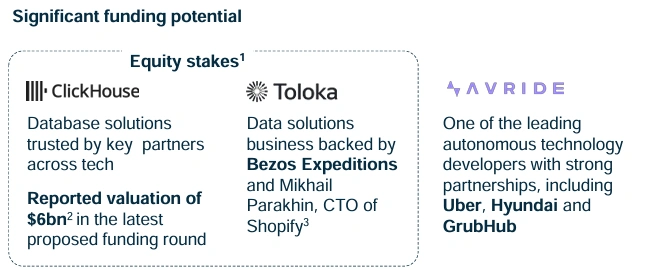
Beyond GPU services, Nebius has several controlling interests that might offer upside potential in the future, including Avride, Toloka, TripleTen, and ClickHouse.
Risk warning: CoreWeave's current public float is extremely small, with daily turnover often exceeding 100%. The RSI has been in overbought territory for an extended period, suggesting potential speculative behavior.
Disclaimer: Moomoo Technologies Inc. is providing this content for information and educational use only.Read more


Comments (4)
to post a comment
45
89