All Eyes on Nvidia Earnings as the AI Trade Seeks Fresh Momentum

AI Era's Big Winners: A Fundamental Overview of Five American PCB Manufacturers
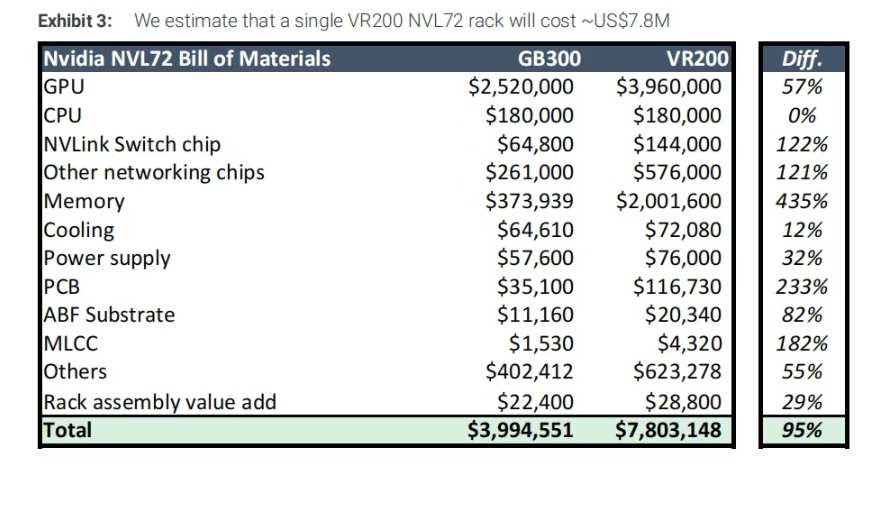
A previous bill-of-materials (BOM) teardown by Morgan Stanley revealed that the ODM (Original Design Manufacturer) procurement average selling price for Nvidia’s next-generation Rubin VR200 rack has reached $7.8 million, nearly doubling from the $3.99 million for the previous-generation GB300 rack. Notably, the PCB value in the VR200 rack stands at $116,700, a staggering 233% year-on-year increase compared to the $35,100 in the GB300 rack—the second-highest growth rate only behind memory chips. The PCB value in the next-generation Kyber rack is expected to surge even further. As process complexity increases, PCB manufacturing precision is approaching semiconductor-grade levels, leading to a widespread rise in ASPs.

Beyond the supply-demand gap in North America's domestic high-end AI high-speed PCB capacity, the PCB sector's boom is also driven by underlying policy factors. The U.S. CHIPS and Science Act, tariffs, and the relocation of cloud providers' supply chains have all boosted the local PCB industry. $Amazon (AMZN.US)$ 's AWS, $Alphabet-A (GOOGL.US)$ , and $Meta Platforms (META.US)$ are mandating higher proportions of local hardware procurement to bypass overseas delivery, tariff, and certification issues. This has led to longer delivery cycles and sustained price increases.
Finally, core manufacturers possess significant technological moats. Companies like TTM Technologies and Rogers Corporation hold distinct advantages in specialized high-end product segments.
Who Are the Key Players?
As the largest domestic PCB manufacturer in North America and a top-five global player, TTMI controls 30% of North America's high-end PCB capacity. With 23 factories across the U.S., Mexico, and Asia, it is a platform company on the U.S. stock market covering AI high-speed boards, military/aerospace RF PCBs, and automotive PCBs.

TTMI holds strong domestic advantages with core customers. Its AI computing clients include $NVIDIA (NVDA.US)$ , Google, Meta, Amazon, and $Supermicro CDR (CAD Hedged) (SMCI.CA)$ , with local North American delivery. In the military and aerospace sector, it supplies $Boeing (BA.US)$ , $Lockheed Martin (LMT.US)$ , and $RTX Corp (RTX.US)$ , serving as the major U.S. defense PCB supplier with high barriers to entry and stable, high gross margins.
Rogers focuses on high-frequency PTFE RF substrates and RF/microwave PCBs, serving as a core material supplier for AI optical modules, 5G base stations, and military radars. It holds a global monopoly on PTFE high-frequency substrates and is irreplaceable in North American aviation/defense RF PCBs. There is rigid demand for its high-frequency boards in AI 1.6T optical modules, and the value per unit continues to rise with bandwidth upgrades.

A North American cloud provider server ODM that manufactures its own M8/M9 high-speed PCBs. It is a Tier-1 supplier for Meta, AWS, and Nvidia's computing hardware.

The company specializes in military and aviation-specific PCBs, including airborne high-reliability boards and aerospace micro-assembly circuits. It is driven by pure military demand, completely insulated from consumer electronics cycles, and offers strong defensive attributes.

An EMS (Electronic Manufacturing Services) provider offering PCB contract manufacturing. It is tied to North American medical, industrial, and small-batch custom AI computing boards, focusing on high-reliability specialty PCBs with high customer stickiness.

Beyond Primary PCB Suppliers: Related Companies in the Supporting Supply Chain
Materials:
1. Copper Clad Laminate (CCL): $Panasonic Holdings (6752.JP)$'s Megtron series high-speed CCL industry grading codes, M8/M9, have become the global standard for categorizing ultra-low-loss PCB substrates.
3. $Corning (GLW.US)$: A leader in upstream PCB substrate glass fiber, supplying high-end electronic glass fiber cloth and quartz cloth, which are core raw materials for M9 high-speed CCL.
4. $Linde (LIN.US)$ & $Air Products & Chemicals (APD.US)$: Suppliers of specialty process gases and etching gases for PCB manufacturing.
Equipment:
1. $MKS Inc (MKSI.US)$ (Core Equipment Leader): Its wholly-owned subsidiary brand, ESI, is the global leader in high-end PCB laser drilling equipment and the only major PCB laser processing equipment manufacturer on the U.S. stock market.
2. $KLA Corp (KLAC.US)$: Following its acquisition of Orbotech, it has become a global oligopoly in optical inspection equipment for PCBs and IC substrates.
3. $Amtech Systems (ASYS.US)$: A small-cap Nasdaq-listed PCB process equipment manufacturer providing automated equipment for PCB plating, surface treatment, and lamination, serving small-to-mid-sized high-end PCB makers in North America.
The recent rebound in the PCB sector has been relatively weak. However, considering the significant increase in the value of PCBs within the entire AI rack, the earnings of related companies may gradually materialize in the future.
Disclaimer: Moomoo Technologies Inc. is providing this content for information and educational use only.Read more


Comments (5)
to post a comment
69
60