
$100 Options Club | An FOMC That Might Hike, and AI Infra Gets Sold After Leopold Aschenbrenner Reload
Hey mooers, welcome to this week's $100 Options Trading Club. Every week we spot low-cost options setups worth watching, break down the logic, and always lay the risk out in the open. Everything below is for educational and illustrative purposes only; the strikes and premiums are examples to show how the ideas work, not recommendations to trade. Prices are approximate and move constantly.
Setup 1: The FOMC — a hike tomorrow that nobody is hedging (SPY)
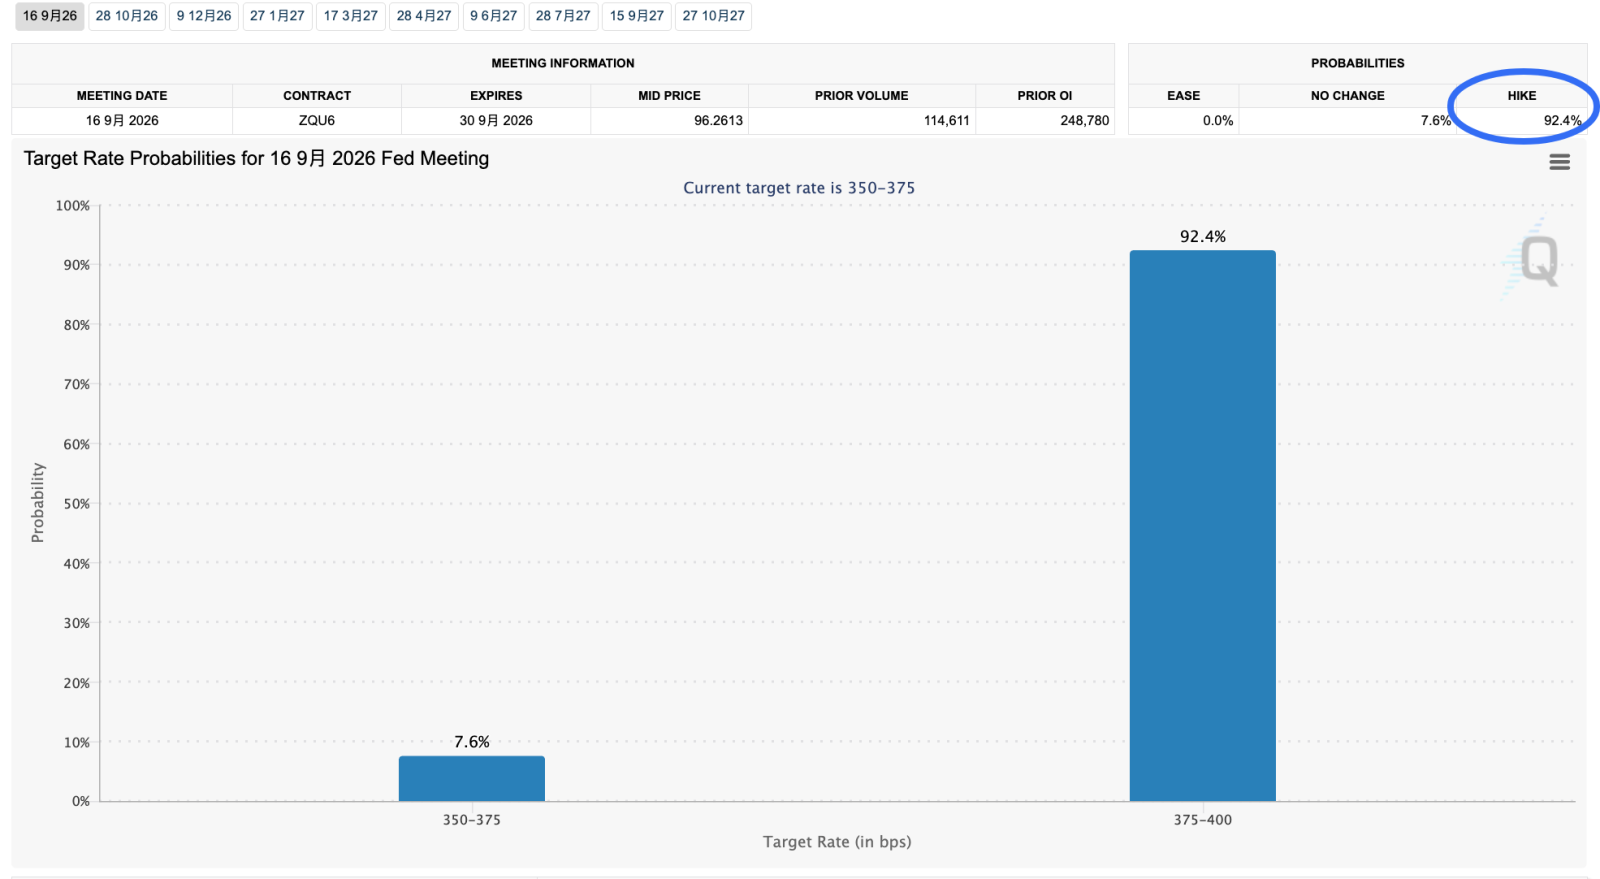
Tomorrow's FOMC is the rare meeting where the Fed is expected to raise 25bp, where markets put it over 90%. Under Chair Warsh the reaction function has flipped to "hike unless the data says pause," after a hot jobs print and core CPI running near double the pace needed to hit 2%.

The 9/18 expected move of $SPDR S&P 500 ETF (SPY.US)$ is only about ±$9.89, or ±1.3%, for a week that contains a live FOMC (that expiry's IV is ~19.6%; the ATM straddle is ~$10.39, ≈ ±1.37%). Realized volatility is running just ~9–10%.

The hike itself is so fully priced that the whole FOMC week costs barely 1.3% of protection. Cheap insurance before a top-tier event is an opportunity. The unpriced risk isn't the hike — it's the path: markets already price about 2.5 more hikes, so the surprise lives in the dot plot and Warsh's tone.
The bear case — Long SPY Put (this Fri 9/18, ~2.5% OTM, cost ~$130)
With vol this compressed, a ~$1 put only needs the index ~2–3% lower to be in play. Logic: if the dot plot confirms a genuine tightening cycle (not "one and done"), a 10-year yield pressing 5% plus stretched equities can snap back fast. (Reference: the 9/18 743-put trades ~$1.38; ~740 sits near ~$1. Note downside skew makes puts pricier, so the $1 put sits further out than the $1 call.)
Try moomoo Strategy Lab on SPY>>> to analyze breakevens, P/L thresholds, and budget your cost before you strategize.

for illustration only, not investment advice
The bull case — Long SPY Call (this Fri 9/18, ~1.2% OTM, cost ~$100)
A roughly 1%-OTM weekly call is about a buck. Logic: the hike is baked in, so a Warsh who signals "recalibration, one and done" removes the feared tail — a classic relief melt-up in a low-vol tape. (Reference: the 9/18 770-call trades ~$1.04, the 772-call ~$0.66.)

for illustration only, not investment advice
Setup 2: The chip complex just broke — play the theme cheaply, and mind the skew (SMH)
Per CNBC, Leopold Aschenbrenner's Situational Awareness is back buying options on the AI-infrastructure / memory theme: $SK hynix (SKHY.US)$, $SanDisk (SNDK.US)$, $Bloom Energy (BE.US)$, and $CoreWeave (CRWV.US)$.
While the AI-infrastructure and memory trade got hit hard, and the whole semiconductor complex went with it: $VanEck Semiconductor ETF (SMH.US)$ closed down about 4.75%.

Two things make SMH interesting this week:
1. You get the entire chip complex at ~39% IV, versus ~59% for a single name like AMD. Same theme, far less volatility tax on your ticket.
2. The downside skew is steep. Out-of-the-money puts carry much richer IV than out-of-the-money calls (roughly: -5% put IV ~43%, versus +5% call ~39%). The market is paying up for protection. That argues for using spreads instead of buying naked OTM puts and it makes the call side relatively cheap.

for illustration only, not investment advice
The bear case — Bear Put Spread (this Fri 9/18: buy a ~3% OTM put, sell a ~5% OTM put)
Net debit ~$1.40 (cost ~$140). The spread is $10 wide, so max profit ~$8.60 (~$860) if $VanEck Semiconductor ETF (SMH.US)$ closes around 5% lower; breakeven roughly 3.3% below spot; about a 6:1 payoff. Logic: if the de-grossing continues through a hawkish FOMC, semis lead lower. Using a spread means the pricier further-OTM put you sell (higher IV) helps fund the closer put you buy, you turn the steep skew in your favor instead of overpaying for a naked put.
Try moomoo Strategy Lab on SMH>>> to analyze breakevens, P/L thresholds, and budget your cost before you strategize.

for illustration only, not investment advice
The bull case — Call Debit Spread (this Fri 9/18: buy a ~3% OTM call, sell a ~5% OTM call)
Net debit ~$1.47 (cost ~$147). Max profit ~$8.53 (~$853) if SMH closes around 5% higher; breakeven roughly 3.2% above spot. Logic: if today's flush is an overshoot and buyers step back in, the call side is the relatively cheap way to express it (lower IV than the put side).

for illustration only, not investment advice
Options can expire worthless. Wrong direction, or too small a move, and the premium is gone. On Broadcom specifically, that ~90% IV crushes right after the print, a correct-direction bet can still lose if the move is smaller than priced. Low cost ≠ low risk. This content is provided by the $100 Options Trading Club for educational and informational purposes only and does not constitute investment advice, a recommendation, or an offer or solicitation to buy or sell any security or to adopt any trading strategy. Options trading involves significant risk and is not suitable for all investors; you may lose the entire premium paid. Consider your objectives and risk tolerance,and consult a licensed financial professional before trading. Past performance and hypothetical examples do not guarantee future results.
Disclaimer: Moomoo Technologies Inc. is providing this content for information and educational use only.Read more


Comments
to post a comment
28
12